

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Global Cake Pans Market Hits $1.59B in 2025, Forecasted to Reach $2.46B by 2032

Navigating the Global Cake Pans Market: Strategic Intelligence for 2026 and Beyond
The global kitchenware sector is experiencing a renaissance, driven by a resurgence in home baking, the expansion of artisanal bakery chains, and evolving consumer preferences for specialized cookware. At the heart of this ecosystem lies the cake pans market, a foundational segment that bridges raw material manufacturing, retail distribution, and end-user culinary performance. As we move further into the mid-2020s, understanding the trajectory, competitive architecture, and regulatory contours of this market is no longer optional for stakeholders. It is a prerequisite for resilient growth.
PW Consulting is pleased to introduce our latest comprehensive study: the Worldwide Cake Pans Market. This report is engineered to convert macro-level industry signals into actionable strategic intelligence. Designed for executives in manufacturing, supply chain management, retail leadership, and investment analysis, our research provides a rigorous, data-driven foundation for navigating the forecast period from 2026 to 2032.
Market Trajectory and the 2026 Inflection Point
The cake pans market has demonstrated remarkable resilience and growth over the past half-decade. Drawing on historical data from 2020 through 2025 and projecting forward, our analysis reveals a sector moving from a global valuation of approximately 1.1 billion USD in 2020 to a substantial 1.58 billion USD by 2025. This expansion underscores a consistent upward demand curve, influenced by heightened culinary engagement, the proliferation of baking content across digital platforms, and steady commercial bakery investments.
Looking ahead, the forecast period from 2026 to 2032 is positioned for sustained momentum. The market is projected to continue its growth trajectory, reaching a valuation that will underscore the segment's increasing strategic weight within the broader houseware and specialty retail categories. A compound annual growth rate of 6.48 percent reflects not only steady consumer demand but also the ongoing maturation of distribution networks and product innovation cycles. For decision-makers, this CAGR is more than a numerical indicator; it represents the pace at which capital allocation, inventory planning, and product development strategies must be calibrated to maintain competitive parity.
Structural Dynamics: Material, Channel, and Regional Interplay
The evolution of the cake pans market is fundamentally shaped by three intersecting forces: material innovation, channel transformation, and regional divergence in purchasing behavior. Our research dissects these dimensions to reveal how value is created, captured, and contested across the supply chain.
Material composition remains a critical battleground. The market is anchored by a diverse array of substrates, each offering distinct performance profiles, cost structures, and end-user value propositions. Metal-based solutions continue to dominate a significant portion of total revenue, driven by their thermal conductivity, durability, and compatibility with both home and commercial baking environments. Within this category, aluminum-based products, including anodized variants, command a prominent share, reflecting their widespread adoption among professional bakeries and discerning home users alike. Carbon steel and aluminum-composite alternatives further expand the material landscape, offering manufacturers flexible pathways to balance performance, weight, and production costs. Meanwhile, non-metallic categories such as silicone, glass, and ceramic have cultivated dedicated followings, appealing to consumers and artisans who prioritize non-stick convenience, aesthetic presentation, and specialized heat-retention properties. This multi-material ecosystem creates a complex value matrix where product positioning, price tiering, and target-user segmentation are inextricably linked.
Worldwide Cake Pans Market
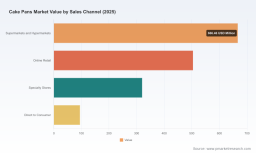
The distribution architecture is undergoing a parallel transformation. Traditional brick-and-mortar formats, particularly supermarkets and hypermarkets, remain powerful engines of volume, leveraging their broad foot traffic and one-stop shopping appeal. At the same time, online retail channels have matured into formidable growth vectors, accelerated by improved logistics infrastructure, social commerce integration, and the consumer shift toward digital discovery and direct purchasing. Specialty stores and direct-to-consumer models further enrich the channel mix, offering niche products, curated assortments, and brand storytelling opportunities that resonate with premium and enthusiast segments. The interplay between these channels dictates not only revenue allocation but also the strategic priorities around brand visibility, inventory velocity, and customer acquisition cost management.
Regionally, the market exhibits distinct demand characteristics that reflect local baking traditions, economic conditions, retail maturity, and import-export dynamics. North America and Europe together represent mature, high-value arenas where brand differentiation, product quality, and regulatory compliance are paramount. Asia Pacific presents a compelling growth narrative, fueled by urbanization, rising disposable incomes, and the expanding footprint of modern retail and e-commerce. Latin America and the Middle East and Africa, while representing more nascent but promising spaces, offer long-term potential tied to the gradual formalization of retail channels and the growing visibility of global baking culture. Our report maps these regional nuances without reducing them to static snapshots, instead providing the contextual intelligence necessary to prioritize market entry, expansion, or resource reallocation with confidence.
Competitive Architecture: Incumbents, Innovation, and Strategic Positioning
The global cake pans market is characterized by a moderately concentrated competitive landscape, with a handful of leading players capturing a meaningful portion of total industry revenue, while a broader tier of specialized and regional manufacturers competes on differentiation, pricing, and channel access. Our analysis identifies a diverse set of enterprises that collectively define the market's strategic contours.
Established North American manufacturers such as Nordic Ware and Wilton Brands LLC have long been synonymous with reliable, design-forward bakeware, serving both professional decorators and home bakers through iconic product lines that span round layer pans, Bundt varieties, and seasonal formats. USA Pan and Fat Daddio's compete in the commercial-grade and performance-oriented segments, emphasizing aluminized steel and anodized aluminum constructions engineered for even heating, non-stick efficacy, and durability under repeated professional use. Calphalon LLC extends this premium logic into the broader consumer space, leveraging its reputation for high-end non-stick bakeware to capture users who prioritize longevity and consistent results.
International manufacturers contribute critical depth to the competitive field. Emile Henry and Le Creuset, rooted in French craftsmanship traditions, offer ceramic and enameled cast iron alternatives that appeal to artisanal and premium home baking audiences seeking superior heat retention and distinctive culinary aesthetics. Kaiser Bakeware, based in Germany, reinforces the market's emphasis on engineered quality, supplying bakeware designed for both home and professional environments. On the industrial and supply-chain side, American Pan and Parrish Magic Line focus on the commercial bakery and stock-pan segment, providing scalable aluminum and coated solutions for high-volume production. China-based Wuxi Hongbei Bakeware Co., Ltd. represents the growing presence of industrial-scale manufacturers capable of delivering custom and stock configurations for bakery operations that prioritize cost efficiency and production flexibility.
This competitive mosaic is neither static nor frictionless. Recent market events underscore the volatility that can ripple through adjacent product categories and influence broader consumer confidence. In February 2026, for instance, regulatory actions escalated a product recall involving certain cake mix varieties due to undeclared allergens, highlighting the critical importance of stringent quality control, transparent labeling, and supply chain traceability for any company operating in the baked goods ecosystem. Although such recalls originate within the mix segment, they send ripple effects across the entire value chain, reinforcing the need for pan manufacturers and distributors to align their quality assurance protocols, packaging integrity, and compliance frameworks with the highest industry standards.
Regulatory Pressures, Input Costs, and the External Environment
Strategic decision-making in the cake pans market cannot be divorced from the external environment in which it operates. Raw material economics, regulatory mandates, and trade policy dynamics all exert direct or indirect pressure on manufacturing costs, pricing strategies, and market access.
Input cost volatility remains a persistent consideration. Global wheat prices, for example, have experienced notable fluctuations, reflecting broader agricultural market conditions that influence the economics of baking at large. While cake pans are not directly derived from agricultural commodities, their demand is closely tied to the overall baking activity of households, bakeries, and foodservice operators. When input costs for core baking ingredients rise or become unpredictable, end-users may adjust purchasing frequency, recipe complexity, or equipment investment cycles. Manufacturers and channel partners must therefore anticipate these demand-side elasticity effects when forecasting volume, planning production runs, and setting price architectures.
Regulatory compliance represents another layer of strategic complexity. Food safety authorities in major markets, including the U.S. FDA, mandate clear labeling of major food allergens such as wheat, eggs, and milk for packaged baked goods. For cottage food operations and small-scale producers, labeling requirements extend to producer identification, product naming, and applicable allergen declarations. Although these mandates primarily target food products rather than cookware, they shape the broader operating environment in which cake pans are purchased, used, and evaluated. Manufacturers that supply professional bakeries or partner with commercial food producers must ensure their product documentation, coating specifications, and material disclosures support rigorous compliance workflows downstream.
Trade policy developments further complicate the landscape. The implementation of broad additional ad valorem import tariffs, beginning at a baseline of 10 percent on goods from a range of trading partners, introduces new cost and sourcing considerations for an industry that relies on international supply chains, cross-border component flows, and globally distributed manufacturing footprints. Companies must evaluate how tariff exposure affects landed costs, supplier diversification strategies, inventory positioning, and final price pass-through to consumers. In this environment, the ability to model tariff scenarios, stress-test margin assumptions, and identify alternative sourcing pathways becomes a core competitive capability rather than a peripheral administrative function.
What the Report Delivers: A Toolkit for Strategic Action
Our Worldwide Cake Pans Market report is structured to move beyond descriptive analysis and toward executive-grade decision support. It is designed to be a practical reference for shaping product roadmaps, refining market entry tactics, optimizing channel strategies, and anticipating competitive responses. The report's scope encompasses, but is not limited to, the following areas of actionable insight:
- Comprehensive market sizing and historical tracking from 2020 through 2025, establishing a validated baseline for assessing growth momentum and structural shifts.
- Forward-looking revenue projections through 2032, enabling scenario planning, target setting, and investment prioritization across the forecast horizon.
- Deep segmentation analysis across material types, sales channels, and geographic regions, revealing where value concentrates, where growth accelerates, and where differentiation is most defensible.
- Competitive profiling of leading manufacturers, including product positioning, brand strategy cues, channel emphasis, and capabilities relevant to commercial and consumer segments.
- Assessment of market concentration dynamics, providing context on the balance of power between dominant incumbents and emerging or niche players.
- Evaluation of external drivers and constraints, including raw material economics, regulatory frameworks, import tariff implications, and consumer behavior trends that influence demand cycles.
- Strategic implications and strategic recommendations tailored to manufacturers, distributors, retail operators, and investors seeking to align their portfolios with the most promising growth vectors.
By integrating quantitative rigor with qualitative industry intelligence, the report equips readers to answer the questions that directly affect enterprise performance: Which segments offer the most favorable risk-adjusted growth? Where should product innovation and material investment be focused? How should channel strategies evolve in response to shifting retail dynamics and digital commerce acceleration? What competitive moves are likely from incumbents and smaller challengers? And how should organizations prepare for regulatory and trade-policy scenarios that could reshape cost structures and market access?
Non-Stick Pans Market
Why This Research Matters for 2026 Decision-Making
The 2026 to 2032 window will be defined by organizations that can translate market signals into disciplined execution. As the global cake pans market continues to expand at a measured but meaningful pace, stakeholders face a dual mandate: capture share in high-potential segments while defending against cost pressures, competitive intensification, and external shocks that can erode margin and disrupt planning cycles. Success in this environment requires more than intuition; it requires a structured understanding of market size, growth rate, segmentation patterns, competitor capabilities, and the macro forces shaping the operating terrain.
Our research is built to serve that need. It provides the evidentiary foundation for strategic choices, from long-range capacity planning and product development investment to pricing architecture, channel mix optimization, and market prioritization. It also highlights the operational discipline required to navigate an environment where input costs fluctuate, regulatory expectations intensify, and trade policy introduces new uncertainty into cross-border commerce.
Access the Full Intelligence Suite
This article offers a strategic preview of the landscape, but the complete analytical depth, detailed segmentation breakdowns, granular competitive assessments, and forward-looking scenario analysis reside within the full Worldwide Cake Pans Market report. For executives and analysts who require precise data, comprehensive segmentation detail, and actionable strategic guidance to inform 2026 planning and beyond, the full study is essential.
To explore the complete findings, access detailed market size trajectories, review in-depth competitor profiles, and unlock the strategic recommendations designed to support informed decision-making, we invite you to visit the source webpage and obtain the full report. Equip your organization with the intelligence needed to navigate the market's next phase of growth with clarity, confidence, and strategic advantage.
For detailed analysis of this topic, please visit the official page: Worldwide Cake Pans Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com