

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Telescopic Cylinder Market to Hit $3.1B by 2032, CAGR 5.12%

Navigating the Future of Motion Control: Why the 2026 Telescopic Cylinder Market Demands Strategic Clarity
In the rapidly evolving landscape of industrial hydraulics, telescopic cylinders remain a critical enabler of motion control across heavy-duty sectors. From construction machinery operating in space-constrained urban environments to agricultural equipment demanding reliable long-stroke performance, these components bridge the gap between compact retracted lengths and extended operational reach. As we move into 2026, understanding the trajectory of this market is no longer optional for executives and strategic planners. It is a prerequisite for capital allocation, supply chain resilience, and competitive positioning.
This article introduces our latest comprehensive research release, the Worldwide Telescopic Cylinder Market study, which provides decision-makers with the granular intelligence needed to navigate a sector undergoing steady structural growth, shifting cost dynamics, and intensifying competitive maneuvering. Below, we outline the strategic rationale behind this analysis, preview the depth of coverage within the report, and explain how the findings can directly inform enterprise decisions throughout the 2026 to 2032 forecast horizon.
The Macro Trajectory: Sustained Growth Embedded in Infrastructure and Industrial Expansion
The telescopic cylinder market has demonstrated a consistent pattern of expansion over the past half-decade, driven by long-term investments in construction, material handling, and agricultural mechanization. Historical data from 2020 through 2025 reveals a revenue base that grew from approximately 1,725 million USD to 2,185 million USD, reflecting both post-pandemic industrial recovery and the compounding effect of sustained capital expenditure in mobile and stationary hydraulic systems. The year 2024 marked a notable inflection point, with market revenue reaching 2,149 million USD, before stabilizing at 2,185 million USD in 2025 as supply chain normalization and raw material price volatility settled into a new equilibrium.
Looking forward, our base forecast projects the global market to reach 2,299 million USD in 2026, representing a measured acceleration as manufacturing output scales and demand from key end-use verticals stabilizes. The growth momentum continues through the forecast window, with the market anticipated to expand to 2,527 million USD by 2027, 2,536 million USD by 2028, and 2,614 million USD by 2029. By 2030, revenue is projected to approach 2,799 million USD, ultimately reaching an estimated 3,100 million USD by 2032. This progression translates to a compound annual growth rate of 5.12 percent across the 2026 to 2032 period, signaling a market characterized by steady, compounding expansion rather than episodic spikes.
For strategic planners, this trajectory carries important implications. A CAGR of this magnitude suggests that demand will reliably track broader industrial activity, but the path to capturing that growth will depend on product differentiation, regional supply chain optimization, and the ability to hedge against input cost volatility. The forecast window also highlights the need to plan for multi-year capacity decisions, supplier diversification, and customer segment prioritization well before market conditions shift.
Segmentation Intelligence: How Type, Application, and Geography Shape Competitiveness
Few market analyses deliver as much actionable value as a rigorous segmentation breakdown. Our research dissects the worldwide telescopic cylinder market along three primary axes: product type, application vertical, and geographic region. Rather than presenting surface-level totals, the report maps how revenue distributes across these segments and what that distribution means for pricing power, production prioritization, and channel strategy.
From a product standpoint, the single-acting and double-acting categories serve distinctly different operational profiles. Single-acting designs continue to dominate in terms of absolute market share, favored for their structural simplicity, reduced maintenance burden, and suitability for applications where gravity or external loads assist retraction. Double-acting variants, while representing a smaller share of total revenue, command strategic importance in scenarios requiring controlled extension and retraction under variable load conditions, making them essential for advanced machinery architectures and precision actuation requirements.
The application landscape further illustrates the diversity of demand drivers. Construction and mining remain the largest application vertical, leveraging telescopic cylinders for dump bodies, excavator booms, and heavy lifting frameworks that must operate under extreme duty cycles. Material handling represents the next major pillar, where telescopic designs are integral to lifts, platforms, and hydraulic stacking systems that require reliable extension under repeated load cycles. Agriculture follows as a significant consumer, with telescopic cylinders deployed in spray booms, seeding equipment, and harvesting platforms where long reach and field durability are non-negotiable. Aviation and other specialized segments round out the demand mix, utilizing high-reliability designs for aircraft servicing platforms and niche industrial applications that prize precision and customized performance envelopes.
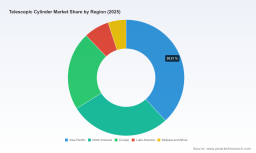
Regionally, the report examines how market maturity, industrial policy, and infrastructure investment patterns create distinct competitive arenas. Asia Pacific stands out as the largest revenue-generating region, reflecting the concentration of manufacturing activity, urban construction density, and broad-based agricultural mechanization. North America and Europe follow as mature, high-value markets where performance specifications, compliance standards, and customization requirements shape procurement decisions. Latin America and the Middle East and Africa collectively represent smaller but strategically relevant demand pools, often driven by resource extraction, infrastructure upgrades, and selective industrial modernization projects. While absolute segment values and regional splits are fully disaggregated within the full report, the strategic takeaway is clear: geographic diversification, localized support capabilities, and segment-specific engineering investments will separate market leaders from the rest of the field.
Competitive Landscape: Convergence, Customization, and the Battle for Specialization
The telescopic cylinder market is populated by a mix of global hydraulic powerhouses, specialized mid-tier manufacturers, and regional specialists that compete on engineering depth, lead time, and application-specific customization. Our research profiles a broad set of key companies, mapping their headquarters, product capabilities, and strategic positioning to help readers understand who competes where, and why.
Parker Hannifin Corporation, based in Cleveland, Ohio, remains a defining presence in the space, offering both single-acting and double-acting telescopic hydraulic cylinders through product lines such as its Series SAT. The company serves a wide spectrum of end markets, including truck, mining, material handling, refuse, construction, and industrial sectors, delivering standard and custom solutions that reflect its scale and engineering breadth. In mid-2025, Parker Hannifin expanded its smart cylinder portfolio with new IoT-enabled actuators featuring sensor-integrated rods and advanced sealing systems, innovations that are directly applicable to telescopic designs intended for harsh environments. This move signals a broader industry trend toward intelligent actuation, where embedded sensing, predictive maintenance capabilities, and higher reliability standards are becoming competitive differentiators rather than optional enhancements.
Bosch Rexroth AG, headquartered in Lohr am Main, Germany, provides telescopic cylinders as part of its broader hydraulic cylinder portfolio, with a pronounced focus on industrial, mobile, and heavy-duty applications. Its emphasis on smart solutions and large-bore capability positions it well for customers who require integrated system-level performance rather than isolated component procurement. Eaton Corporation, based in Dublin, Ireland, manufactures telescopic cylinders within its hydraulics division and serves mobile equipment, construction, and industrial sectors, reinforcing the importance of global supply footprints and cross-division engineering synergies in a market where application support and service networks influence purchasing decisions.
HYDAC International GmbH, located in Sulzbach, Germany, supplies telescopic hydraulic cylinders for various industrial and mobile hydraulic systems, adding to the European engineering presence that values precision, filtration integration, and system reliability. On the North American side, Mailhot Industries, based in Saint-Jacques, Quebec, has established itself as a long-standing leader in hydraulic telescopic cylinders since 1956, specializing in reliable, durable nitrided telescopic cylinders engineered for harsh and extreme conditions. Its historical depth and reputation for ruggedness underscore the enduring premium placed on proven performance in demanding duty cycles.
Other notable participants illustrate the breadth of specialization available to buyers. HSI Corporation, headquartered in Pekin, Illinois, focuses on custom single and double-acting multi-stage telescopic cylinders with large bore capabilities designed for precise application fit. Custom Hoist, Inc., in Huron, Ohio, produces telescopic cylinders widely used in dump trucks and heavy-duty applications, with multiple stage models stocked by distributors to support rapid deployment requirements. JARP Industries, based in the United States, manufactures custom hydraulic cylinder solutions including telescopic designs and operates as an acquired entity within the Mailhot Industries ecosystem, highlighting the consolidation dynamics that continue to reshape the competitive map. Texas Hydraulics, Inc., in Temple, Texas, offers rugged high-duty-cycle cylinders including telescopic and piggyback designs for demanding mobile equipment, while Aggressive Hydraulics, in Cedar, Minnesota, concentrates on fully custom-engineered telescopic hydraulic cylinders for agriculture, mining, and other specialized applications. In Asia, Yancheng Haite Machinery Technology Co., Ltd., in Yancheng, China, specializes in customizable telescopic hydraulic cylinders for global markets, and Wipro Enterprises, in Bangalore, India, produces hydraulic cylinders including telescopic models for construction and industrial use. Jiangsu Hengli Hydraulic Co., Ltd., also based in China, manufactures hydraulic cylinders with telescopic offerings for mobile and industrial equipment, reflecting the growing role of Asian manufacturers in both domestic and export-facing supply chains.
Collectively, these companies demonstrate that the competitive landscape is not a monolith. Market leadership is often defined by the ability to combine scale with specialization, standard products with custom engineering, and regional responsiveness with global manufacturing consistency. Our report examines concentration dynamics within the sector, noting that the top three players account for approximately 38.45 percent of market revenue, while the top five represent about 52.6 percent. This level of concentration suggests a market where scale advantages, brand recognition, and established distribution relationships matter, but where meaningful differentiation remains possible for firms that deliver superior application engineering, faster customization cycles, and robust quality assurance.
Industry Dynamics: Cost Pressures, Standards, and the Urban Construction Imperative
Beyond segment structures and competitor maps, the market environment itself is shaped by forces that directly affect margins, lead times, and product strategy. Raw material economics sit at the center of these dynamics. Steel constitutes nearly half of a hydraulic cylinder's production cost, and price fluctuations in high-grade steel and aluminum have a direct bearing on manufacturing margins. Dependence on volatile raw material prices has become a persistent challenge for telescopic cylinder producers, influencing not only unit economics but also final product pricing strategies, inventory planning, and the timing of long-term customer contracts.
Regulatory and trade dynamics add another layer of complexity. Tariffs on imported steel tubes, precision rods, seals, and machining components have increased production costs and extended lead times for manufacturers operating in North America and Europe. For companies that rely on global sourcing footprints, these trade-related frictions require careful supplier diversification, regional inventory buffering, and strategic negotiations with downstream customers to share or absorb cost pressures. In a market where customization cycles and application-specific engineering extend development timelines, even modest increases in component costs or delivery delays can erode profitability and weaken competitive responsiveness.
At the same time, the functional advantages of telescopic cylinders continue to reinforce demand in specific operating environments. Urban construction, in particular, favors telescopic designs because they deliver long strokes in compact retracted lengths required by space-constrained machinery. As cities intensify infrastructure development and equipment must navigate narrower job sites, elevators, and confined staging areas, the ability to achieve extended reach without sacrificing maneuverability becomes a decisive operational benefit. This demand driver is not merely a technical preference; it shapes procurement priorities, influences machinery design requirements, and reinforces the strategic value of manufacturers who can reliably deliver long-stroke performance in rugged, compact form factors.
Quality standards further define the market's baseline expectations. ISO 9001 certification serves as the foundational benchmark for quality in telescopic hydraulic cylinder manufacturing, and competitive differentiation increasingly depends on what lies beyond that baseline: advanced sealing systems, nitrided surface treatments, sensor integration, and application-specific validation. Recent industry activity reflects this evolution. For example, Hydreco Hydraulics showcased customized hydraulic cylinder solutions, including those for heavy-duty applications, at Bauma 2025 in Munich, illustrating how trade-show exposure and technical demonstrations continue to influence buyer expectations and supplier positioning across the heavy equipment ecosystem.
Worldwide Telescopic Cylinder Market
What the Report Delivers: Building a Decision-Ready Intelligence Foundation
The Worldwide Telescopic Cylinder Market study is designed to move beyond high-level forecasts and equip strategic, commercial, and operational leaders with the specific intelligence required to act. The report includes a detailed market overview anchored to a base year of 2025, with historical analysis spanning 2020 through 2025 and a forecast period extending from 2026 through 2032. All monetary values are presented in USD millions, providing a consistent framework for comparing revenue evolution, growth rates, and segment contributions across time.
Readers will find a structured segmentation analysis by region, product type, and application, with revenue distributions and strategic interpretations that support portfolio planning, capacity allocation, and market-entry evaluation. The competitive landscape section offers detailed company profiles, outlining headquarters, product offerings, application focus, and recent developments for leading participants. This includes coverage of product launches, trade-show activity, and other milestones that reveal how competitors are adjusting their portfolios in response to market conditions and technological expectations.
The research also integrates supply-side and demand-side dynamics, including raw material cost sensitivity, trade and tariff impacts, standards and certification baselines, and macro-level application drivers such as space-constrained urban construction. These insights are presented not as isolated facts but as interconnected forces that affect pricing, sourcing, product design, and market timing. The report further examines market concentration and competitive structure, enabling readers to assess the balance between scale-driven incumbents and specialized challengers, as well as the strategic implications of consolidation and portfolio expansion.
Strategic Value for 2026 Decision-Making
For executives planning 2026 initiatives, this research serves as a decision-support framework across multiple business functions. Commercial leaders can use the segmentation and application data to prioritize high-value verticals, tailor value propositions to specific end-use requirements, and identify where customization capabilities can command premium positioning. Operations and supply chain teams can integrate raw material sensitivity, tariff exposure, and regional cost structures into sourcing strategies, inventory planning, and contract terms that protect margin while maintaining delivery reliability. Product and engineering teams can align development priorities with the market's emphasis on long-stroke compact designs, durability for harsh environments, and the growing importance of embedded sensing and intelligent actuation features.
Corporate development and strategy functions will also benefit from the competitive mapping and concentration analysis. Understanding which players hold scale advantages, which specialize in rugged or custom designs, and how recent product and trade-show developments are reshaping buyer expectations can inform partnership considerations, geographic expansion plans, and portfolio gap analysis. In a market where the top five companies account for slightly more than half of total revenue, there remains meaningful room for firms that can combine dependable standard offerings with differentiated custom engineering and application-specific support.
Importantly, the study is structured to support both near-term tactical decisions and longer-term capital planning. The 2026 to 2032 forecast horizon gives leaders a multi-year view of expected market expansion, enabling more disciplined investment timing, scenario planning for demand fluctuations, and alignment of manufacturing or service capacity with projected revenue growth. The inclusion of historical performance from 2020 through 2025 further strengthens the analytical foundation by contextualizing current market size within a recent period of disruption, recovery, and recalibration.
Access the Full Intelligence
The market overview, segmentation logic, competitive analysis, and industry dynamics described here reflect only a portion of what the full report offers. Core regional splits, application-level revenue distribution, type-level breakdowns, detailed company profiles, and the complete multi-year forecast are presented in full within the study to support precise quantification and scenario modeling. Readers seeking the granular data required for budget planning, market-entry analysis, supply chain optimization, or competitive benchmarking will find the complete dataset essential.
Telescopic Jack Market
To explore the full Worldwide Telescopic Cylinder Market research and access the underlying figures, segmentation tables, and company-level intelligence in their entirety, visit the source page for the complete report and supporting materials.
For detailed analysis of this topic, please visit the official page: Worldwide Telescopic Cylinder Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com