

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Foot Traffic Market Hits $8.62B in 2025, Poised to Reach $26.9B by 2032

Unlocking Customer Location Intelligence: Strategic Imperatives for the 2026 Market Landscape
Introduction: The Evolution of Physical-Digital Convergence
The boundary between digital strategy and physical presence has dissolved. In 2026, organizations that operate solely on online engagement metrics while ignoring in-person footfall dynamics are operating with half a map. The Worldwide Foot Traffic and Customer Location Intelligence Solution Market has matured rapidly from a niche analytics supplement into a core infrastructure layer for retail, real estate, transportation, healthcare, and smart city operations. This article serves as an executive preview of our latest market research, designed to illuminate the strategic vectors that will define enterprise decision-making through 2032. Readers seeking granular segmentation matrices, proprietary survey findings, and competitor benchmarking tables are invited to explore the full report via the source portal.
The modern enterprise must answer questions that were once dismissed as anecdotal: Where do consumers originate before visiting a store? How do seasonal mobility shifts alter trade area profitability? Which physical touchpoints deliver measurable conversion lift versus dead weight? Location intelligence answers these questions with precision. It fuses anonymized mobility data, sensor-derived counts, geospatial mapping, and behavioral modeling into operational intelligence that directly informs site selection, staffing allocation, inventory planning, marketing spend optimization, and asset valuation.
Macro Trajectory: Why the Growth Curve Matters for Decision-Makers
The market has demonstrated sustained expansion across the historical observation window and is positioned for an accelerated trajectory in the forthcoming forecast horizon. From a base exceeding four billion USD in 2020, revenue climbed past 8.6 billion USD by 2025, reflecting heightened enterprise demand for actionable proximity insights. This momentum carries forward sharply, with the projected annual growth rate of approximately 15.65 percent driving valuation toward nearly 10.2 billion USD in 2026 and surpassing 26.8 billion USD by 2032.
The implications are clear. Capital is flowing into location intelligence not as an experimental capability but as a structural requirement for competitive resilience. Procurement leaders must evaluate vendor ecosystems with long-term scalability in mind. Strategy teams should anticipate that early-mover advantages in foot traffic analytics will compound as data networks deepen and AI-driven inference models become more sophisticated. Investors and board members need visibility into whether their organization's current data architecture can absorb the kind of continuous, high-frequency spatial insights that the market trajectory implies will become table stakes within half a decade.
Crowd Management Solution Market
Solution Architecture and Technology Interplay
Location intelligence solutions are delivered through a layered stack that combines software and analytics platforms, hardware and sensor systems, and professional and managed services. The software layer typically anchors the value proposition: it ingests multi-source data, normalizes disparate formats, applies machine learning models, and surfaces dashboards that translate raw observations into decision-ready intelligence. Hardware components range from in-store sensors and computer-vision counters to environmental and proximity detection units that feed ground-truth signals into broader platforms. Managed services bridge the gap between tool deployment and business outcomes, offering implementation guidance, custom modeling, and ongoing analytical support.
Technology selection is no longer a binary choice between beacon-based tracking and satellite positioning. Wi-Fi and Bluetooth/BLE frameworks continue to provide accurate micro-level presence detection within controlled environments. GPS and satellite positioning supply macro-mobility context, enabling organizations to understand catchment areas, route behaviors, and regional visitation flows. AI-powered video analytics represent a fast-evolving frontier, converting visual streams into demographic, dwell-time, and pathing insights while raising distinct considerations around privacy-by-design architecture. Infrared and thermal sensor approaches complement these methods where lighting conditions, occlusion, or data governance constraints make optical processing less practical. The sophisticated buyer evaluates not single technologies but the interoperability of heterogeneous signals, seeking platforms that can triangulate insights rather than rely on a single sensing modality.
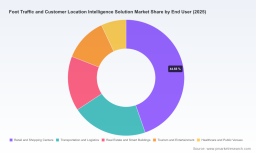
End-User Demand: How Different Verticals Convert Location Data into Operating Leverage
Foot traffic intelligence is not a monolithic use case. Demand patterns diverge considerably across sectors, each extracting a distinct form of economic value from spatial data.
- Retail and shopping centers use location analytics to optimize store layouts, calibrate promotional calendars, evaluate cannibalization risk, and refine trade area definitions. Site selection teams increasingly treat footfall velocity and visitation composition as non-negotiable inputs for new openings and lease negotiations.
- Transportation and logistics operators leverage movement intelligence to align service frequency with passenger and freight flows, reduce idle capacity, and improve last-mile planning. The discipline of matching supply to actual demand patterns rather than assumed averages is a direct productivity driver.
- Real estate and smart buildings apply occupancy metrics to manage tenant mix, forecast amenity utilization, and enhance property-level operational efficiency. As commercial portfolios adapt to evolving work and consumption habits, asset managers increasingly require visitation evidence to validate pricing and leasing strategies.
- Tourism and entertainment venues utilize flow analytics to manage crowd density, time-entry pacing, and experiential offerings, aligning throughput with guest satisfaction and safety tolerances.
- Healthcare and public venues deploy people counting and zone-level occupancy insights to improve patient flow, staff allocation, and space utilization, especially in environments where congestion directly affects service quality and safety.
What unites these verticals is the realization that spatial behavior is a lagging indicator of past planning assumptions and a leading indicator of future performance. The enterprises that institutionalize location intelligence treat it as an operational thermostat rather than a periodic dashboard.
Competitive Landscape: Differentiated Approaches in a Consolidating Field
The vendor ecosystem spans data aggregators, analytics platform builders, sensor manufacturers, GIS specialists, and managed-services providers. Market concentration remains moderate, meaning that no single vendor dominates the entire value chain, but a cadre of well-capitalized public and private players is actively extending their stack depth and ecosystem reach.
Several archetypes have emerged. Platform-first analytics providers construct multi-source data pipelines and partner networks to deliver visitation trends, trade area modeling, and consumer behavior insights. GIS and spatial analysis specialists contribute foundational mapping, spatial statistics, and site-performance evaluation capabilities that complement mobility datasets. Sensor and in-store analytics vendors focus on ground-truth measurement within physical environments, converting visual or proximity signals into people counts, heatmaps, pathing, and conversion metrics. Data infrastructure and mobility data firms supply anonymized movement records and points-of-interest context that feed third-party platforms. The most competitive vendors increasingly differentiate through ecosystem integrations, privacy-compliant data sourcing, and domain-specific model tuning rather than raw data volume alone.
Recent market activity underscores this orientation toward integration, thought leadership, and product deepening. In early 2026, major platform participants continued to emphasize the bifurcation of retail performance and the need for nuanced consumer behavior interpretation in economic development and commercial strategy forums. Simultaneously, data integrations between foot traffic intelligence providers and commercial real estate platforms have accelerated, reflecting demand for asset- and REIT-level consumer behavior insights that connect physical visitation patterns to valuation, leasing, and asset management workflows. Parallel product enhancements in retail site selection tooling have introduced more rigorous cannibalization rate calculations and trade area overlap modeling, signaling that the market is moving from descriptive footfall reporting to prescriptive optimization.
Regulatory and Structural Dynamics Shaping Deployment Strategy
The commercial upside of location intelligence is inseparable from the regulatory environment in which it operates. Data sovereignty and localization requirements in certain jurisdictions mandate that mobility and location data be stored and processed within national borders, constraining cross-border intelligence architectures and forcing vendors and buyers to design regional data residency strategies. In parallel, cross-jurisdictional legal frameworks such as the U.S. CLOUD Act affect how international enterprises evaluate data-handling practices, particularly when platform providers operate under multiple legal exposures simultaneously. These forces are not peripheral compliance footnotes; they influence vendor selection, contractual data processing terms, and architecture decisions around where analytics workloads run.
Spectrum management policy also intersects with the sensing layer. Ongoing regulatory and technical efforts to improve wireless spectrum sharing and utilization have relevance for the transmission reliability and density of Bluetooth, Wi-Fi, and other proximity sensing modalities that underpin parts of the location intelligence stack. While these developments may appear abstract, they affect real-world signal quality, deployment cost curves, and the long-term robustness of sensor-dependent installations in dense urban and indoor environments.
Worldwide Foot Traffic and Customer Location Intelligence Solution Market
Forward-looking enterprises are therefore embedding regulatory diligence into procurement cycles. They are asking vendors about data provenance, anonymization standards, retention policies, regional processing options, and the governance audits available to support compliance teams. In this market, trust is a competitive asset, and privacy-preserving design is increasingly a purchasing requirement rather than a desirability factor.
Strategic Implications for Enterprise Decision-Makers in 2026
For executives shaping 2026 plans, the central question is not whether to use location intelligence but how to operationalize it at the right scale and with the right governance.
- Align foot traffic intelligence with core KPIs. Location data should be wired into the metrics that already drive board-level attention: sales per square foot, conversion rates, labor productivity, asset occupancy, site cannibalization, and customer lifetime value. Insights that live in isolated analytics sandboxes do not inform capital allocation.
- Adopt a layered sensing strategy. No single data source captures the full picture. Combining macro-mobility context with in-store or in-venue sensing, and supplementing both with geospatial analytics, produces more resilient inference than any standalone feed.
- Invest in integration before customization. Platforms that connect cleanly to existing CRM, ERP, lease management, and workforce scheduling systems deliver faster time-to-value than bespoke models that require permanent specialized maintenance.
- Treat privacy and compliance as architecture, not add-ons. Evaluate vendors on data sourcing transparency, anonymization rigor, regional processing capability, and auditability. In a market with rising regulatory scrutiny, procurement documentation should reflect these dimensions explicitly.
- Plan for compounding data network effects. As more entities adopt location intelligence, benchmark data, model accuracy, and comparative context improve. Organizations that deploy early and steadily expand usage will benefit from richer baselines and more refined predictive signals than those who defer.
Conclusion: From Market Intelligence to Operational Advantage
The Worldwide Foot Traffic and Customer Location Intelligence Solution Market is moving from rapid expansion to functional maturation. Revenue scales, technology diversification, and ecosystem integration all point toward a market where spatial insight becomes embedded in everyday operational decision-making rather than treated as a specialized analytics project. The strategic winners in 2026 and beyond will be those who translate location intelligence into measurable operating improvements: sharper site selection, more efficient staffing and space utilization, better trade area understanding, and more defensible asset valuation supported by empirical visitation evidence.
This executive overview has outlined the market trajectory, solution architecture, vertical demand patterns, competitive archetypes, and regulatory dynamics that frame the decision environment. It is necessarily a high-level synthesis. The full market research report provides the detailed segmentation analysis, granular segmentation breakdowns, vendor profiling depth, regional dynamics, technology adoption patterns, and forward scenarios required for precise procurement, investment, and strategic planning decisions. Readers seeking that complete intelligence should access the source report to obtain the full dataset, segmentation matrices, and actionable end-user profiles that accompany this analysis.
For detailed analysis of this topic, please visit the official page: Worldwide Foot Traffic and Customer Location Intelligence Solution Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com