

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Category: market research
PW Consulting: Metallocene Catalyst Market Hits $302.45M in 2025,CAGR 6.85% Forecast to 2032
By pmarketresearch, 2026-09-15
Strategic Horizon: Why Metallocene Catalyst Intelligence Defines 2026 Decision-Making
The global metallocene catalyst industry stands at a pivotal inflection point. As we transition into the forecast horizon of 2026 through 2032, the market is projected to expand from a 2026 baseline to a substantial 2032 valuation, reflecting a compound annual growth rate of 6.85%. This trajectory is not merely a statistical projection; it represents a structural recalibration of polyolefin manufacturing, driven by precision chemistry, evolving regulatory mandates, and shifting raw material economics. Our newly released market research study dissects this evolution with granular rigor, delivering an actionable intelligence framework designed specifically for executive decision-makers navigating capital allocation, product portfolio optimization, and competitive positioning in the coming decade.
For industry leaders, 2026 is not simply another planning cycle. It is a year where feedstock cost volatility, regional capacity expansions, and sustainability-driven specification shifts will converge to redefine margin structures and technology adoption curves. The metallocene catalyst segment, historically positioned as a premium alternative to conventional polymerization systems, is now experiencing accelerated commercial validation across high-performance film, specialty packaging, and advanced polyolefin grades. Understanding where value pools are forming, which technological architectures are gaining commercial traction, and how competitive players are structuring their go-to-market strategies requires more than high-level industry commentary. It demands a systematically constructed analytical scaffold that maps historical performance, forward-looking consumption patterns, and strategic inflection points onto executable business intelligence.
This research publication has been engineered to serve as that scaffold. By integrating a decade of historical performance data alongside a seven-year forward projection, the study captures both the stabilizing forces and the disruptive currents reshaping the catalyst landscape. The narrative that follows outlines the structural components of the report, highlights the competitive architecture defining the sector, and contextualizes the macroeconomic and regulatory currents that will dictate pricing dynamics, capacity utilization, and technology selection through 2032.
Decoding the Growth Trajectory: From Historical Momentum to Forward Outlook
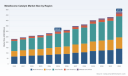
The market's historical arc from 2020 through 2025 establishes a clear foundation of sustained expansion. Revenue progression over this period demonstrates consistent upward momentum, reflecting the gradual but decisive penetration of metallocene-enabled polymer grades into mainstream industrial applications. By 2025, the market had consolidated its position at a meaningful valuation, setting the stage for an accelerated deployment phase in the forecast window. The projected growth curve through 2032 indicates a market that will not only maintain its expansion tempo but will also experience structural shifts in consumption geography, product architecture preference, and end-use specification requirements.
A compound annual growth rate of 6.85% signals more than steady demand; it reflects a compounding effect of technology adoption, downstream converter requirements for thinner-gauge and higher-performance films, and the ongoing substitution of conventional catalyst platforms in targeted high-margin applications. This growth rate is particularly significant given the premium positioning of metallocene chemistry and the inherent cost differentials that have historically constrained broader adoption. As manufacturing scale improves, process integration deepens, and downstream demand for precision polymer architecture intensifies, the economic equation surrounding metallocene catalyst deployment continues to realign.
Metallocene Catalyst Market
Report Architecture: What Decision-Makers Will Find Inside
Our market research publication has been structured to translate complex market signals into executable strategic insight. Rather than presenting static figures in isolation, the study constructs a multi-dimensional analytical framework that enables leadership teams to evaluate opportunity, assess risk, and benchmark competitive positioning with precision. The report encompasses the following core components:
- Historical Baseline and Forward Projection Modeling : A comprehensive dataset tracing revenue evolution across the historical observation window and extending through the full forecast horizon, allowing stakeholders to stress-test growth assumptions and map capacity planning against projected demand curves.
- Technology Segmentation Analysis : A detailed examination of catalyst architecture classifications, including standard metallocene configurations and dinuclear formulations, with emphasis on performance differentiation, process compatibility, and application-specific performance profiles.
- Application-Driven Consumption Mapping : An exploration of how metallocene catalysts are distributed across polymer production pathways, including polyethylene, polypropylene, broader polyolefin manufacturing, and specialized industrial uses, highlighting where performance premiums justify technology investment.
- Competitive Landscape Profiling : Company-level assessments of leading catalyst producers and integrated polymer players, capturing product portfolio strategies, regional manufacturing footprints, partnership ecosystems, and recent commercial developments that signal future market directionality.
- Market Concentration and Structural Dynamics : Analytical perspective on industry consolidation patterns, competitive intensity, and the strategic implications of concentrated market share among top-tier participants.
- Regulatory and Raw Material Context Integration : A synthesized view of environmental compliance trajectories, packaging mandates, feedstock cost movements, and price transmission mechanisms that will influence catalyst economics and downstream adoption velocity.
Each section is designed to operate independently as a reference module while functioning cohesively as an integrated strategic dashboard. Executive teams can extract standalone insights for functional planning or leverage the full architecture for enterprise-level scenario modeling and investment prioritization.
Competitive Architecture: Key Players and Strategic Positioning
The competitive landscape is defined by a cohort of technology-focused catalyst producers, integrated chemical manufacturers, and regional specialty players, each pursuing distinct go-to-market strategies and innovation roadmaps. Leadership in this space is not solely determined by scale; it is increasingly shaped by catalytic precision, process compatibility, customer-specific formulation capabilities, and the ability to align catalyst performance with downstream polymer grade requirements.
Among the prominent participants shaping the market's trajectory are Univation Technologies, W.R. Grace and Company, LyondellBasell Industries, Nouryon, Mitsui Chemicals, Ube Industries, Prime Polymer, Zibo Xinsu Chemical, Chevron Phillips Chemical, Daelim Industrial, SK Chemicals, and Mitsubishi Chemical. These firms operate across North America, Europe, and Asia, with product portfolios spanning gas-phase single-site catalyst systems, custom-synthesized metallocene architectures, specialty polyolefin catalyst formulations, and ligands engineered for activation and performance optimization. Their strategic differentiators range from proprietary process integration and high-extrusion-rate film architectures to custom manufacturing capabilities for complex organic intermediates and single-site catalyst activation systems.
Recent commercial events underscore the accelerating pace of technology selection and grade innovation. In September 2024, Indian Oil Corporation Ltd. selected Univation Technologies' UNIPOL PE Process integrated with metallocene catalyst technology for a world-scale polyethylene production line at Paradip, India, signaling robust demand for single-site catalyst deployment in large-capacity Asian manufacturing projects. Shortly thereafter, in October 2024, TotalEnergies SE launched a new metallocene polyethylene grade, Advanced Supertough 12AST05, targeting film and packaging applications with enhanced performance characteristics. These developments illustrate how catalyst architecture, process selection, and downstream grade innovation are converging to create differentiated value propositions in competitive procurement environments.
Metallocene Polyethylene Market
From a structural perspective, market concentration remains notably elevated among top-tier participants, with leading firms commanding a significant share of industry revenue. This concentration carries strategic implications for procurement stability, technology licensing dynamics, and the pace at which new entrants or regional specialty producers can capture share in high-specification segments. Understanding these competitive fault lines is essential for organizations evaluating supplier diversification, partnership strategies, and long-term technology roadmaps.
Market Dynamics: Pricing, Regulations, and the Cost Equation
The operating environment for metallocene catalysts is shaped by a continuously evolving set of cost, regulatory, and downstream specification pressures. Raw material economics play a central role in determining margin resilience and adoption velocity. Recent market indicators from March 2026 highlight that mLLDPE pricing in Northeast Asia moved to approximately 1.19 USD per kilogram, reflecting a modest downward adjustment driven by declining upstream ethylene and metallocene catalyst feedstock costs at key producing facilities. While lower feedstock expenses can ease input pressure, the broader cost equation remains nuanced, particularly when evaluating the relative premium of metallocene systems compared to conventional catalyst alternatives.
Industry data indicates that metallocene catalysts generally carry a cost premium of approximately 30-40% relative to traditional Ziegler-Natta systems used in LLDPE production. This differential has historically positioned metallocene chemistry as a selective rather than universal solution, reserved for applications where precision polymer architecture delivers measurable performance advantages in film clarity, mechanical properties, downgauging potential, or processing efficiency. As downstream converters increasingly pursue thinner films, mono-material packaging, and enhanced recyclability, the economic justification for premium catalyst platforms is undergoing reconsideration, with performance-per-unit-cost becoming a central evaluation criterion.
Regulatory developments are compounding this shift. The European Union's Packaging and Packaging Waste Regulation requires recyclable and mono-material packaging solutions by 2030, creating a compliance-driven demand tailwind for metallocene catalyst-derived polyolefins that can meet stringent structural and recyclability specifications. Concurrently, stricter EU environmental regulations on single-use plastics are compelling converters to seek recyclable monomaterial packaging architectures, further reinforcing the role of precision catalyst chemistry in enabling specification-compliant output. These regulatory currents are not confined to Europe; they are influencing global packaging design standards and accelerating technology alignment across export-oriented manufacturing hubs.
Strategic Imperatives for 2026 Enterprise Planning
As organizations prepare their 2026 planning cycles, the metallocene catalyst market presents a distinct set of strategic considerations. First, technology selection decisions must be evaluated against long-term regulatory trajectories rather than short-term cost differentials alone. Catalyst platforms that enable recyclable mono-material structures and high-performance film specifications are likely to secure preferential positioning as compliance requirements tighten.
Second, regional capacity deployment and supplier diversification strategies should be informed by a clear understanding of where demand growth is concentrating and which catalyst architectures are gaining commercial validation in those environments. The interaction between regional pricing dynamics, feedstock cost movements, and downstream grade requirements will increasingly determine which supply relationships deliver sustainable margin resilience.
Third, competitive intelligence must extend beyond product specifications to encompass process integration capabilities, custom formulation responsiveness, and partnership ecosystems that shape commercial deployment velocity. Companies that can align catalyst performance with client-specific processing conditions and downstream end-use requirements will be best positioned to capture premium segments and defend against substitution risk.
Finally, scenario planning should incorporate both upside demand drivers, such as sustainability mandates and high-performance packaging growth, and downside pressures, including feedstock volatility, cost premium sensitivity, and competitive intensity among concentrated market leaders. The organizations that thrive in this environment will be those that treat catalyst strategy not as a procurement footnote but as a core component of polymer production economics and product differentiation planning.
Conclusion: Navigating the Forecast Window with Confidence
The metallocene catalyst market is entering a phase of accelerated structural evolution. Growth trajectory, competitive positioning, regulatory pressure, and raw material dynamics are converging to create a landscape where strategic foresight directly translates into commercial advantage. Our comprehensive market research study provides the analytical depth, segmentation clarity, and competitive context necessary to navigate this environment with confidence. For executive teams seeking to validate investment assumptions, optimize supplier strategy, and align technology adoption with downstream market demand, the full report delivers the granular intelligence required to convert insight into action.
To access detailed segmentation breakdowns, regional development patterns, application-specific consumption profiles, and complete competitive benchmarking data, we invite you to explore the complete publication through our official research portal. The full intelligence suite is designed to support executive planning, procurement strategy, and long-range technology roadmap development across the 2026-2032 forecast horizon.
For detailed analysis of this topic, please visit the official page: Metallocene Catalyst Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Laminator Market Hits $489M in 2025, Poised for 7.25% CAGR Through 2032
By pmarketresearch, 2026-09-15
Strategic Intelligence for the Laminating Machinery Sector: Navigating Growth, Segmentation, and Competitive Dynamics in 2026
The global laminator market stands at a critical inflection point. As enterprises across packaging, printing, and commercial production recalibrate their capital allocation strategies, the ability to distinguish between transient demand spikes and structural growth drivers has never been more consequential. This analysis, drawn from our latest Laminator Market research, is designed to equip strategic decision-makers with the contextual clarity required to navigate a landscape defined by technological differentiation, regional reconfiguration, and compounding macroeconomic pressures. The following overview outlines the market architecture, competitive contours, and operational imperatives that will shape procurement, investment, and portfolio decisions through 2032.
Laminating Machine Market
Market Trajectory: Historical Momentum and the 2026–2032 Forecast Horizon
Tracing the revenue curve from 2020 through the base year of 2025 reveals a market that has consistently outpaced broader industrial equipment benchmarks. Total market value expanded from 347.0 million USD in 2020 to 489.0 million USD by 2025, reflecting a compound annual growth trajectory that underscores sustained commercial adoption rather than cyclical rebound. The momentum extends well into the forecast period: projected revenue crosses the 535.82 million USD threshold in 2026 and continues ascending toward 798.0 million USD by 2032, supported by a forecast-period CAGR of 7.25 percent.
For enterprise strategists, this trajectory carries several implications. First, the growth is broad-based enough to suggest that laminators are transitioning from niche auxiliary equipment to integrated production infrastructure in multiple downstream verticals. Second, the acceleration pattern indicates that early-mover commitments to advanced lamination capacity are likely to capture disproportionate share in packaging and commercial printing workflows where throughput and material protection requirements are intensifying. Third, the forecast window provides a sufficiently long runway for organizations to align equipment roadmaps with multi-year capacity expansion plans rather than reacting to short-term supply constraints.
Importantly, the macro trajectory does not distribute evenly across commercial realities. The market's composition reflects distinct operational profiles, with automatic and semi-automatic configurations dominating revenue pools, manual units sustaining steady demand in institutional and light-commercial settings, and industrial-grade systems anchoring high-specification packaging and specialty coating applications. This structural split dictates that procurement strategies cannot rely on homogenized specifications; instead, they must align machine capability with workflow intensity, material chemistry, and downstream compliance requirements.
Segmentation Architecture: Decoding Demand Drivers Without Overgeneralization
Effective market positioning requires a granular understanding of how value migrates across machine categories, application verticals, and geographic corridors. Our research decomposes these dimensions to reveal where procurement budgets are concentrating and where addressable gaps remain underserved.
Laminator Market
Within the equipment taxonomy, thermal pouch and roll-based configurations continue to anchor office, educational, and light commercial print environments, while reel-to-reel and reel-to-sheet platforms drive commercial graphics enhancement, thin and thick film encapsulation, and protective coating workflows. Industrial and solventless lamination systems occupy a specialized but high-value tier, serving flexible packaging, food and pharmaceutical-grade applications, and integrated print-laminate-slitting lines. The divergence in operational economics across these categories means that total cost of ownership calculations must incorporate film chemistry compatibility, curing technology requirements, maintenance cycles, and throughput variability rather than relying solely on acquisition price.
On the application side, packaging remains the dominant revenue anchor, reflecting the sector's relentless demand for moisture barrier performance, shelf-life extension, substrate durability, and aesthetic finishing. Printing and commercial graphics applications constitute a secondary but strategically important pool, where lamination serves both protective and decorative functions, including foil integration, embossing compatibility, and UV-cured surface enhancement. Office and adjacent institutional use cases maintain a stable baseline, driven by document preservation, signage production, and small-batch commercial output. Each application vertical carries distinct material sensitivity profiles; for example, packaging workflows are particularly exposed to raw material cost volatility for laminating films such as polypropylene and polyester, while adhesive pricing tied to oil-based inputs can suppress margin flexibility in flexible packaging lines.
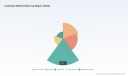
Geographically, the market exhibits a multi-polar distribution with pronounced regional specialization. Asia Pacific commands the largest revenue share, reflecting concentrated packaging production capacity, expanding commercial printing ecosystems, and rapid adoption of automated lamination lines. North America and Europe sustain robust demand grounded in mature print service infrastructure, regulatory-driven material compliance, and ongoing upgrades to industrial coating and laminating platforms. Latin America and the Middle East and Africa represent growth corridors where infrastructure maturation, import substitution trends, and localized production incentives are gradually reshaping procurement patterns. Organizations evaluating market entry, capacity relocation, or partner selection must therefore treat regional analysis as a dynamic variable rather than a static ranking.
Competitive Landscape: Strategic Postures of Leading Players
The laminator market is characterized by moderate concentration, with the top three players accounting for approximately 26.5 percent of revenue and the top five collectively capturing around 30.1 percent. This structure signals a market where incumbents hold meaningful positional advantage but where specialization, regional reach, and technology differentiation remain viable pathways for competitive traction.
Several companies illustrate the strategic diversity shaping the sector. GBC maintains a strong presence in office and print shop thermal pouch and roll laminators, with product lines such as the LamPrix 100 and Catena series tailored to schools, offices, and small commercial production environments. Autobond focuses on print enhancement lamination machines, thin and thick film encapsulators, and reel-to-reel and reel-to-sheet systems designed for commercial printing and graphics protection. Cellcoat Systems operates at the intersection of thermal lamination and coating machinery, emphasizing roll-to-roll and bespoke applications across packaging and graphic arts.
On the industrial and packaging side, Uteco Converting S.p.a. deploys solventless and multi-technology coaters and laminators, including PrismaLG, DuaLam, and Mistral platforms, targeting flexible packaging and food and pharmaceutical applications. Lamina System AB addresses sheet-to-sheet laminating, mounting, and gluing workflows for printing, corrugated, and folding carton industries. In China, Sunkia Machinery advances automatic thermal film and roll-to-roll lamination machines with patented multi-function systems and ISO/CE certification, positioning itself for international deployment. Wenzhou Guowei Printing Machinery integrates gravure printing and laminating machines with slitting for complete packaging lines, while Wenzhou Feihua Printing Machinery offers automatic and semi-auto laminating machines with UV coating options and embossing capabilities for packaging and printing. Chongqing Sinstar Packaging Machinery concentrates on solventless lamination machines for flexible packaging, including upgraded SUPLOCK solutions.
Recent corporate activity reinforces the market's innovation cadence. In October 2025, 3M Company recalled its Scotch Thermal Laminator model TL909-50 due to overheating hazards affecting approximately 13,440 units, prompting refunds and broader safety compliance reviews across thermal laminator categories. The same period saw Advanced Greig Laminators, Inc. introduce the AGL 80 industrial laminating machine for foam and gasket applications, incorporating UV and UV LED curing technologies. Momentum carried into 2026, with Skandacor showcasing the LAMpro Cheetah S15M versatile laminator capable of both lamination and digital foil processing at C!Print 2026, and Jialite demonstrating the NFY-S540 Automatic Film Laminating Machine live at DPRINT SOUTH 2026. These developments highlight a sector where safety compliance, curing technology integration, multi-function versatility, and live demonstration-driven commercialization are increasingly intertwined.
Market Dynamics: Restraints, Catalysts, and Procurement-Relevant Risks
Strategic planning in this market cannot isolate equipment specifications from the environmental and operational forces that shape adoption. Raw material volatility remains a recurring constraint, particularly for laminating films including polypropylene and polyester, where price instability limits development potential in packaging applications and compresses margin flexibility. Adhesive pricing tied to oil-based inputs introduces additional friction, especially for flexible packaging workflows where solventless and lamination adhesive economics directly influence line profitability. High manufacturing costs and volatile raw material conditions are frequently cited as key restraints limiting the broader expansion of thermal lamination film adoption, reinforcing the case for long-term supply agreements, material substitution evaluation, and lifecycle cost modeling.
Regulatory and safety dynamics add another layer of complexity. The October 2025 CPSC recall of 3M Scotch thermal laminators due to overheating and burn hazards triggered safety compliance reviews and reminded procurement teams that thermal-based equipment must be evaluated not only for throughput and finish quality but also for thermal management reliability, certification status, and post-market support responsiveness. At the same time, companies such as Sunkia Machinery have emphasized ISO and CE certifications for international deployment, signaling that compliance readiness is becoming a competitive differentiator in cross-border sales and integrator partnerships.
Infrastructure and cost considerations further shape adoption curves. High manufacturing costs and material volatility can slow the rollout of advanced thermal lamination film solutions, particularly in price-sensitive segments where buyers prioritize immediate cost control over long-term performance gains. Conversely, regions and verticals with stronger capital availability, tighter quality requirements, and integrated production line strategies are better positioned to absorb upfront investment in exchange for throughput stability, material protection, and reduced rework.
Strategic Imperatives for 2026 Decision-Making
As organizations map their laminator procurement and capacity strategies for 2026 and beyond, several decision frameworks emerge from the market structure:
- Align machine selection with workflow intensity rather than uniform specifications. Automatic, manual, and industrial configurations serve distinct throughput, material, and compliance requirements, and procurement misalignment can generate hidden operating costs.
- Integrate raw material exposure into total cost of ownership models. Film chemistry, adhesive pricing, and curing technology requirements influence both acquisition decisions and multi-year operating economics, particularly in packaging and flexible packaging applications.
- Treat safety compliance and certification status as procurement gate criteria. Thermal management reliability, recall risk awareness, and international certification readiness should inform vendor evaluation alongside technical performance.
- Assess regional demand architecture when planning capacity, partnerships, or market entry. Revenue distribution across North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa reflects different production ecosystems, regulatory environments, and adoption maturities.
- Monitor competitive activity through a technology-integration lens. UV and UV LED curing, multi-function lamination and foil processing, solventless systems, and integrated print-laminate-slitting lines are reshaping value propositions across commercial printing and packaging.
What the Full Study Delivers
This market research extends well beyond headline revenue figures and broad segmentation labels. It provides an operational intelligence framework designed for procurement leads, capital planners, competitive intelligence teams, and market entry strategists. The full study maps machine-type revenue distribution, application-level demand concentration, and regional revenue splits with the precision required to support scenario planning and vendor benchmarking. It profiles core companies with operational context, recent product and compliance developments, and strategic posture analysis. It further examines market concentration dynamics, raw material and regulatory pressures, and the interplay between manufacturing costs and adoption feasibility across thermal, solventless, and industrial lamination categories.
For decision-makers seeking to convert market momentum into disciplined capital allocation, the complete report delivers the segmented intelligence, competitive mapping, and dynamic risk assessment necessary to act with confidence. To access the full dataset, company profiles, segmentation breakdowns, and forecast architecture, visit the Laminator Market research page and secure the complete intelligence package.
For detailed analysis of this topic, please visit the official page: Laminator Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Print Quality Inspection Market to Reach $300M by 2032, Growing at 5.8% CAGR
By pmarketresearch, 2026-09-15
Navigating the Print Quality Inspection System Market: Strategic Intelligence for 2026 Decision-Makers
The global manufacturing landscape is undergoing a profound transformation. As production lines accelerate and regulatory scrutiny intensifies, the Print Quality Inspection System market has emerged as a critical enabler of operational excellence. For executive teams, capital allocators, and strategic planners, understanding the trajectory of this market is no longer optional. It is a prerequisite for competitive positioning, supply chain resilience, and long-term value creation.
PW Consulting has published a comprehensive market research report that maps the Print Quality Inspection System market from historical baselines through 2032. This article serves as an executive preview of the research. It outlines the macro architecture of the market, highlights the competitive forces and technological inflection points shaping the sector, and explains why the full report delivers the granular intelligence required for actionable planning in 2026 and beyond.
A Decade of Resilient Expansion: Mapping the Macro Trajectory
Over the past half-decade, the market has demonstrated steady growth, reflecting the sector's embedded role in quality assurance across printing, packaging, and industrial inspection workflows. Historical data from 2020 through 2025 shows a consistent upward trajectory, with total market revenue progressing from approximately 148.5 million USD to 201.5 million USD by the base year. This sequence underscores a market that has weathered supply chain disruptions, component constraints, and shifting production priorities without losing structural momentum.
The forward outlook reinforces this trajectory. Forecasts for the 2026 to 2032 period project continued expansion, with total market revenue climbing from an estimated 216.69 million USD in 2026 to approximately 300.0 million USD by the end of the forecast horizon. This progression translates to a compound annual growth rate of 5.8 percent, a figure that positions the Print Quality Inspection System market as a steady, mid-single-digit growth segment within the broader industrial automation and quality control ecosystem.
For strategy leaders, these figures carry implications beyond headline sizing. They signal durable demand for inspection hardware, software, and integrated solutions across print and packaging value chains. The growth profile also suggests that market share dynamics will increasingly favor firms that can combine precision, speed, and software-driven flexibility rather than those competing solely on hardware specifications. As the market advances, the margin between incremental adoption and strategic deployment will widen, and the firms that act early will capture the benefits of scale, learning, and ecosystem positioning.
The full report provides the detailed historical-to-forecast bridge, sensitivity considerations, and scenario framing that enable finance and strategy teams to build defensible internal models. The macro numbers presented here establish the scale and pace of the opportunity; the report supplies the structural context needed to translate those numbers into decisions.
What the Report Delivers: Operational Content for Real-World Planning
Market data alone does not equip leadership to act. The strategic value of this research lies in its operational depth. The report is structured to support cross-functional usage, from procurement and engineering to product strategy and corporate development. It goes beyond aggregate sizing to examine how adoption patterns differ across system architectures, deployment contexts, and end-use requirements.
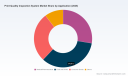
The segmentation analysis breaks the market into actionable dimensions. By system type, the research distinguishes between in-line and off-line inspection approaches, capturing the operational tradeoffs between continuous production monitoring and batch-oriented verification. By application, the report evaluates how demand varies across medical and pharmaceutical workflows, food and beverage packaging, consumer goods, and other industrial use cases. By geography, it maps regional dynamics to help leaders assess market maturity, competitive pressure, and growth potential in different operating environments.
Importantly, the report is designed to preserve analytical integrity while protecting commercially sensitive detail. It presents the framework and directional insights that executives need to prioritize internal work, while reserving the full breakdown of regional and application-level proportions, specific revenue figures, and granular share data for the authenticated report. This approach ensures that strategic conversations can begin with credible context, while the precise numbers remain tied to the official intelligence asset.
In addition to segmentation, the research integrates market structure indicators. Concentration metrics such as the combined share of leading competitors provide a lens on fragmentation, competitive intensity, and the room available for new entrants or consolidation plays. The report also addresses the practical constraints that influence deployment velocity, including the capital intensity of high-speed line scan imaging modules, integration requirements, and infrastructure readiness. These factors matter because adoption is rarely a pure function of demand; it is shaped by investment cycles, change management, and manufacturing economics.
The end result is a research deliverable that can support a range of planning activities: demand forecasting, capacity and investment timing, vendor evaluation, partnership scouting, and market entry analysis. It provides the scaffolding for informed decisions without reducing a multidimensional market to a single headline figure.
Competitive Landscape: Who Shapes the Market Today
No assessment of this market is complete without a clear view of the competitive field. The Print Quality Inspection System sector is populated by a mix of specialized inspection providers, vision technology leaders, and broader industrial automation companies. Each brings a distinct value proposition, from AI-enabled defect detection to prepress verification, web monitoring, tension control, and integrated quality management software.
Several firms illustrate the range of strategic positions in the market. EyeC GmbH, based in Hamburg, has built recognition around inspection and prepress verification solutions, including series architectures designed for defect detection and artwork verification. Its recent emphasis on cloud-based prepress inspection software reflects a wider industry movement toward hardware-independent inspection workflows and software-led differentiation. AVT Inc., headquartered in Israel, serves the label and flexible packaging industries with inspection and color measurement solutions focused on real-time defect detection and waste reduction, and has recently undergone a corporate transformation that refocused the business on dedicated inspection solutions.
LUSTER, operating out of China, has gained attention for AI-driven vision inspection systems that target high-speed printing and packaging workflows. Its product activity underscores the growing role of artificial intelligence in automating visual quality control. Procemex, based in Finland, offers web monitoring and inspection systems for pulp, paper, and printing applications, with defect detection solutions that extend beyond print alone into wider web processing. Erhardt+Leimer, also based in Germany, integrates web inspection and tension control with print quality solutions, a combination that resonates in paper, printing, and packaging environments where process stability and quality assurance are tightly linked.
Print Quality Inspection System Market
Other significant participants reinforce the breadth of the competitive set. Nireco Corporation from Japan supplies inspection systems for web and surface applications. Lake Image Systems in the United Kingdom provides comprehensive inspection solutions that span web and sheet monitoring, with product lines tailored to printing and packaging. Baldwin Vision Systems in the United States delivers defect detection systems for web and sheet-fed printing. Futec, also from Japan, focuses on inspection and control systems for high-speed printing processes. Esko, based in Belgium, contributes prepress and print quality inspection solutions, particularly around artwork and packaging verification. Omron, through its Microscan business in the United States, offers machine vision systems for automated inspection and verification in packaging and labeling. Cognex Corporation, likewise based in the United States, develops AI-powered vision systems for automated inspection and defect detection.
The competitive field is not static. Recent developments show a sector in motion. In March 2025, AVT Inc. announced its acquisition by Porat Itay Holdings and its transformation into an independent company, a move intended to sharpen its focus on print quality inspection solutions. In June 2025, LUSTER introduced the VisionPrint 8 AI Inspection System at CHINA PRINT 2025, highlighting next-generation AI for printing visual quality control. EyeC GmbH has continued to expand its software footprint, including the introduction of Proofiler Graphic Connect, a cloud-based prepress inspection tool designed to operate independently of hardware and systems. In May 2026, both Procemex and EyeC showcased inspection and monitoring solutions at major industry events, signaling continued emphasis on live demonstration, customer engagement, and ecosystem visibility.
This competitive mosaic matters because procurement and strategy teams rarely select a supplier in isolation. Decisions are shaped by integration requirements, regional service capabilities, software roadmaps, and compatibility with existing line architectures. The full report provides a structured competitive profile framework that supports vendor benchmarking and partnership evaluation, while the overview here establishes the breadth and dynamism of the market's key participants.
Forces Reshaping Demand: Technology, Regulation, and Manufacturing Economics
Market growth is not merely a function of capacity expansion. It is being reshaped by intersecting forces that influence both the pace and the nature of adoption. At the technology level, artificial intelligence is becoming a defining element of inspection systems. AI-powered defect detection, automated visual quality control, and software-driven verification are reducing reliance on manual inspection and enabling higher throughput with greater consistency. As these capabilities mature, they are changing the value proposition of inspection systems from reactive defect capture to proactive process assurance.
Regulatory and standards-driven factors are equally important. Quality management expectations continue to evolve across manufacturing sectors, and print quality inspection systems increasingly sit within broader compliance frameworks. International standards such as ISO 9001:2015 serve as a foundational reference for quality management across global manufacturing, while sector-specific requirements add further discipline. In regulated pharmaceutical and medical applications, compliance expectations tied to FDA and EMA standards create additional demands on packaging and print verification workflows. In February 2026, the Quality Management System Regulation took effect, amending device CGMP requirements and incorporating ISO 13485:2016 into quality management expectations. These dynamics reinforce the strategic relevance of inspection systems as instruments of documentation, traceability, and consistency.
X-ray Inspection Systems Market
Manufacturing economics also influence adoption patterns. Rising labor shortages in manufacturing environments are a material consideration, as they heighten the appeal of automated inspection and reduce the feasibility of manual quality checks at scale. At the same time, high capital equipment costs and the infrastructure investment required for high-speed line scan imaging modules can act as deployment barriers. This tension between labor-related pressure and capital-related constraints creates a nuanced demand environment in which adoption depends not only on technical merit but also on financing strategies, production planning, and total cost of ownership assessments.
Together, these forces create a market where intelligence must be both technical and commercial. Leaders need to understand how regulation, labor dynamics, and technology roadmaps will interact with segment-specific requirements and regional operating conditions. The report is built to address that complexity directly. It connects market structure to the operational realities that determine whether an inspection investment succeeds in a given environment.
Why This Report Matters for 2026 Strategy
For organizations planning in 2026, the Print Quality Inspection System market represents more than a niche equipment segment. It sits at the intersection of quality, automation, compliance, and production economics. That positioning makes it relevant to a wide range of decision-makers, including operations leaders evaluating line upgrades, procurement teams comparing inspection vendors, product strategists assessing adjacent opportunities, and investors modeling exposure to industrial automation and packaging technologies.
The strategic value of this research lies in its ability to convert broad market movement into practical decision support. The forecasting framework provides a defensible path from historical performance to forward expectations, enabling internal models that are grounded in documented market data rather than anecdotal assumptions. The segmentation architecture helps teams identify where growth is concentrated, where system preferences differ, and where application-specific requirements create differentiation opportunities. The competitive analysis supports vendor evaluation, partnership strategy, and positioning decisions. The integration of regulatory and operational context ensures that market size discussions are linked to the realities that shape deployment timing and success.
At the same time, the report respects the difference between directional intelligence and proprietary detail. It establishes the analytical frame, the competitive logic, and the operational levers that matter, while holding back the full regional and application-level breakdowns, precise revenue splits, and granular share figures for the authenticated version. This design is intentional. It allows leaders to assess the relevance of the research quickly and to justify deeper engagement with the complete dataset where decisions demand precision.
Moving from Context to Precision
Market research is most valuable when it shortens the distance between uncertainty and action. The Print Quality Inspection System market is expanding with steady discipline, shaped by AI-enabled inspection, evolving quality management expectations, manufacturing labor dynamics, and the capital considerations that accompany high-speed imaging infrastructure. The competitive field is diverse and active, and recent corporate and product developments indicate that software, cloud integration, and AI are becoming central to differentiation.
This overview provides the executive context needed to understand the market's scale, structure, and strategic significance. It frames the opportunity and explains how the full report extends that framing into actionable detail. For teams that need to make investment, procurement, product, or partnership decisions with confidence, the next step is to access the complete dataset, segmentation depth, competitor profiles, and scenario analysis contained in the full PW Consulting research. The macro story is clear; the detailed intelligence required to act on it awaits in the report.
For detailed analysis of this topic, please visit the official page: Print Quality Inspection System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
The Prebiotic Pivot: Why the Fructooligosaccharide Market Demands Strategic Attention in 2026
The global food and nutrition industry is currently navigating a structural transformation where functional benefit is no longer a differentiator but a baseline expectation. Within this landscape, Fructooligosaccharide (FOS) has emerged as a critical ingredient bridging the gap between sugar reduction mandates, gut health trends, and regulatory compliance in sensitive categories like infant nutrition. As we move into 2026, the velocity of this market expansion is accelerating, driven by converging consumer demands and sophisticated supply chain adaptations.
This article serves as a strategic preview to the latest comprehensive market research published by PW Consulting. Our analysis is designed to equip executives, R&D directors, and investors with the macro-level intelligence necessary to navigate the 2026-2032 forecast period. While specific granular data points require the full report, the macro trajectory and competitive dynamics outlined below underscore the urgent need for data-backed decision-making in this sector.
A Trajectory of Resilient Growth: The 2026 Outlook
The financial momentum behind Fructooligosaccharides is not merely cyclical; it is structural. Based on our analysis of historical performance from 2020 through 2025, the market has demonstrated remarkable resilience even amidst raw material volatility. The market size, valued in millions of USD, has climbed steadily, reflecting a compound annual growth rate (CAGR) of 8.25% projected through 2032.
For strategic planners, this growth rate signals more than just revenue expansion. It indicates a deepening penetration of FOS across diverse value chains. The baseline year of 2025 establishes a new equilibrium, setting the stage for a forecast period where the market is expected to reach significant valuation milestones by the early 2030s. This growth is underpinned by a shift from niche health stores to mainstream food and beverage formulations, driven by the dual pressures of clean label initiatives and functional health claims.
However, interpreting these top-line figures requires nuance. The aggregate market size masks varying growth velocities across different forms and applications. Understanding which segments are driving the bulk of this value expansion versus which are stabilizing is crucial for capital allocation. Our full report dissects these streams without revealing the specific percentages in this summary, ensuring that stakeholders understand the magnitude of opportunity while reserving the precise market share data for the confidential intelligence package.
Competitive Landscape: Consolidation and Innovation
The Fructooligosaccharide market is characterized by a moderately concentrated competitive environment. With the top three players holding a combined market share that reflects significant influence and the top five controlling a majority of the landscape, barriers to entry remain non-trivial. This concentration suggests that supply security and regulatory approvals are key leverage points for the incumbents.
Several key enterprises define the current operational standards and innovation pace within this sector. Beneo GmbH, headquartered in Germany, continues to be a pivotal player, particularly with its Beneo-scL85 short-chain FOS which is integral to sugar reduction strategies and infant nutrition. Their European production facilities provide a logistical advantage for serving the high-regulation markets of the West.
Simultaneously, Meiji Holdings Co., Ltd. from Japan represents the strength of the Asian market and branded ingredient solutions. Their Actilight and Meioligo brands have set benchmarks in functional foods and supplements. Recently, Meiji demonstrated the application potential of FOS by launching a functional chocolate line in July 2024, utilizing FOS to achieve significant sugar reduction while maintaining gut health benefits. This move highlights the trend of FOS migrating from health-specific products into indulgence categories.
On the global supply side, giants like Cargill and Ingredion maintain broad portfolios that ensure availability across infant formula, dietary supplements, and functional beverages. Ingredion's focus on GRAS-supported formulations and multiple product grades allows for flexibility in customer formulation. Tate & Lyle PLC has also been active, particularly regarding regulatory clearance. In March 2025, Tate & Lyle filed a GRAS notice for short-chain FOS for use in infant products and conventional food and beverage categories, with safety data reviewed up to February 2025. This regulatory step is critical as it expands the viable application space for their enzymatic short-chain FOS (scFOS).
Other notable contributors include Galam Group, which has highlighted clinical research on their GOFOS™ FOS stimulating GLP-1 hormone levels for metabolic health, and COSUCRA Groupe Warcoing SA, which continues to supply chicory-derived FOS. Roquette Frères and Quantum Hi-Tech (China) Biological Co., Ltd. round out the landscape, with the latter focusing heavily on Asian market needs and prebiotic oligosaccharides for food, feed, and supplements.
Strategic Implications of Recent Developments
The recent activities of these companies point to three major strategic themes. First, regulatory fortification is accelerating; the GRAS notifications and EU approvals since 1999 for baby formula create a safer environment for large-scale adoption. Second, product innovation is shifting towards metabolic health, evidenced by the clinical highlights regarding GLP-1 stimulation. Third, capacity investments are being made to handle sugar reduction demands, as seen in Beneo's 2024 production capacity expansions.
Market Dynamics: Regulatory and Cost Headwinds
While the growth narrative is positive, the operational environment is fraught with complexities that require sophisticated risk management. Regulatory compliance remains the primary gatekeeper for market access, particularly in sensitive categories. For instance, FOS maintains GRAS status for use in infant formula at specific limits—up to 400 mg/100 ml in starter formula and 500 mg/100 ml in follow-on formula as consumed. These limits, documented in FDA GRAS Notice GRN 537 from February 2015, dictate formulation constraints that companies must adhere to strictly.
Fructooligosaccharide (FOS) Market
In the European Union, FOS has been approved for addition in restricted amounts to baby formula and follow-on formula sold since 1999, establishing a long-standing precedent there. Meanwhile, in Canada, FOS is permitted as a medicinal and non-medicinal ingredient in Natural Health Products. These varying regional requirements create a fragmented compliance landscape that increases the cost of market entry for new players and rewards incumbents with established regulatory dossiers.
Supply chain stability presents another layer of challenge. High production costs and seasonal fluctuations in chicory root supply continue to challenge the scaling of inulin-derived FOS. This volatility impacts pricing strategies and margin protection across the value chain. Companies that rely on a single source of raw material face heightened risk compared to those with diversified sourcing strategies or enzymatic production capabilities that bypass some agricultural dependencies.
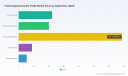
Furthermore, the distinction between powder and liquid forms adds another dimension to logistics and formulation. While specific market split data is reserved for the full report, it is evident that the choice of form influences distribution channels and end-user acceptance, particularly in liquid versus solid food applications.
Strategic Value of the 2026-2032 Forecast Report
For decision-makers, the value of this comprehensive study lies in its ability to translate high-level trends into actionable intelligence. The market is not growing uniformly; certain applications are leveraging the prebiotic boom more aggressively than others. The food and beverages category, alongside infant formula and dietary supplements, represents a substantial portion of the demand drivers, but the dynamics within each segment differ radically in terms of margin structure and regulatory hurdle rates.
Our report provides a deep dive into these segmentations. It analyzes the form preferences that are gaining traction in specific regions without disclosing the exact regional revenue splits here. This allows you to understand where the liquidity is flowing—whether towards powder forms favored in supplements or liquid forms suited for beverages—without relying on assumptions.
The competitive analysis section goes beyond listing major players. It evaluates their strategic positioning, capacity expansions, and recent moves such as the product launches by Meiji in 2024 and capacity strengthening by Beneo. Understanding who is filing for new GRAS notifications, like Tate & Lyle in March 2025, versus who is focusing on clinical research like Galam Group, allows companies to anticipate competitor moves in their own product roadmaps.
Additionally, the report addresses the production cost dynamics head-on. By contextualizing the chicory root supply fluctuations against the backdrop of growing demand, we provide a framework for assessing supplier viability and long-term contract negotiations. The market concentration data reveals how much power suppliers hold versus buyers, informing procurement strategies for the next five to seven years.
Conclusion: Navigating the Next Horizon
The Fructooligosaccharide market in 2026 is at an inflection point. The convergence of regulatory clarity, consumer awareness regarding gut health, and the industry-wide push for sugar reduction creates a fertile ground for expansion. However, the path to capturing value in this 8.25% CAGR environment requires more than just general optimism. It demands granular insight into segmentation strengths, regulatory boundaries, and competitive moats.
The data presented in this overview highlights the scale and direction of the opportunity. From the historical recovery post-2022 to the robust forecasts leading to 2032, the trajectory is clear. Yet, the specific regional allocations, the precise value of each application segment, and the detailed comparative financial strengths of the key players remain part of the confidential depth of our full market research publication.
For organizations looking to secure their supply chains, formulate new products, or identify M&A opportunities within the prebiotic sector, relying on aggregated data is insufficient. The nuances of GRAS approvals, the impact of chicory root seasonality on specific regions, and the shifting preferences between short-chain and longer-chain variations require the detailed scrutiny provided in the PW Consulting Fructooligosaccharide Market Report. We invite stakeholders to engage with the full dataset to transform these industry insights into concrete strategic advantage.
Worldwide Short Chain Fructooligosaccharides Market
For detailed analysis of this topic, please visit the official page: Fructooligosaccharide (FOS) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Roadmarking Paints Market Hits $7.18B in 2025, 5.8% CAGR to $10.6B by 2032
By pmarketresearch, 2026-09-15
Navigating the Next Wave of Growth in the Roadmarking Paints Market
As urban infrastructure expands and regulatory frameworks deepen their focus on safety and sustainability, the roadmarking paints sector stands at a critical inflection point. For executives, procurement leaders, and strategy teams operating across construction, coatings, and public works, understanding the trajectory of this market is no longer optional. It is a prerequisite for capital allocation, product portfolio planning, and long-term competitive positioning. Our latest research study offers a comprehensive, data-driven view of the industry, mapping historical performance, projecting forward momentum, and unpacking the operational realities that will shape corporate decisions through the end of the decade.
This analysis is designed as a strategic preview of what the full report delivers. Rather than providing a superficial overview, it walks through the macro-scale trajectory, the structural forces altering supply and demand, the competitive dynamics among established players, and the practical frameworks our methodology uses to translate market signals into executable intelligence. The goal is to demonstrate the depth of insight available and to show precisely how decision-makers can leverage this research to reduce uncertainty, optimize investment timing, and align product strategies with emerging market realities.
Traffic Marking Paints Market
Macro Trajectory: From Historical Correction to Sustained Expansion
The roadmarking paints market has demonstrated consistent growth over the past half-decade, recovering from early-cycle fluctuations and building momentum as governments and private developers prioritize road safety, lane visibility, and infrastructure modernization. Historical data from 2020 through 2025 reveals a steady upward path, with the total market expanding from approximately 5.52 billion USD to an estimated 7.18 billion USD. This progression reflects not only renewed public spending on transportation networks but also a gradual shift toward higher-performance marking solutions that offer improved durability, retroreflectivity, and environmental compliance.
Looking ahead, the forecast period from 2026 through 2032 projects continued expansion, with the market expected to surpass the 10 billion USD threshold and reach a valuation near 10.6 billion USD by the close of the forecast window. The implied compound annual growth rate across this horizon stands at 5.8 percent, a pace that signals durable demand rather than a temporary cyclical spike. This trajectory is underpinned by widening application footprints, ongoing replacements of worn or faded markings, and the gradual adoption of advanced formulation technologies that extend service life and reduce lifecycle maintenance costs.
What makes this growth profile strategically significant is its consistency across varying economic conditions. While raw material pricing fluctuations and regulatory adjustments introduce short-term volatility, the underlying demand drivers remain anchored in infrastructure renewal cycles, urbanization trends, and the need for standardized, high-visibility road markings that meet increasingly rigorous safety specifications. Organizations that understand where growth concentrates, which product categories are gaining share, and how regional procurement rhythms differ will be better positioned to time capacity expansions, pricing strategies, and distribution partnerships.
Regulatory Pressures, Raw Material Volatility, and the Shifting Value Chain
No strategic assessment of this market is complete without addressing the operational pressures that are reshaping cost structures and influencing purchasing behavior. One of the most persistent challenges in recent quarters has been raw material cost volatility. Resin suppliers, thermoplastic compound producers, and specialty glass bead manufacturers have experienced uneven pricing dynamics, creating margin pressure for formulators and coating manufacturers. This instability is especially pronounced for soda lime glass and specialty chemical coatings, where supply chain sensitivity and regional sourcing constraints can quickly alter input economics. For budget-constrained infrastructure projects, these cost pressures can slow adoption of premium marking systems or push buyers toward lower-cost alternatives that may compromise durability or reflectivity.
At the same time, regulatory standards are tightening across multiple jurisdictions. Environmental regulations concerning VOC emissions and broader ecological impact continue to influence formulation choices, accelerating the transition away from solvent-heavy products in favor of waterborne and low-emission alternatives. Compliance requirements are not merely a constraint; they are increasingly a competitive differentiator. Manufacturers that can deliver high-performance markings while meeting emission thresholds and sustainability expectations gain preferential access to public tenders, municipal contracts, and specification-driven projects.
Recent specification updates also illustrate how technical standards are evolving. Revisions to ready-mixed paint specifications for road marking, such as the updated IS 164 framework, introduce new performance and quality expectations that affect both product development and procurement criteria. For suppliers, alignment with updated standards is essential to maintain eligibility in key bidding environments. For buyers, these changes create a clearer benchmark for evaluating consistency, adhesion, weather resistance, and retroreflective performance. The interplay between raw material dynamics and regulatory evolution means that market participants must monitor both cost-side and compliance-side variables simultaneously, a complexity that our study maps in detail across multiple operational dimensions.
What the Report Covers: A Practical Blueprint for Decision-Makers
The full research study is built to move beyond headline figures and equip teams with actionable frameworks. It begins with a rigorous sizing and forecasting model that traces market development from historical baselines through the full forecast horizon. Rather than relying on aggregate figures alone, the analysis disaggregates demand across product types, application settings, and geographic markets, enabling readers to identify where growth is accelerating, which segments are maturing, and how share shifts are unfolding among competing technologies.
A central component of the study is its segmentation architecture. The report examines the market across paint-based, thermoplastic, and cold plastic categories, evaluating the distinct performance profiles, installation requirements, and cost dynamics associated with each. It also explores application environments ranging from roads and highways to parking lots and airports, highlighting how usage intensity, traffic patterns, and specification requirements drive differentiated demand. This segmentation lens allows strategists to assess which product categories are best aligned with specific end-use priorities and to anticipate where substitution trends or technology upgrades may alter purchasing patterns.
Beyond segmentation, the study provides a detailed competitive landscape assessment. It profiles leading participants, examines their product positioning, and evaluates the strategic implications of their offerings in the roadmarking paints space. The analysis considers how companies differentiate through formulation technology, regional compliance readiness, application specialization, and service capabilities. It also explores concentration patterns, identifying how market share is distributed among major players and what that implies for pricing power, partnership opportunities, and entry barriers.
Operational and strategic depth is further reinforced through a structured examination of market dynamics. The report analyzes supply-side constraints, procurement behavior, regulatory impact, and the ways in which raw material and compliance pressures interact to shape margin structures and competitive positioning. This section is designed to help teams translate external market signals into internal planning assumptions, whether for production scheduling, inventory strategy, pricing architecture, or long-range capacity planning.
Competitive Landscape: Strategic Positioning Among Leading Players
The competitive environment in roadmarking paints is defined by a mix of global coatings multinationals and specialized regional suppliers, each pursuing distinct value propositions within a market that rewards both technical performance and specification alignment. Several established companies illustrate the breadth of strategic approaches currently shaping the industry.
PPG Industries, headquartered in Pittsburgh, Pennsylvania, brings a well-recognized portfolio through its ENNIS-FLINT family of waterborne and solvent-based traffic paints. Its offering reflects a focus on formulation versatility and alignment with diverse application requirements, enabling customers to select products that match local specification expectations, environmental constraints, and performance targets. For organizations evaluating supplier partnerships, PPG's positioning underscores the importance of product breadth and the ability to serve multiple marking environments with consistent quality.
Swarco, with headquarters in Austria and global operations, represents a broader systems-oriented approach. Its road marking portfolio spans solvent-based paints, waterborne paints, and two-component systems, reflecting a strategy centered on optionality and technical adaptability. This multi-formulation model allows Swarco to address varying procurement preferences and regulatory environments across different markets. In a sector where local compliance and application conditions can differ sharply from one region to another, such flexibility is a meaningful competitive advantage.
Meon Ltd, based in the United Kingdom, focuses on line marking paints and cold plastic systems for roads, parking lots, and airports. Its product scope highlights the value of serving multiple application environments with specialized formulations that balance durability, application efficiency, and visibility performance. By concentrating on end-use versatility, Meon illustrates how suppliers can capture demand across both high-traffic transportation corridors and structured facilities where marking precision and longevity are critical.
Roadmarking Paints Market
Axalta Coating Systems, operating globally from Belgium, contributes a portfolio that includes spirit-soluble and modified alkyd formulations for road line marking. Its presence in the market reflects the continued relevance of established coating chemistries alongside newer waterborne and low-emission alternatives. This breadth demonstrates how legacy formulation expertise can coexist with evolving compliance demands, particularly in markets where specification transitions are gradual and where buyers still value proven performance characteristics.
Cloverdale Paint Inc, headquartered in Alberta, Canada, emphasizes waterborne traffic paint formulations approved for use in Canadian infrastructure specifications. Its regional alignment illustrates the importance of specification certification and local compliance readiness in public-sector procurement. In markets where bidding eligibility depends on meeting recognized technical standards, suppliers with approved formulations can secure a defensible position even in the face of broader raw material or pricing pressures.
Together, these profiles reveal a competitive arena where differentiation is increasingly tied to formulation adaptability, regulatory readiness, and application-specific reliability. The full report builds on these company-level insights to map share structures, evaluate positioning strategies, and identify where consolidation, partnership, or product innovation is most likely to reshape competitive dynamics.
Strategic Implications for Corporate Planning in 2026 and Beyond
The strategic significance of the roadmarking paints market lies in the intersection of durable demand and evolving operational constraints. Growth is not simply a function of infrastructure spending; it is increasingly shaped by formulation shifts, compliance requirements, and cost-side pressures that influence which products win specification approvals and repeat contracts. For manufacturers, this environment rewards early investment in waterborne and low-emission technologies, disciplined raw material procurement strategies, and close alignment with the specification calendars of public and private buyers. For distributors and applicators, understanding regional demand rhythms and the relative performance economics of paint-based, thermoplastic, and cold plastic systems can improve bidding accuracy and service positioning.
For investors and corporate development teams, the concentration pattern in the market suggests that scale, specification access, and regulatory compliance capabilities remain important barriers. At the same time, the diversity of application environments and product types creates room for specialized suppliers to compete effectively in selected niches. The challenge is to distinguish between short-term pricing noise and structural shifts in demand, a task that requires granular segmentation data, forward-looking scenario analysis, and a clear view of how regulatory updates will alter procurement eligibility over time.
The forecast horizon through 2032 offers a valuable planning window. Organizations that use this period to align product development, capacity strategy, and partnership models with the market's underlying growth path will be better prepared to capture share as older markings are replaced, as new infrastructure projects advance, and as specification standards continue to evolve. The report provides the analytical scaffolding needed to make those decisions with greater confidence, translating market projections into practical strategic options.
From Insight to Action: Why the Full Report Matters
A strategic preview can highlight direction, but the full study is where depth becomes decision-ready intelligence. The complete report brings together historical sizing, forward forecasts, segmentation analysis, competitive profiling, and dynamic market assessment in a single integrated framework. It is designed to support multiple internal use cases: executive briefings, product strategy reviews, procurement planning, market entry evaluations, and investment prioritization. By consolidating both macro trends and operational realities, the study helps teams move from awareness to action without having to reconstruct the analysis from disparate sources.
The report also addresses the practical challenge of navigating uncertainty. Raw material volatility, regulatory updates, and shifting application preferences all introduce variables that can complicate planning. By mapping these forces explicitly and linking them to segmentation behavior and competitive response, the research provides a clearer lens for scenario planning and risk assessment. Readers gain not just a view of what the market is doing, but a structured understanding of why it is moving that way and what that implies for different business functions.
For organizations seeking to stay ahead of specification changes, align product portfolios with emerging demand, and evaluate competitive positioning with greater precision, the full study offers the level of detail required to support high-stakes decisions. The macro trajectory sets the stage, the segmentation and competitive analyses sharpen the focus, and the dynamics section connects external pressures to internal strategy. Together, these components create a comprehensive foundation for planning in a market where performance, compliance, and cost management must be balanced at every step.
The roadmarking paints market is entering a phase in which growth, regulation, and competitive differentiation will increasingly reinforce one another. Companies that approach this environment with rigorous data, clear segmentation insight, and a realistic view of cost and compliance pressures will be best positioned to convert market expansion into durable advantage. This research study is built to provide exactly that strategic clarity, and the full report delivers the depth needed to turn market intelligence into executable planning.
For detailed analysis of this topic, please visit the official page: Roadmarking Paints Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Regenerative Medicine Market Hits $30B in 2025, Projected 22.5% CAGR Through 2032
By pmarketresearch, 2026-09-15
Navigating the Regenerative Medicine Inflection Point: Strategic Intelligence for 2026 Decision-Makers
The regenerative medicine sector has graduated from a promising niche to a defining pillar of global healthcare. As we move through 2026, the convergence of advanced cell and gene therapies with robust tissue engineering platforms is fundamentally reshaping therapeutic paradigms, manufacturing economics, and competitive positioning. For corporate strategists, investors, and R&D leaders, navigating this complexity requires more than high-level trends; it demands granular, actionable intelligence calibrated for immediate decision-making.
Our latest market research study, Regenerative Medicine Market: Strategic Outlook 2026-2032 , delivers precisely that. This report serves as a comprehensive navigation system for organizations operating at the intersection of biotechnology, advanced manufacturing, and healthcare delivery. By synthesizing historical trajectory analysis, macroeconomic forecasting, competitive mapping, and granular regulatory assessment, we provide the analytical rigor necessary to navigate an environment characterized by rapid innovation cycles, evolving policy frameworks, and intense competitive jockeying.
A Market on a Compounding Growth Trajectory
The macroeconomic architecture of the regenerative medicine landscape has demonstrated remarkable resilience and expansion momentum. Over the historical evaluation window of 2020 through 2025, the sector's revenue base scaled from approximately 12.5 billion USD to 30.0 billion USD, reflecting a sustained compound annual growth trajectory that has consistently outpaced broader biopharma benchmarks. This foundational expansion has established a critical inflection point entering the current forecast horizon.
The forward-looking projections through 2032 illustrate a market poised for structural acceleration. Starting from a 2025 baseline of 30.0 billion USD, revenue trajectories are expected to climb to 37.16 billion USD in 2026, with compounding momentum driving valuations to 45.17 billion USD by 2027, and continuing upward through the latter half of the decade. The established forecast compound annual growth rate of twenty-two and a half percent underscores an environment where revenue generation mechanisms are scaling faster than traditional therapeutic categories. This growth velocity is not merely a statistical projection; it represents a fundamental recalibration of therapeutic economics, where the convergence of autologous and allogeneic platforms, advanced manufacturing capabilities, and expanding clinical applications creates compounding value streams.
However, translating top-line growth forecasts into executable corporate strategy requires more than directional numbers. It demands a precise understanding of where capital efficiency, therapeutic differentiation, and regulatory tailwinds intersect. Our analysis isolates the structural drivers enabling this sustained expansion, providing decision-makers with the contextual clarity needed to allocate resources, prioritize pipeline development, and position portfolios against emerging competitive threats.
Architects of Competitive Advantage in an Evolving Landscape
The regenerative medicine competitive arena is characterized by a distinguished blend of pharmaceutical legacy players, specialized cell and gene therapy developers, and tissue-engineering innovators. The sector exhibits moderate concentration dynamics, with the top three market participants collectively commanding forty-five percent of total revenue share, while the top five entities extend that influence to sixty-two percent. This concentration pattern reflects a landscape where established biopharma organizations leverage scale, regulatory expertise, and commercial infrastructure, while agile mid-tier developers capitalize on scientific novelty and niche therapeutic positioning.
Leading the pharmacological forefront, Novartis AG has cemented its position through pioneering autologous CAR-T cell therapies and breakthrough gene therapy modalities, including landmark treatments for hematologic malignancies and spinal muscular atrophy. The company's recent regulatory milestone involving expanded-use authorizations for next-generation neuromuscular therapies exemplifies how strategic lifecycle management drives sustained market relevance. Similarly, Gilead Sciences, Inc. has engineered a formidable presence in the cell therapy space through its portfolio of autologous CAR-T interventions targeting hematologic cancers, demonstrating the commercial viability of highly specialized manufacturing ecosystems. Bristol-Myers Squibb Company continues to advance its cell and gene therapy portfolio, particularly in multiple myeloma and related indications, while Amgen Inc. pushes the boundaries of allogeneic and autologous cellular platforms for refractory oncology applications.
In the tissue engineering and regenerative scaffolding domain, Smith+Nephew plc and Integra LifeSciences Corporation provide critical infrastructure for wound healing, orthopedic reconstruction, and neurosurgical applications, leveraging biologic matrices and engineered products that bridge acute care and long-term tissue restoration. Organogenesis Holdings Inc. and Cook Biotech, Inc. further reinforce this segment through advanced cellular and tissue-based product development, addressing complex wound management challenges and surgical regeneration requirements. Specialized innovators such as Mesoblast Ltd. and Vericel Corporation have carved out defensible positions in allogeneic mesenchymal stromal cell therapies, cartilage repair, and severe burn interventions, illustrating how therapeutic specificity can command premium positioning. Astellas Pharma Inc. remains focused on cardiovascular and orthopedic regenerative applications, while Pfizer Inc. continues commercializing gene therapy solutions for rare genetic disorders. Together, these organizations represent a multidimensional competitive mosaic where differentiation spans scientific platform type, therapeutic application breadth, manufacturing modality, and commercial execution capability.
Navigating the Decision Matrix: What Our Report Delivers
Translating macro-level growth trajectories and competitive overviews into boardroom-ready strategies requires a structured analytical approach. Our research methodology is designed to function as a strategic decision-support toolkit, delivering precisely the information layers that executives need to move from awareness to action.
The study begins with a comprehensive market sizing and forecasting architecture that maps historical performance from 2020 through the immediate 2025 baseline, then projects forward through a seven-year forecast horizon extending to 2032. This temporal framing allows organizations to stress-test growth assumptions, benchmark pipeline commercialization timelines against anticipated market absorption curves, and identify inflection windows where strategic investment yields maximum leverage. Crucially, the analytical structure avoids superficial aggregation; instead, it deconstructs revenue generation pathways, identifies the therapeutic and technological vectors that will dictate share allocation, and highlights the operational prerequisites required to capture disproportionate value.
Stem Cell Therapy Market
Our segmentation analysis dissects the commercial landscape across core therapeutic categories, delivery and application domains, and geographic dimensions. Rather than presenting fragmented percentage breakdowns, the report synthesizes these dimensions into an integrated strategic map that reveals where platform maturity, clinical demand, and manufacturing feasibility align. This approach enables R&D pipeline managers to evaluate therapeutic area prioritization with greater precision, while commercial leadership teams can assess geographic expansion timing against evolving reimbursement landscapes and regulatory readiness. The analysis also quantifies cross-segment dependencies, illustrating how innovations in one domain—such as advanced autologous manufacturing—create cascading effects across adjacent product categories and regional commercialization strategies.
Competitively, the report provides detailed corporate profiling for the sector's most influential participants, mapping their strategic positioning, pipeline emphasis, manufacturing modalities, and recent commercial milestones. Each profile is structured to support benchmarking exercises, partnership evaluation, and competitive response planning. By contextualizing recent corporate developments, regulatory interactions, and therapeutic approvals within broader market dynamics, the analysis reveals not just who is competing, but how competitive advantage is being constructed and defended in real time.
The 2026 Inflection: Regulatory Tailwinds, Operational Friction, and Strategic Imperatives
The current market environment is being actively reshaped by a series of interconnected dynamics that demand strategic recalibration. Regulatory frameworks are evolving to accommodate the unique scientific and manufacturing realities of regenerative interventions. In September 2025, the U.S. Food and Drug Administration issued draft guidance detailing expedited development programs for regenerative medicine therapies targeting serious conditions, explicitly outlining Regenerative Medicine Advanced Therapy designations and accelerated approval pathways. This guidance was followed in January 2026 by the agency's announcement of increased flexibility regarding Chemistry, Manufacturing, and Controls requirements for cell and gene therapies, including permissive release criteria within investigational new drug applications and reduced comparability data expectations. These regulatory shifts collectively lower historical barriers to clinical progression while signaling a more adaptive review environment for developers capable of demonstrating robust clinical benefit.
Commercialization, however, still encounters structural friction. High treatment costs and inconsistent reimbursement policies continue to constrain broader adoption of regenerative medicine therapies, particularly for cell and gene interventions that demand specialized manufacturing workflows and stringent cold-chain logistics. The financial structures supporting patient access remain fragmented across payers and health systems, creating variable adoption velocities that differ significantly by therapeutic category and geographic market. Simultaneously, supply chain resilience has emerged as a critical operational vulnerability. Approximately thirty-five percent of regenerative medicine manufacturers rely on imported key starting materials, a dependency that becomes particularly acute given the small-batch, patient-specific nature of many production processes and the narrow operational windows between apheresis collection, manufacturing completion, and clinical delivery. Manufacturing economics further compound these challenges, with per-batch cell therapy costs spanning a wide range driven by labor-intensive processing, specialized technical expertise, and scalability constraints inherent to small patient populations.
Recent corporate and regulatory developments throughout late 2025 and early 2026 illustrate how these dynamics are actively unfolding in practice. Regulatory approvals expanded into novel therapeutic territories, with non-profit-led gene therapy initiatives gaining authorization pathways and taxpayer-funded translational programs achieving their first commercial clearances. Industry participants navigated complex submission cycles, including priority-reviewed biologics license applications with accelerated review timelines. Manufacturing and commercial organizations simultaneously adjusted operational frameworks in response to evolving regulatory expectations, recalibrating quality systems, comparative data requirements, and supply chain contingencies to align with the new regulatory posture.
For strategic planners, the implication is clear: the companies that will capture disproportionate value in this environment are those treating regulatory engagement, reimbursement strategy, manufacturing scalability, and supply chain redundancy as integrated strategic pillars rather than isolated operational functions. Our report maps these interconnections explicitly, providing scenario-based guidance on how to align pipeline development, commercial launch sequencing, and partnership strategy with the evolving regulatory and reimbursement architecture.
Regenerative Medicine Market
From Insight to Execution: Why This Report Matters Now
In a market expanding at a twenty-two and a half percent compound annual rate through the end of the decade, the cost of strategic misalignment compounds rapidly. Organizations that rely on fragmented data sources, outdated competitive assessments, or generalized growth narratives risk misallocating capital, missing regulatory windows, and ceding positioning to competitors with more precise market intelligence. Our research is engineered to eliminate that uncertainty.
The report functions as a centralized strategic resource for multiple decision-making workflows. Corporate development teams can utilize the competitive mapping and segmentation architecture to evaluate acquisition targets, identify partnership opportunities, and assess white-space positioning within therapeutic categories where platform maturity and demand intensity converge. R&D and pipeline leadership can leverage the regulatory timeline assessment and manufacturing economics analysis to prioritize internal programs, design clinical development strategies that align with expedited pathway eligibility, and structure manufacturing workflows that balance scalability with patient-specific customization. Commercial and market access leadership can draw on the reimbursement and adoption friction analysis to design launch strategies that anticipate payer engagement requirements, optimize pricing architectures, and sequence geographic rollouts according to regulatory readiness and reimbursement maturity.
Furthermore, the report's forward-looking scenario construction extends beyond static forecasting. By modeling how regulatory flexibility, supply chain restructuring, and competitive concentration dynamics will interact across the 2026 to 2032 horizon, the analysis enables organizations to prepare for multiple plausible futures rather than betting exclusively on a single trajectory. This scenario-based approach is essential in a sector where scientific breakthroughs, policy adjustments, and manufacturing innovations can rapidly alter competitive positioning and market absorption velocity.
Access the Complete Strategic Intelligence
The regenerative medicine landscape is entering a decisive phase where competitive advantage will be determined by the precision of strategic intelligence, the agility of operational response, and the sophistication of cross-functional alignment. High-level trend awareness is no longer sufficient. Executives require detailed, integrated analysis that connects market sizing architecture, competitive positioning, regulatory evolution, reimbursement friction, and manufacturing economics into a coherent decision-making framework.
Our full report delivers that framework. It expands upon the market trajectory, segmentation dynamics, competitive profiles, regulatory and operational developments, and strategic recommendations outlined here, providing the comprehensive intelligence necessary to plan, execute, and defend strategic initiatives through 2032 and beyond. To access the complete analysis, including granular segmentation breakdowns, detailed competitive benchmarking, scenario modeling, and actionable strategic recommendations, visit the PW Consulting research portal and secure your copy of the Regenerative Medicine Market Strategic Outlook. Equip your organization with the intelligence required to navigate this inflection point with confidence.
For detailed analysis of this topic, please visit the official page: Regenerative Medicine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: UPS Market Projected to Hit $265.95M by 2032 with 5.85% CAGR
By pmarketresearch, 2026-09-15
Strategic Resilience: Navigating the Uninterruptible Power System Market Through 2032
The global landscape of power infrastructure is undergoing a seismic shift, driven by an insatiable demand for continuity in an increasingly digitized world. For enterprise leaders, investors, and industry strategists, the Uninterruptible Power System (UPS) market represents more than just a safeguard against outage; it is a critical component of operational resilience, data integrity, and technological enablement. As we navigate the forecast period extending to 2032, understanding the intricate dynamics of this market is no longer optional—it is a strategic imperative.
This article serves as a strategic preamble to PW Consulting's comprehensive market research on the Uninterruptible Power System (UPS) Market. It outlines the macroeconomic trajectory, competitive intensity, and technological inflection points that define the sector. However, true strategic advantage lies in granularity. While here we establish the high-level framework, the full report offers the specific segmentation data and actionable intelligence required to make informed investment and procurement decisions.
Market Trajectory and Growth Indicators
The historical performance of the UPS market from 2020 to 2025 lays a robust foundation for future expansion. Valued at approximately 130.45 Million USD in 2020, the market has demonstrated consistent resilience and growth, culminating in an estimated valuation of 180.25 Million USD in 2025. This upward trajectory reflects the broader industrial and technological trends prioritizing power stability. The momentum is expected to accelerate as we move into the forecast period from 2026 to 2032.
Projected figures indicate that the market will reach 186.66 Million USD in 2026, continuing to climb toward 265.95 Million USD by the end of the forecast window in 2032. This growth path suggests a Compound Annual Growth Rate (CAGR) of roughly 5.85 percent over the forecast period. Such sustained growth is not merely a function of population or economic expansion but is deeply tied to the critical nature of the applications these systems support. For stakeholders, this macro view signals a healthy, expanding market, but the real value lies in understanding where this growth is concentrated and what drives it.
Key Drivers of Expansion
Several macro-industrial forces are propelling this demand. The proliferation of data centers stands out as a primary catalyst, given the critical nature of server uptime in cloud computing and enterprise IT. Similarly, the telecommunications sector relies heavily on UPS solutions to maintain signal integrity and network availability. Beyond infrastructure, sectors such as healthcare and industrial manufacturing are increasingly adopting advanced power protection to safeguard sensitive equipment and ensure safety compliance.
Furthermore, the residential sector continues to contribute to the base load of demand, driven by the adoption of smart home technologies and remote work infrastructure. As energy grids face increasing strain from renewable integration and peak load demands, the role of the UPS evolves from a backup mechanism to a key element of energy management systems. Understanding the specific velocity of growth across these applications requires detailed analysis, which is extensively covered in the full research document.
Competitive Landscape and Market Concentration
The UPS market is characterized by a moderately concentrated competitive environment. Current analysis suggests that the top three players hold approximately 42.5 percent of the market share, while the top five players account for around 55.8 percent. This concentration indicates a market where dominant incumbents hold significant sway, yet there remains ample room for specialized players and regional challengers to carve out niches.
Uninterrupted Power Supply (UPS) Market
Leading the charge are established global entities such as Schneider Electric, headquartered in France, and Eaton, based in Ireland. These companies continue to refine their offerings to cater to diverse industrial needs. Vertiv, operating out of the United States, has been particularly active in recent months, signaling aggressive innovation. Other key players like ABB from Switzerland, Delta Electronics from Taiwan, and Riello UPS from Italy maintain strong footholds with specialized engineering capabilities.
The landscape is further diversified by significant contributions from Asian manufacturers. Huawei and Toshiba bring distinct technological strengths to the table, while companies like Piller in Austria and Kehua Data and INVT in China represent the growing technical prowess of the region. Additionally, domestic players such as Falcon Electric and Active Power in the United States serve specific market segments with tailored solutions. Navigating this ecosystem requires a clear understanding of each player's strategic positioning, which the full report dissects in detail.
Recent Strategic Developments
The pace of innovation in the UPS sector is accelerating, as evidenced by recent product launches and regulatory milestones. In early 2026, Vertiv introduced the Vertiv PowerUPS 6000 Industrial UPS system. This launch targeted commercial and industrial markets, including manufacturing, transportation, and oil and gas, signaling a push toward ruggedized power solutions. Later in May 2026, Vertiv expanded this portfolio with the Vertiv PowerUPS 200 family for connected homes and workspaces, ranging from 600 VA to 1500 VA, alongside the Vertiv PowerUPS 100 Standby Series designed for distributed digital environments.
Simultaneously, ABB made waves at Data Center World Washington 2026 with the introduction of the HiPerGuard 34.5kV. This medium-voltage UPS enables AI data centers to connect directly to the 34.5kV grid without voltage conversion, achieving UL 9540 certification for energy storage safety and performance. This development is critical for reducing conversion losses and simplifying infrastructure for high-density computing. In a similar vein, Schneider Electric released what is described as the most compact 3-phase UPS in its class, expanding power protection for high-density IT and industrial applications.
These moves are not isolated product launches; they represent strategic pivots toward efficiency, density, and integration. The industry context also highlights regulatory and infrastructure shifts. For instance, the HiPerGuard portfolio's IEC and UL certification across voltage levels from 4.16kV to 34.5kV underscores a trend toward microgrid-ready architecture integrating battery storage, gas generation, and renewables. Meanwhile, suppliers like EnerSys expanded lithium-ion UPS battery portfolios in 2025, optimizing configurations for edge data center and distributed IT room deployments.
Strategic Implications for 2026 and Beyond
For decision-makers, the implications of these dynamics are profound. The convergence of AI-driven data center requirements, industrial automation, and green energy transitions is reshaping the UPS value proposition. Companies must evaluate not just the capacity of power protection systems, but their efficiency, scalability, and compatibility with future energy architectures. The market growth projected through 2032 suggests that early movers who align their infrastructure with these trends will secure significant operational advantages.
However, the sheer volume of data required to make these strategic alignments effectively is substantial. Knowing the overall market size is useful, but knowing the specific growth rates within distinct regional zones, the exact revenue splits by technology type, and the nuanced performance of competitors in specific application verticals is where true insight is found. The report delves into these specifics without holding back the granular details necessary for precise planning.
Deep Dive into Report Contents
PW Consulting's full market research report is designed to be a practical tool for strategy formulation. It goes beyond high-level trends to provide actionable intelligence. The content is structured to assist in market entry analysis, competitive benchmarking, and capacity planning. The report details the segmentation splits which reveal where the actual revenue volumes are accumulating across different geographies and technology types.
Readers of the full study will gain access to a breakdown of the market by region, highlighting the relative leadership and growth potential of areas such as North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa. Furthermore, the analysis by type provides clarity on the performance of Standby, Line-Interactive, and Online UPS systems, allowing for targeted product strategy. The application segment analysis further dissects demand drivers across Data Centers, Telecommunications, Healthcare, Industrial Manufacturing, and Residential sectors.
Uninterruptible Power System (UPS) Market
Each section includes qualitative assessments of regulatory impacts, supply chain dynamics, and technological barriers. The competitive profile section offers detailed snapshots of the key companies, including their headquarters, strategic focus, and recent developments. This level of detail allows stakeholders to map out competitive threats and identify partnership opportunities with greater precision.
Conclusion: The Premium of Precision
In a market defined by stability and precision, vague estimates are insufficient. The UPS market is poised for significant growth, driven by technological necessity and infrastructural evolution. The data indicates a clear path forward, but the route depends on specific variables that only detailed research can uncover. Whether you are looking to invest, expand, or optimize your current power infrastructure, the difference between a good strategy and a great one lies in the details.
This overview has outlined the macroeconomic scene and the competitive intensity. To access the specific revenue figures, regional growth rates, and proprietary segmentation data that will inform your 2026 planning, we invite you to consult the full report. The intelligence contained within is designed to transform uncertainty into strategic clarity.
For the complete dataset, including exact market values for each segment and comprehensive competitor profiles, please visit the source webpage to download the full Uninterruptible Power System (UPS) Market Research Study.
For detailed analysis of this topic, please visit the official page: Uninterruptible Power System (UPS) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: IP Camera Market to Reach $32.22B by 2032, Driven by 13.0% CAGR
By pmarketresearch, 2026-09-15
Unlocking the Strategic Value of the Global IP Cameras Market: A 2026 Decision-Maker’s Guide
The surveillance ecosystem is undergoing a structural transformation. What was once a straightforward security expenditure is now a strategic infrastructure investment, driven by artificial intelligence, cloud management, regulatory compliance, and expanding use cases across commercial, residential, and government environments. PW Consulting’s latest research on the IP Cameras Market is designed to convert this complexity into actionable intelligence for enterprise leaders, procurement teams, investors, and technology strategists navigating the 2026 decision cycle.
This flagship report does not merely chart historical trajectory; it equips stakeholders with the analytical scaffolding required to allocate capital, shape product roadmaps, anticipate regulatory shifts, and position against an increasingly concentrated competitive field. Below, we outline the strategic architecture of the study, the operational content it delivers, and why its insights will prove indispensable for organizations operating through 2026 and beyond.
The Macro Trajectory: Why 2026 Is a Strategic Inflection Point
Drawing on historical data spanning 2020 through 2025 and a forward-looking forecast window extending to 2032, the research captures a market that has demonstrated remarkable resilience and compounding momentum. Over the past half-decade, global IP camera revenue has expanded from $8.15 billion in 2020 to $13.72 billion in 2025, reflecting sustained demand across both mature deployment zones and rapidly emerging end-user segments.
The forward curve continues this acceleration. Forecasts indicate the market will reach $15.99 billion in 2026 and scale to $32.22 billion by 2032, underpinned by a compound annual growth rate of 13.0 percent. This trajectory is not simply a function of incremental unit growth; it reflects structural adoption drivers including AI-enabled analytics, cloud-native management platforms, heightened safety and compliance mandates, and the integration of visual surveillance into broader operational and clinical workflows. For enterprise decision-makers, understanding the timing, pacing, and underlying catalysts of this expansion is essential. Misjudging the velocity of adoption can result in misaligned capital deployment, obsolete product strategies, or missed partnership opportunities.
Industrial Cameras Market
Importantly, the research contextualizes these headline figures within the operational realities that shape procurement cycles, budget approvals, and regional rollout strategies. It examines how evolving reimbursement environments, capital expenditure constraints, and compliance requirements intersect with technology refresh timelines, giving leaders a grounded view of what is commercially viable and strategically advisable in 2026.
Report Content Overview: Operational Intelligence You Can Deploy
Designed for practitioners rather than passive observers, the report translates market signals into structured, operational content. Stakeholders will find a comprehensive framework built around the following deliverables:
- Market sizing and historical reconstruction (2020–2025): A rigorous baseline that reconciles retrospective revenues with documented adoption patterns, providing auditable reference points for internal forecasting models and investment committees.
- Forward-looking forecast (2026–2032): Scenario-grounded projections that illuminate pathway dependencies, growth inflection points, and the pacing of demand across evolving technology and compliance landscapes.
- Segmentation architecture: A multi-dimensional breakdown examining how different camera types, application environments, and regional dynamics interact to shape total addressable demand. The report shows how segment performance diverges, where adoption accelerates, and which structural factors constrain or amplify growth in specific deployment contexts.
- Competitive landscape and concentration analysis: Detailed profiles of leading manufacturers and platform providers, combined with market concentration metrics that reveal the balance between established incumbents and emerging challengers. This section helps readers assess competitive moats, partnership viability, and supplier diversification strategies.
- Regulatory and compliance mapping: A structured view of the legal and procurement frameworks influencing IP camera selection, including federal buying rules, healthcare data protection requirements, and region-specific certification mandates that reshape eligibility and deployment risk.
- Technology and product development tracking: Coverage of recent product launches, sustainability initiatives, and platform innovations that signal where manufacturers are directing R&D investment and how those decisions cascade into customer value propositions.
- Decision-support frameworks: Practical tools to evaluate vendor selection, compliance readiness, total cost of ownership, integration complexity, and upgrade pathways, enabling procurement and IT leaders to move from strategic intent to execution.
Rather than presenting isolated data points, the study threads these elements together into a coherent narrative about how market forces, technology maturity, regulatory pressure, and competitive positioning converge to define winning strategies in 2026.
Navigating the Competitive Landscape
The IP cameras market is defined by a blend of deep vertical expertise, platform differentiation, and intensifying strategic positioning. Market concentration data included in the report reveals a landscape where a relatively small group of players accounts for a substantial share of total revenue, reinforcing the importance of supplier evaluation, partnership architecture, and long-term vendor risk management.
Several manufacturers have built identifiable strengths around specific deployment contexts and compliance pathways. Axis Communications, based in Lund, Sweden, has strengthened its reputation around ARTPEC-based network IP cameras optimized for sensitive environments, including healthcare surveillance and privacy-compliant installations. Its September 2025 launch of an environmentally sustainable IP camera line using recycled materials reflects broader industry movement toward responsible manufacturing and product lifecycle considerations.
Hanwha Vision, headquartered in South Korea, continues to advance AI-enabled IP cameras and modular systems with integration pathways that support hospital safety, fall detection, and clinical workflows, including connections with Epic EHR environments. This illustrates a growing trend in which IP camera providers are no longer fulfilling a purely observational role but are becoming embedded participants in operational and safety workflows.
Dahua Technology, based in Hangzhou, China, has expanded its footprint through video-centric AIoT IP cameras and security solutions aimed at operational efficiency and regulatory compliance within hospital facilities. Bosch Security Systems, from Stuttgart, Germany, develops advanced IP camera systems tailored for healthcare security monitoring and integration with hospital infrastructure, reinforcing the importance of systems-level interoperability.
Pelco, operating from Fresno, California, produces IP camera series specifically engineered for patient safety monitoring and regulatory-compliant applications, while Hikvision has long maintained a presence in network IP cameras and facility-oriented hospital solutions focused on patient and visitor security and operational oversight. Verkada, based in San Mateo, represents the cloud-managed segment with platforms that incorporate HIPAA compliance and privacy features for healthcare facility security. Honeywell International, from Charlotte, North Carolina, contributes Performance Series and explosion-proof IP cameras suited for secure healthcare environments and facility upgrades. Arecont Vision, a U.S.-based manufacturer, is recognized for megapixel IP cameras selected for high-quality video coverage and system upgrades within hospital surveillance environments.
These profiles are not presented merely as company summaries. The report uses them to illustrate how different firms compete on architecture, compliance readiness, vertical integration, cloud versus on-premises models, and ecosystem partnerships. It also examines how procurement eligibility rules and regional certification requirements alter the competitive field, shaping which manufacturers can realistically participate in certain buyer segments.
Regulatory Dynamics and Compliance as Strategic Risk
One of the most consequential themes for 2026 is the rise of compliance as a gating factor in procurement. Federal buying environments increasingly require selection of NDAA-compliant IP cameras, with eligibility considerations that directly influence supplier eligibility for public-sector and contractor-adjacent deployments. At the same time, healthcare-focused deployments face HIPAA-driven expectations around data handling, access controls, and privacy-preserving features such as face blurring and secure authentication.
Beyond North America, regulatory momentum is reshaping deployment speed and product eligibility in other markets. From April 2026, STQC Essential Requirements compliance for CCTV and IP cameras becomes mandatory in India for all healthcare facility deployments. This creates a compliance deadline that procurement teams, system integrators, and technology vendors must plan around when evaluating rollout schedules, certification pathways, and vendor selection.
These regulatory layers cannot be treated as afterthoughts. They affect design requirements, supplier shortlists, integration complexity, renewal cycles, and total cost of ownership. The report structures compliance considerations as a strategic dimension rather than a legal footnote, giving leaders a clearer view of where risk concentrates and how to build procurement frameworks that remain resilient under evolving policy conditions.
IP Cameras Market
Technology Trends and Deployment Realities
The market’s growth is being reshaped not only by demand volume but by how the technology is deployed and valued. Fixed dome IP cameras continue to dominate many hospital installations because their discreet design, vandal resistance, and reliable coverage suit corridors and waiting areas where operational visibility must coexist with a patient-facing environment. This preference illustrates a broader principle: the winner in a given deployment scenario is often determined by installation constraints, environmental factors, and integration needs as much as by raw specification comparisons.
At the same time, the shift toward AI-powered IP camera systems with analytics capabilities introduces a strategic tension. Hospitals and other organizations want the operational efficiency and safety gains these analytics can provide, yet they frequently face capital expenditure constraints when upgrading legacy surveillance infrastructure. The report examines this dynamic in detail, exploring how organizations sequence upgrades, justify investments, and balance immediate security needs against longer-term analytics ambitions.
Cloud-managed platforms, privacy-preserving features, and sustainability-oriented product design are additional vectors shaping buyer preferences. Recent product activity, including sustainability-focused launches and platform-level compliance enhancements, signals that manufacturers are competing not only on image quality and reliability but on lifecycle impact, management simplicity, and regulatory readiness. For decision-makers, these qualities increasingly influence vendor selection because they affect long-term operating costs, audit exposure, and organizational alignment with internal sustainability or risk mandates.
Why This Report Matters for 2026 Decision-Making
The IP Cameras Market research is built for leaders who need more than a top-line number. Whether the objective is to plan a procurement cycle, prioritize product roadmap investments, evaluate market entry, assess supplier diversification, or prepare for regulatory deadlines, the study provides the context required to make those decisions with confidence.
Specifically, the report helps organizations:
- Understand where market momentum is strongest and what structural factors are propelling it.
- Evaluate competitive positioning with attention to concentration, vertical specialization, and platform differentiation.
- Anticipate compliance obligations and incorporate them into procurement and deployment planning.
- Align technology refresh strategies with budget cycles, operational priorities, and analytics roadmaps.
- Identify where sustainability, cloud management, and privacy features are becoming decisive purchase criteria.
By connecting market size, segmentation logic, competitive behavior, and regulatory dynamics within a single analytical frame, the report converts fragmented signals into a coherent strategy input. That integration is especially critical in 2026, when procurement teams and technology leaders must make multi-year commitments in an environment shaped by fast-moving compliance requirements, shifting deployment norms, and increasingly concentrated supplier options.
Next Steps: Accessing the Full Intelligence
This overview has outlined the strategic architecture of the study and the operational value it delivers. It has deliberately avoided itemizing the granular segment breakdowns, individual regional revenue figures, and detailed application-level splits that form the analytical backbone of the full report. Those specifics are essential for precise planning, but they are also the kind of proprietary intelligence that warrants deeper examination within the complete research package.
For decision-makers ready to move from strategic awareness to execution, the full report provides the detailed segment mapping, competitive profiles, compliance timelines, and forecast pathways needed to support board-level discussion, procurement selection, and product strategy formulation. Accessing the complete publication will give your team the specificity required to translate 2026 market momentum into disciplined, evidence-based decisions.
The IP cameras market is expanding with clarity and momentum. The question for enterprise leaders is no longer whether the category is growing, but how to position intelligently within it. PW Consulting’s research is designed to answer that question with the depth, discipline, and decision-ready structure your organization needs.
For detailed analysis of this topic, please visit the official page: IP Cameras Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Cable Glands Market Hits $1.8B in 2025, Projects 6.5% CAGR to 2032
By pmarketresearch, 2026-09-15
Cable Glands Market Strategic Outlook 2026: Navigating Growth, Compliance, and Competitive Intensity
Executive Summary: Why This Research Matters Now
The global cable glands market stands at a pivotal inflection point as industries confront tightening safety regulations, volatile raw material costs, and accelerating infrastructure modernization. For executives planning capital allocation, supplier diversification, and product roadmap investments through 2032, fragmented intelligence is no longer sufficient. Our latest market research translates macroeconomic trajectories into actionable strategic frameworks, enabling leadership teams to anticipate compliance shifts, optimize material sourcing, and position portfolios against entrenched competitors. This article previews the analytical depth available in the full study, highlighting the structural drivers, competitive dynamics, and decision-support tools that will define your 2026 planning cycle.
Market Trajectory: From Recovery to Sustained Expansion
Between 2020 and 2025, the cable glands sector demonstrated consistent revenue expansion, climbing from approximately USD 1.5 billion to an estimated USD 1.8 billion. The upward momentum is projected to accelerate through the forecast window ending in 2032, with a compound annual growth rate of 6.5 percent. By the close of the projection period, total market revenue is expected to approach USD 2.78 billion. This trajectory is not merely a reflection of incremental demand; it signals a structural upgrade cycle across industrial, energy, and infrastructure sectors where cable entry integrity, environmental sealing, and hazardous-location compliance have become non-negotiable design parameters.
Several converging forces underpin this expansion. Global electrification initiatives continue to drive cable deployment in power distribution, manufacturing automation, and renewable energy installations. Simultaneously, regulatory frameworks governing explosive atmospheres, moisture ingress, and electromagnetic compatibility are pushing engineers toward certified cable gland solutions rather than generic hardware. Raw material cost fluctuations—spanning brass, aluminum, plastic polymers, and nickel-plated steel—remain a persistent pressure point for manufacturers, influencing both pricing strategies and margin management. Yet, demand resilience across end-use sectors has consistently absorbed these inputs, reinforcing a market environment where scale, certification breadth, and supply chain agility determine competitive outcomes.
Strategic Implications of the Growth Curve
A 6.5 percent CAGR in a mature industrial hardware category is meaningful only when mapped to specific investment horizons. For procurement leaders, the forecast underscores the urgency of locking in long-term supplier agreements before capacity constraints tighten. For product managers, the growth window creates room to differentiate through specialized certifications, modular gland designs, and material innovations that reduce total cost of ownership. For corporate development teams, the expansion trajectory suggests that consolidation, geographic capacity expansion, and portfolio adjacencies will remain active themes among well-capitalized incumbents. The full research study quantifies these pathways without relying on speculative assumptions, anchoring each recommendation in observable market behavior and regulatory timelines.
Segmentation Architecture: Where Value Is Created and Captured
The market’s structural composition reveals clear concentration patterns that influence pricing power, innovation pacing, and customer acquisition strategies. Demand is distributed across multiple dimensional axes—by region, by type, by cable construction, by material, and by end-use industry—each carrying distinct margin profiles and compliance requirements. Understanding how these segments interact enables companies to avoid the common pitfall of treating cable glands as a commodity line item rather than a engineered interface with safety-critical performance expectations.
Hazardous Versus Non-Hazardous Applications
The split between hazardous-area and non-hazardous-area cable glands reflects a fundamental divergence in engineering requirements. Non-hazardous applications dominate overall volume, driven by general industrial, commercial, and infrastructure deployments where environmental sealing and strain relief are the primary value drivers. Hazardous-area solutions, while smaller in aggregate share, command premium positioning due to the rigorous certification burdens, specialized materials, and testing protocols required for explosive atmospheres. The strategic question for manufacturers is whether to deepen expertise in high-compliance niches or to scale broadly across standard applications while offering certified options as a differentiated tier. The research study maps the competitive positioning within each segment, highlighting where certification breadth, lead-time reliability, and technical support create durable barriers rather than transient price advantages.
Material and Cable Construction Dynamics
Material selection continues to shape both cost structures and end-customer preferences. Brass, stainless steel, and plastic nylon each offer distinct trade-offs in corrosion resistance, mechanical durability, weight, and procurement cost. Armored and unarmored cable constructions further differentiate installation requirements, clamping mechanisms, and sealing performance. Price volatility in base metals and polymer feedstocks has forced manufacturers to reassess bill-of-materials strategy, inventory buffering, and regional sourcing mixes. Companies that have integrated material forecasting with production scheduling are better positioned to stabilize pricing and maintain service levels during supply disruptions. The full report examines how leading producers are recalibrating material portfolios in response to these pressures, including the strategic use of nickel-plated brass, aluminum alternatives, and high-temperature polyamide formulations for specialized applications.
End-Use Industry Exposure
Demand flows from a diversified industrial base, with oil and gas, power and utilities, manufacturing and process industries, construction, and other sectors each contributing distinct growth drivers. Oil and gas operations prioritize flameproof and intrinsically safe glands for upstream and downstream environments, while power and utilities focus on long-term durability, weather resistance, and compliance with grid-installation standards. Manufacturing and process industries require glands that support automation density, frequent maintenance cycles, and chemical exposure resistance. Construction and ancillary segments often emphasize cost efficiency, ease of installation, and broad dimensional coverage. The research study isolates the demand signatures of each sector, helping executives align product lines, certification investments, and channel strategies with the industries where their capabilities generate the strongest competitive advantage.
Competitive Landscape: Incumbent Strength and Regional Diversification
Market concentration data indicates that the top three participants command roughly 45 percent of total revenue, while the top five collectively account for approximately 60 percent. This concentration level suggests a market where scale, global certification portfolios, and established distribution networks provide meaningful advantages, yet it also leaves substantial room for specialized manufacturers and regional players to compete through niche engineering, service responsiveness, and localized compliance expertise.
Global Incumbents and Specialty Leaders
Several established manufacturers illustrate the range of competitive strategies shaping the market. Hawke International has built a leading position in Exd and Exe cable glands and connection solutions for hazardous locations, leveraging deep expertise in explosion protection and global type approvals. HELUKABEL distinguishes itself through plastic and metal gland solutions that emphasize airtight seals, dust and moisture protection, and strain relief, supported by a broad industrial portfolio. ABB supplies industrial cable glands with widespread certifications and type approvals across wet, dry, indoor, outdoor, and corrosive environments, aligning its offerings with large-scale infrastructure and process deployments. Cembre contributes nickel-plated brass MAXIBRASS series glands with IP and EMC protection levels, appealing to customers seeking robust mechanical performance and standardized protection ratings. Phoenix Contact and Lapp Group both maintain strong positions in high-quality industrial cable connections, with Lapp Group’s SKINTOP® line spanning plastic, nickel-plated brass, and stainless steel metric glands, reinforcing a reputation for specification-grade reliability.
Regional and specialty manufacturers add further complexity to the landscape. AerosUSA serves as the exclusive U.S. supplier of AGRO Syntec and Syntec Anti-Kink polyamide glands featuring lamellar technology for multiple cable diameters, targeting buyers who value compact design and flexible diameter accommodation. Weyer Electric and Shanghai Weyer Electric Co., Ltd. operate as high-tech enterprises producing nylon, metal, and high-temperature multi-core glands, with an expanding footprint across new energy, railway, aerospace, and industrial applications. CGS Cable Glands has established itself as a leading Indian manufacturer with more than 28 years of experience in weatherproof, EMC, and flameproof solutions, reflecting the growing importance of Indian production capacity in both domestic and export markets. CMP Products, headquartered in Johannesburg, maintains a global leadership position in cable glands, cleats, and accessories, underscoring the strategic relevance of African manufacturing hubs in supply chains serving mining, energy, and industrial sectors.
Recent Market Activity and Momentum Signals
Competitive intensity is visible not only in product portfolios but in external engagement and innovation visibility. In June 2026, AerosUSA exhibited at RSSI to showcase cable glands and industrial wire protection solutions, signaling sustained attention to North American industrial buyers and specification communities. HELUKABEL participated in multiple international trade shows during the same period to demonstrate its cable glands portfolio and product innovations, reinforcing a market-presence strategy designed to capture cross-regional demand. The Lapp Group presented SKINTOP® cable glands and related products at AUTOMATE 2026 in Chicago, aligning its offerings with automation-focused audiences and underscoring the connection between cable management reliability and industrial control system performance. These visible activities are indicative of a broader pattern: manufacturers are increasingly using trade presence, technical demonstrations, and application-focused messaging to differentiate in a category where specifications and certifications often dominate purchasing decisions.
Regulatory and Technical Compliance: The Hidden Architecture of Demand
Compliance is not a peripheral concern in the cable glands market; it is a core determinant of market access, procurement eligibility, and risk exposure. Recent regulatory developments have sharpened the focus on certification rigor and documented conformity. In October 2025, the CSA issued a Certificate of Compliance for cable glands intended for external connections in Zone 1/Div 2 hazardous locations, reinforcing the importance of region-specific approvals for North American installations. At the same time, cable glands must comply with CAN/CSA-C22.2 No. 60079 series standards for use in explosive environments, a requirement that remains an active and enforceable benchmark for manufacturers serving hazardous-location customers.
Globally, the certification landscape continues to demand alignment with UL, CSA, UR, and ATEX/IECEx standards where applicable, especially for products destined for hazardous locations and safety-critical electrical installations. These certifications influence everything from material selection and production process controls to labeling, documentation, and post-market traceability. For buyers, the presence or absence of recognized certifications can determine whether a product enters the specification sheet at all. For manufacturers, maintaining certification breadth across multiple standards bodies is both a competitive asset and an operational burden, requiring sustained investment in testing, quality systems, and regulatory monitoring. The research study examines how certification portfolios are being used strategically, including where companies are expanding approvals to unlock new geographies, and where regulatory divergence is creating friction in cross-border supply chains.
Tubular Cable Lugs Market
Raw Material and Supply Chain Considerations
In addition to compliance, raw material dynamics remain a structural factor in manufacturing economics. Brass, aluminum, plastic, and nickel-plated steel form the core input base for cable glands, and global price fluctuations directly affect production costs and margin stability. Trade and import-export policies for these materials further influence manufacturing cost structures and supply availability, particularly for producers operating across multiple jurisdictions. Companies that have diversified supplier bases, implemented forward purchasing strategies, or redesigned product lines to accommodate alternative materials are better insulated against cost shocks. The full analysis connects these raw material pressures to segment-level margin behavior, regional sourcing patterns, and the pricing strategies that differentiate resilient competitors from those forced into reactive discounting.
What the Full Research Study Delivers
The complete market research report moves beyond high-level trends to provide operational decision support across multiple planning dimensions. It includes a detailed forecast model spanning the 2026–2032 period, built on a transparent methodology that links historical demand behavior to forward-looking assumptions. The study decomposes market size by region, type, cable construction, material, and end-use industry, allowing executives to test strategic scenarios against the segments most relevant to their portfolios. Competitive profiles extend beyond summary descriptions to evaluate positioning strength, certification coverage, material strategies, and visible market activities that signal near-term momentum.
Beyond market sizing, the report integrates regulatory tracking, raw material cost context, and trade-policy considerations into a unified view of market risk and opportunity. This integrated approach enables users to evaluate questions such as which certifications are becoming table stakes in specific geographies, where material substitution can reduce exposure to volatile inputs, and which competitors are building durable advantages through scale, technical service, or compliance breadth. For corporate strategy teams, the study provides a structured basis for market entry, product line rationalization, supplier negotiation, and M&A screening. For commercial leaders, it offers a clearer map of where specification ownership, channel relationships, and application-based selling can translate into share gains.
Cable Glands Market
How to Use This Intelligence in 2026 Planning
The strategic value of this research lies in its ability to convert broad market movement into focused action. Executives can use the forecast framework to align capacity planning, inventory policy, and procurement timelines with demand trajectories rather than short-term price signals. Product and engineering teams can prioritize certification investments and material decisions based on the segments where compliance and performance differentiation command premium returns. Sales and channel leaders can refine targeting by understanding which end-use industries are generating the most reliable demand growth and which competitive players are most active in those spaces. Procurement and supply chain managers can incorporate raw material and trade-policy context into sourcing decisions, reducing exposure to shocks that often disrupt reactive purchasing models.
The full report is designed to support these decisions with granular segmentation data, company-level benchmarking, and forward-looking scenario analysis that remains grounded in observable market behavior. It does not simply describe growth; it explains where growth is concentrated, why it is concentrated there, and how organizations can respond with disciplined investment rather than generalized optimism.
Conclusion: Positioning for the Next Phase of Market Evolution
The cable glands market is entering a period in which compliance rigor, material cost management, and competitive specialization will matter as much as baseline demand growth. A 6.5 percent CAGR through 2032 signals a meaningful expansion opportunity, but the real strategic challenge is to identify which segments, certifications, materials, and geographies align with an organization’s capabilities and risk tolerance. Market concentration among leading players indicates that scale and certification breadth remain powerful advantages, yet the presence of focused regional and specialty manufacturers demonstrates that targeted engineering and service excellence can still secure strong positioning.
For decision-makers preparing 2026 plans, the difference between reactive participation and strategic leadership will come down to the quality of market intelligence guiding capital, product, and supply chain choices. The full study provides the segmentation detail, competitor context, regulatory mapping, and forecast structure necessary to make those choices with confidence. Organizations that treat cable glands as a safety-critical, specification-driven interface rather than a commoditized fastener category will be better positioned to capture margin, defend share, and expand into the applications where performance requirements are intensifying.
For detailed analysis of this topic, please visit the official page: Cable Glands Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Ultrafiltration Membrane Market to Hit $321.45M by 2032 on 7.45% CAGR
By pmarketresearch, 2026-09-15
Navigating the Next Wave: Strategic Imperatives in the Ultrafiltration Membrane Filtration Market (2026–2032)
The global ultrafiltration (UF) membrane filtration market is entering a decisive phase of expansion, driven by tightening water regulations, industrial process intensification, and the accelerating adoption of membrane-based separation technologies across diverse end-use sectors. As organizations prepare their capital allocation and operational strategies for the 2026–2032 horizon, understanding the structural dynamics of this market has transitioned from a technical consideration to a core strategic imperative. This report delivers a granular, forward-looking assessment of market trajectories, competitive positioning, and technology adoption curves, providing decision-makers with the analytical rigour needed to align investment portfolios with emerging demand signals.
Market Trajectory and Structural Growth Indicators
Over the historical review period (2020–2025), the ultrafiltration membrane filtration market demonstrated resilient, compounding growth, advancing from approximately 152.3 USD Million in 2020 to an estimated 195.4 USD Million by the 2025 base year. This upward trajectory reflects sustained capital expenditure in municipal water infrastructure, industrial wastewater compliance, and process-oriented filtration in food, beverage, and pharmaceutical manufacturing. Looking ahead, the forecast period (2026–2032) projects a steady expansion trajectory, with the market anticipated to reach 213.86 USD Million in 2026 and continue scaling toward 321.45 USD Million by 2032. The implied compound annual growth rate (CAGR) of approximately 7.45 percent underscores a market that is not merely recovering from cyclical fluctuations but is structurally re-rating higher as membrane solutions become embedded in long-term operational planning.
For strategic planners, this growth profile signals more than top-line expansion. It indicates a market where demand is being pulled by regulatory pressure, supply chain resilience priorities, and the ongoing shift toward water reuse and closed-loop industrial processes. The inflection observed between 2023 and 2025, followed by the projected acceleration into the late 2020s, suggests that early-mover organizations that align their R&D, manufacturing capacity, and service networks with these demand curves will be positioned to capture disproportionate value as the market matures.
The 2026–2032 Decision Window: Why Timing Matters
The 2026–2032 forecast window is particularly consequential for enterprise strategy. During this period, several converging forces will reshape procurement cycles, technology selection criteria, and regional deployment priorities. First, the integration of pre-filtration and ultrafiltration into unified module architectures is reducing footprint requirements and capital intensity, making membrane systems viable for a broader set of brownfield and space-constrained installations. Second, biofouling mitigation, pore-size engineering, and material durability are becoming decisive differentiators as operators seek to extend membrane lifecycles and reduce chemical cleaning frequency. Third, stringent discharge limits and water-stressed regional conditions are pushing municipal and industrial buyers toward solutions that combine high removal efficiency with operational reliability under variable feedwater quality.
In this environment, firms that rely on retrospective snapshots or generic market narratives risk misallocating resources. A disciplined, forward-looking analysis enables leadership teams to stress-test investment theses against realistic adoption curves, identify where consolidation or partnership opportunities are likely to emerge, and calibrate product roadmaps to the specifications that end-users will increasingly demand. The strategic value of this report lies precisely in its ability to convert macroeconomic and sector-level signals into actionable planning parameters for procurement, R&D, regional expansion, and competitive positioning.
What This Research Unpacks: From Macro Signals to Operational Intelligence
This study is constructed to serve as a decision-support framework rather than a static market summary. It begins with a rigorous historical reconstruction of market size and growth trends, establishing a credible baseline against which forward projections can be evaluated. From there, the analysis progresses into structured segmentation that examines how demand characteristics diverge across membrane material types, end-use applications, and geographic deployment patterns. Rather than presenting isolated percentages, the report contextualizes each segment within the operational realities that drive purchasing behavior: pore-size requirements, chemical compatibility, cleaning protocols, throughput expectations, and total cost of ownership considerations.
The research also maps the competitive landscape with attention to product architecture, technology roadmaps, and recent commercial moves that signal where incumbents and challengers are placing their bets. By examining product launches, certifications, and flagship contract awards, the analysis reveals how leading players are adapting their portfolios to address footprint constraints, fouling resistance, and application-specific performance thresholds. This competitive intelligence is paired with demand-side insights that clarify how municipal utilities, industrial processors, and life sciences operators are evaluating UF solutions against alternative separation technologies.
Ultrafiltration Membrane Market
Throughout, the report emphasizes practical applicability. Readers will find structured analysis that supports capacity planning, identifies high-growth application pathways, highlights regions where infrastructure investment cycles are accelerating, and flags technology transitions that could reshape procurement specifications over the next several years. The objective is to equip strategy, product, and commercial teams with a shared analytical foundation that can be translated into regional rollout plans, partnership strategies, and portfolio prioritization decisions.
Competitive Landscape: Incumbents, Innovators, and the Shape of the Market
The competitive architecture of the ultrafiltration membrane filtration market reflects a mix of established multinational players, specialized material innovators, and regional manufacturers that are expanding their commercial footprint. With a top-three concentration ratio of 18.75 percent and a top-five concentration of 25.6 percent, the market remains relatively fragmented at the upper tier, leaving meaningful room for differentiation through technology, service integration, and application-specific solutions. This fragmentation is not a sign of immaturity; rather, it indicates a market where performance credentials, regional support networks, and total-cost positioning can decisively influence procurement outcomes.
Several leading companies illustrate the strategic directions currently shaping the market. Toray Industries, Inc., based in Tokyo, has been advancing hollow-fiber UF membrane modules tailored for high-removal wastewater treatment and water reuse, including a next-generation lower-biofouling module with a nominal pore size of 0.005 micrometers. This product direction reflects an industry-wide emphasis on tightening separation performance while reducing fouling-related operational burdens, particularly for reuse and sensitive industrial streams.
Ultrafiltration Membrane Filtration Market
DuPont de Nemours, Inc., headquartered in Wilmington, Delaware, continues to expand its UF portfolio through both established offerings and targeted product launches. Its Inge™ UF modules, including PVDF and PES multi-bore variants with integrated pre-filters, are designed to streamline system architecture and reduce capital footprint. The company also maintains the ZeeWeed™ hollow-fiber UF platform for municipal, industrial, and offshore applications, signaling a strategy that balances standardized high-volume solutions with application-specific configurations.
Veolia Water Technologies & Solutions, headquartered in Paris, reinforces the importance of system-level integration and long-term operational partnerships. Through its UF and UF/RO membrane systems, the company addresses drinking water, wastewater, semiconductor, and offshore injection water production. Recent contract activity, including a multi-year operation award for a large-scale semiconductor water treatment facility, underscores how membrane providers are increasingly rewarded for reliability, recovery performance, and lifecycle service capabilities rather than component pricing alone.
BASF SE, based in Ludwigshafen, Germany, contributes multi-bore PES UF membranes and modules that support drinking water treatment, seawater pretreatment, and desalination optimization. Meanwhile, Cembrane A/S in Aarhus, Denmark, has established itself as a major producer of silicon carbide-based UF membranes for drinking water purification and high-throughput industrial wastewater applications, highlighting the growing relevance of robust inorganic membrane materials in demanding service environments.
The market also includes specialized and regionally focused players that expand the breadth of available solutions. Synder Filtration, Inc., in Vacaville, California, provides custom UF membrane flat sheets and spiral-wound elements for process water, food and beverage, and chemical industry applications. Meissner Filtration Products, Inc., in Carlsbad, California, supplies hollow-fiber PES UF membranes and modules for laboratory, bioprocess, and industrial filtration, reflecting the continued importance of precision filtration in controlled-process environments. Theway Membranes Pvt. Ltd., based in Chennai, India, represents the expansion of domestic manufacturing capability, producing hollow-fiber UF membranes for beer and wine filtration, membrane distillation, and industrial use. Taken together, these players illustrate a competitive field where material science, module design, and application know-how are the primary levers for differentiation.
Deployment Drivers Across Applications and Regions
Demand for ultrafiltration membranes is being shaped by distinct application-level priorities that influence performance requirements, procurement cycles, and service expectations. Water and wastewater treatment remains a central demand driver, as municipalities and industrial operators seek to meet stricter effluent standards, support water reuse initiatives, and improve the reliability of pretreatment trains ahead of downstream processes. In food and beverage processing, UF is increasingly valued for separation steps that must preserve product quality while maintaining consistent yield and operational uptime. Pharmaceutical and biotechnology applications continue to rely on UF for process fluid clarification, buffer preparation, and controlled filtration steps where material compatibility and regulatory documentation are critical. Chemical industry usage favors membranes that can handle variable feed compositions and resist fouling or chemical degradation under repeated cleaning cycles.
Geographically, deployment patterns reflect differences in infrastructure investment cycles, water stress intensity, industrial mix, and regional manufacturing capacity. Some markets are driven by large-scale municipal modernization programs and compliance-led retrofits, while others are expanding through industrial decentralization, beverage and food processing growth, and semiconductor-related water treatment requirements. The interplay between these regional dynamics and application-specific demand creates a complex but navigable landscape for organizations that can align their distribution, technical support, and product specifications with local procurement realities.
Recent commercial activity reinforces the strategic importance of these deployment drivers. Product introductions that unify pre-filtration and UF in a single module are reducing installation footprints and simplifying capital planning for space-constrained sites. Advances in lower-biofouling designs and fine pore-size engineering are attracting attention from operators seeking to extend run lengths and reduce maintenance intensity. In parallel, high-profile certifications and long-duration operation contracts are signaling that end-users increasingly evaluate UF suppliers on proven reliability, recovery performance, and the ability to support complex, multi-year service requirements. Exhibit presence at major industry events further illustrates how vendors are using technical demonstrations and utility-focused presentations to shape specification conversations well before procurement decisions are finalized.
Strategic Takeaways for Leadership Teams
As organizations move from market awareness to concrete planning, several strategic implications emerge from the current landscape. First, technology selection is increasingly governed by total cost of ownership rather than initial module pricing. Decisions around material compatibility, fouling resistance, cleaning frequency, and footprint compression can materially affect operating economics over the life of an installation. Second, the fragmented upper-tier concentration suggests that differentiation through application expertise, regional service coverage, and integrated system design can outweigh scale alone for many buyer segments. Third, the forecast growth trajectory indicates that demand will continue to broaden across both traditional and emerging use cases, making portfolio flexibility and specification agility important capabilities for producers and solution providers alike.
For procurement and operations leaders, the practical priority is to align membrane specifications with realistic operating conditions and lifecycle cost models rather than relying on generalized performance claims. For commercial and strategy teams, the priority is to identify where regional infrastructure cycles, industrial expansion, and regulatory momentum are likely to generate near-term demand clusters, and to position partnerships, distribution, or manufacturing capacity accordingly. For R&D and product organizations, the priority is to track the convergence of material improvements, module architecture changes, and application-specific performance requirements that are redefining what buyers consider a competitive offering.
Access the Full Strategic Assessment
The ultrafiltration membrane filtration market is moving from incremental adoption to structural integration across water, industrial, and process applications. Organizations that base their 2026–2032 planning on a detailed, forward-looking assessment will be better equipped to prioritize investments, refine product and service strategies, and anticipate specification shifts before they become mainstream procurement requirements. This report provides the analytical depth required to support those decisions, combining historical reconstruction, segmented growth analysis, competitive intelligence, and deployment-context insights into a single decision-ready framework.
To explore the complete segmentation analysis, regional deployment patterns, application-level demand drivers, and the full competitive profiling included in the study, access the complete market research on the source page. The full report delivers the granular intelligence needed to translate market momentum into executable strategy for the years ahead.
For detailed analysis of this topic, please visit the official page: Ultrafiltration Membrane Filtration Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com