

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Roadmarking Paints Market Hits $7.18B in 2025, 5.8% CAGR to $10.6B by 2032

Navigating the Next Wave of Growth in the Roadmarking Paints Market
As urban infrastructure expands and regulatory frameworks deepen their focus on safety and sustainability, the roadmarking paints sector stands at a critical inflection point. For executives, procurement leaders, and strategy teams operating across construction, coatings, and public works, understanding the trajectory of this market is no longer optional. It is a prerequisite for capital allocation, product portfolio planning, and long-term competitive positioning. Our latest research study offers a comprehensive, data-driven view of the industry, mapping historical performance, projecting forward momentum, and unpacking the operational realities that will shape corporate decisions through the end of the decade.
This analysis is designed as a strategic preview of what the full report delivers. Rather than providing a superficial overview, it walks through the macro-scale trajectory, the structural forces altering supply and demand, the competitive dynamics among established players, and the practical frameworks our methodology uses to translate market signals into executable intelligence. The goal is to demonstrate the depth of insight available and to show precisely how decision-makers can leverage this research to reduce uncertainty, optimize investment timing, and align product strategies with emerging market realities.
Traffic Marking Paints Market
Macro Trajectory: From Historical Correction to Sustained Expansion
The roadmarking paints market has demonstrated consistent growth over the past half-decade, recovering from early-cycle fluctuations and building momentum as governments and private developers prioritize road safety, lane visibility, and infrastructure modernization. Historical data from 2020 through 2025 reveals a steady upward path, with the total market expanding from approximately 5.52 billion USD to an estimated 7.18 billion USD. This progression reflects not only renewed public spending on transportation networks but also a gradual shift toward higher-performance marking solutions that offer improved durability, retroreflectivity, and environmental compliance.
Looking ahead, the forecast period from 2026 through 2032 projects continued expansion, with the market expected to surpass the 10 billion USD threshold and reach a valuation near 10.6 billion USD by the close of the forecast window. The implied compound annual growth rate across this horizon stands at 5.8 percent, a pace that signals durable demand rather than a temporary cyclical spike. This trajectory is underpinned by widening application footprints, ongoing replacements of worn or faded markings, and the gradual adoption of advanced formulation technologies that extend service life and reduce lifecycle maintenance costs.
What makes this growth profile strategically significant is its consistency across varying economic conditions. While raw material pricing fluctuations and regulatory adjustments introduce short-term volatility, the underlying demand drivers remain anchored in infrastructure renewal cycles, urbanization trends, and the need for standardized, high-visibility road markings that meet increasingly rigorous safety specifications. Organizations that understand where growth concentrates, which product categories are gaining share, and how regional procurement rhythms differ will be better positioned to time capacity expansions, pricing strategies, and distribution partnerships.
Regulatory Pressures, Raw Material Volatility, and the Shifting Value Chain
No strategic assessment of this market is complete without addressing the operational pressures that are reshaping cost structures and influencing purchasing behavior. One of the most persistent challenges in recent quarters has been raw material cost volatility. Resin suppliers, thermoplastic compound producers, and specialty glass bead manufacturers have experienced uneven pricing dynamics, creating margin pressure for formulators and coating manufacturers. This instability is especially pronounced for soda lime glass and specialty chemical coatings, where supply chain sensitivity and regional sourcing constraints can quickly alter input economics. For budget-constrained infrastructure projects, these cost pressures can slow adoption of premium marking systems or push buyers toward lower-cost alternatives that may compromise durability or reflectivity.
At the same time, regulatory standards are tightening across multiple jurisdictions. Environmental regulations concerning VOC emissions and broader ecological impact continue to influence formulation choices, accelerating the transition away from solvent-heavy products in favor of waterborne and low-emission alternatives. Compliance requirements are not merely a constraint; they are increasingly a competitive differentiator. Manufacturers that can deliver high-performance markings while meeting emission thresholds and sustainability expectations gain preferential access to public tenders, municipal contracts, and specification-driven projects.
Recent specification updates also illustrate how technical standards are evolving. Revisions to ready-mixed paint specifications for road marking, such as the updated IS 164 framework, introduce new performance and quality expectations that affect both product development and procurement criteria. For suppliers, alignment with updated standards is essential to maintain eligibility in key bidding environments. For buyers, these changes create a clearer benchmark for evaluating consistency, adhesion, weather resistance, and retroreflective performance. The interplay between raw material dynamics and regulatory evolution means that market participants must monitor both cost-side and compliance-side variables simultaneously, a complexity that our study maps in detail across multiple operational dimensions.
What the Report Covers: A Practical Blueprint for Decision-Makers
The full research study is built to move beyond headline figures and equip teams with actionable frameworks. It begins with a rigorous sizing and forecasting model that traces market development from historical baselines through the full forecast horizon. Rather than relying on aggregate figures alone, the analysis disaggregates demand across product types, application settings, and geographic markets, enabling readers to identify where growth is accelerating, which segments are maturing, and how share shifts are unfolding among competing technologies.
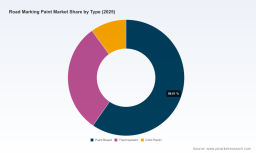
A central component of the study is its segmentation architecture. The report examines the market across paint-based, thermoplastic, and cold plastic categories, evaluating the distinct performance profiles, installation requirements, and cost dynamics associated with each. It also explores application environments ranging from roads and highways to parking lots and airports, highlighting how usage intensity, traffic patterns, and specification requirements drive differentiated demand. This segmentation lens allows strategists to assess which product categories are best aligned with specific end-use priorities and to anticipate where substitution trends or technology upgrades may alter purchasing patterns.
Beyond segmentation, the study provides a detailed competitive landscape assessment. It profiles leading participants, examines their product positioning, and evaluates the strategic implications of their offerings in the roadmarking paints space. The analysis considers how companies differentiate through formulation technology, regional compliance readiness, application specialization, and service capabilities. It also explores concentration patterns, identifying how market share is distributed among major players and what that implies for pricing power, partnership opportunities, and entry barriers.
Operational and strategic depth is further reinforced through a structured examination of market dynamics. The report analyzes supply-side constraints, procurement behavior, regulatory impact, and the ways in which raw material and compliance pressures interact to shape margin structures and competitive positioning. This section is designed to help teams translate external market signals into internal planning assumptions, whether for production scheduling, inventory strategy, pricing architecture, or long-range capacity planning.
Competitive Landscape: Strategic Positioning Among Leading Players
The competitive environment in roadmarking paints is defined by a mix of global coatings multinationals and specialized regional suppliers, each pursuing distinct value propositions within a market that rewards both technical performance and specification alignment. Several established companies illustrate the breadth of strategic approaches currently shaping the industry.
PPG Industries, headquartered in Pittsburgh, Pennsylvania, brings a well-recognized portfolio through its ENNIS-FLINT family of waterborne and solvent-based traffic paints. Its offering reflects a focus on formulation versatility and alignment with diverse application requirements, enabling customers to select products that match local specification expectations, environmental constraints, and performance targets. For organizations evaluating supplier partnerships, PPG's positioning underscores the importance of product breadth and the ability to serve multiple marking environments with consistent quality.
Swarco, with headquarters in Austria and global operations, represents a broader systems-oriented approach. Its road marking portfolio spans solvent-based paints, waterborne paints, and two-component systems, reflecting a strategy centered on optionality and technical adaptability. This multi-formulation model allows Swarco to address varying procurement preferences and regulatory environments across different markets. In a sector where local compliance and application conditions can differ sharply from one region to another, such flexibility is a meaningful competitive advantage.
Meon Ltd, based in the United Kingdom, focuses on line marking paints and cold plastic systems for roads, parking lots, and airports. Its product scope highlights the value of serving multiple application environments with specialized formulations that balance durability, application efficiency, and visibility performance. By concentrating on end-use versatility, Meon illustrates how suppliers can capture demand across both high-traffic transportation corridors and structured facilities where marking precision and longevity are critical.
Roadmarking Paints Market
Axalta Coating Systems, operating globally from Belgium, contributes a portfolio that includes spirit-soluble and modified alkyd formulations for road line marking. Its presence in the market reflects the continued relevance of established coating chemistries alongside newer waterborne and low-emission alternatives. This breadth demonstrates how legacy formulation expertise can coexist with evolving compliance demands, particularly in markets where specification transitions are gradual and where buyers still value proven performance characteristics.
Cloverdale Paint Inc, headquartered in Alberta, Canada, emphasizes waterborne traffic paint formulations approved for use in Canadian infrastructure specifications. Its regional alignment illustrates the importance of specification certification and local compliance readiness in public-sector procurement. In markets where bidding eligibility depends on meeting recognized technical standards, suppliers with approved formulations can secure a defensible position even in the face of broader raw material or pricing pressures.
Together, these profiles reveal a competitive arena where differentiation is increasingly tied to formulation adaptability, regulatory readiness, and application-specific reliability. The full report builds on these company-level insights to map share structures, evaluate positioning strategies, and identify where consolidation, partnership, or product innovation is most likely to reshape competitive dynamics.
Strategic Implications for Corporate Planning in 2026 and Beyond
The strategic significance of the roadmarking paints market lies in the intersection of durable demand and evolving operational constraints. Growth is not simply a function of infrastructure spending; it is increasingly shaped by formulation shifts, compliance requirements, and cost-side pressures that influence which products win specification approvals and repeat contracts. For manufacturers, this environment rewards early investment in waterborne and low-emission technologies, disciplined raw material procurement strategies, and close alignment with the specification calendars of public and private buyers. For distributors and applicators, understanding regional demand rhythms and the relative performance economics of paint-based, thermoplastic, and cold plastic systems can improve bidding accuracy and service positioning.
For investors and corporate development teams, the concentration pattern in the market suggests that scale, specification access, and regulatory compliance capabilities remain important barriers. At the same time, the diversity of application environments and product types creates room for specialized suppliers to compete effectively in selected niches. The challenge is to distinguish between short-term pricing noise and structural shifts in demand, a task that requires granular segmentation data, forward-looking scenario analysis, and a clear view of how regulatory updates will alter procurement eligibility over time.
The forecast horizon through 2032 offers a valuable planning window. Organizations that use this period to align product development, capacity strategy, and partnership models with the market's underlying growth path will be better prepared to capture share as older markings are replaced, as new infrastructure projects advance, and as specification standards continue to evolve. The report provides the analytical scaffolding needed to make those decisions with greater confidence, translating market projections into practical strategic options.
From Insight to Action: Why the Full Report Matters
A strategic preview can highlight direction, but the full study is where depth becomes decision-ready intelligence. The complete report brings together historical sizing, forward forecasts, segmentation analysis, competitive profiling, and dynamic market assessment in a single integrated framework. It is designed to support multiple internal use cases: executive briefings, product strategy reviews, procurement planning, market entry evaluations, and investment prioritization. By consolidating both macro trends and operational realities, the study helps teams move from awareness to action without having to reconstruct the analysis from disparate sources.
The report also addresses the practical challenge of navigating uncertainty. Raw material volatility, regulatory updates, and shifting application preferences all introduce variables that can complicate planning. By mapping these forces explicitly and linking them to segmentation behavior and competitive response, the research provides a clearer lens for scenario planning and risk assessment. Readers gain not just a view of what the market is doing, but a structured understanding of why it is moving that way and what that implies for different business functions.
For organizations seeking to stay ahead of specification changes, align product portfolios with emerging demand, and evaluate competitive positioning with greater precision, the full study offers the level of detail required to support high-stakes decisions. The macro trajectory sets the stage, the segmentation and competitive analyses sharpen the focus, and the dynamics section connects external pressures to internal strategy. Together, these components create a comprehensive foundation for planning in a market where performance, compliance, and cost management must be balanced at every step.
The roadmarking paints market is entering a phase in which growth, regulation, and competitive differentiation will increasingly reinforce one another. Companies that approach this environment with rigorous data, clear segmentation insight, and a realistic view of cost and compliance pressures will be best positioned to convert market expansion into durable advantage. This research study is built to provide exactly that strategic clarity, and the full report delivers the depth needed to turn market intelligence into executable planning.
For detailed analysis of this topic, please visit the official page: Roadmarking Paints Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com