

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Laminator Market Hits $489M in 2025, Poised for 7.25% CAGR Through 2032

Strategic Intelligence for the Laminating Machinery Sector: Navigating Growth, Segmentation, and Competitive Dynamics in 2026
The global laminator market stands at a critical inflection point. As enterprises across packaging, printing, and commercial production recalibrate their capital allocation strategies, the ability to distinguish between transient demand spikes and structural growth drivers has never been more consequential. This analysis, drawn from our latest Laminator Market research, is designed to equip strategic decision-makers with the contextual clarity required to navigate a landscape defined by technological differentiation, regional reconfiguration, and compounding macroeconomic pressures. The following overview outlines the market architecture, competitive contours, and operational imperatives that will shape procurement, investment, and portfolio decisions through 2032.
Laminating Machine Market
Market Trajectory: Historical Momentum and the 2026–2032 Forecast Horizon
Tracing the revenue curve from 2020 through the base year of 2025 reveals a market that has consistently outpaced broader industrial equipment benchmarks. Total market value expanded from 347.0 million USD in 2020 to 489.0 million USD by 2025, reflecting a compound annual growth trajectory that underscores sustained commercial adoption rather than cyclical rebound. The momentum extends well into the forecast period: projected revenue crosses the 535.82 million USD threshold in 2026 and continues ascending toward 798.0 million USD by 2032, supported by a forecast-period CAGR of 7.25 percent.
For enterprise strategists, this trajectory carries several implications. First, the growth is broad-based enough to suggest that laminators are transitioning from niche auxiliary equipment to integrated production infrastructure in multiple downstream verticals. Second, the acceleration pattern indicates that early-mover commitments to advanced lamination capacity are likely to capture disproportionate share in packaging and commercial printing workflows where throughput and material protection requirements are intensifying. Third, the forecast window provides a sufficiently long runway for organizations to align equipment roadmaps with multi-year capacity expansion plans rather than reacting to short-term supply constraints.
Importantly, the macro trajectory does not distribute evenly across commercial realities. The market's composition reflects distinct operational profiles, with automatic and semi-automatic configurations dominating revenue pools, manual units sustaining steady demand in institutional and light-commercial settings, and industrial-grade systems anchoring high-specification packaging and specialty coating applications. This structural split dictates that procurement strategies cannot rely on homogenized specifications; instead, they must align machine capability with workflow intensity, material chemistry, and downstream compliance requirements.
Segmentation Architecture: Decoding Demand Drivers Without Overgeneralization
Effective market positioning requires a granular understanding of how value migrates across machine categories, application verticals, and geographic corridors. Our research decomposes these dimensions to reveal where procurement budgets are concentrating and where addressable gaps remain underserved.
Laminator Market
Within the equipment taxonomy, thermal pouch and roll-based configurations continue to anchor office, educational, and light commercial print environments, while reel-to-reel and reel-to-sheet platforms drive commercial graphics enhancement, thin and thick film encapsulation, and protective coating workflows. Industrial and solventless lamination systems occupy a specialized but high-value tier, serving flexible packaging, food and pharmaceutical-grade applications, and integrated print-laminate-slitting lines. The divergence in operational economics across these categories means that total cost of ownership calculations must incorporate film chemistry compatibility, curing technology requirements, maintenance cycles, and throughput variability rather than relying solely on acquisition price.
On the application side, packaging remains the dominant revenue anchor, reflecting the sector's relentless demand for moisture barrier performance, shelf-life extension, substrate durability, and aesthetic finishing. Printing and commercial graphics applications constitute a secondary but strategically important pool, where lamination serves both protective and decorative functions, including foil integration, embossing compatibility, and UV-cured surface enhancement. Office and adjacent institutional use cases maintain a stable baseline, driven by document preservation, signage production, and small-batch commercial output. Each application vertical carries distinct material sensitivity profiles; for example, packaging workflows are particularly exposed to raw material cost volatility for laminating films such as polypropylene and polyester, while adhesive pricing tied to oil-based inputs can suppress margin flexibility in flexible packaging lines.
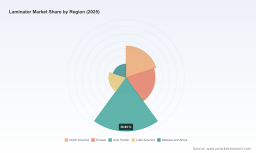
Geographically, the market exhibits a multi-polar distribution with pronounced regional specialization. Asia Pacific commands the largest revenue share, reflecting concentrated packaging production capacity, expanding commercial printing ecosystems, and rapid adoption of automated lamination lines. North America and Europe sustain robust demand grounded in mature print service infrastructure, regulatory-driven material compliance, and ongoing upgrades to industrial coating and laminating platforms. Latin America and the Middle East and Africa represent growth corridors where infrastructure maturation, import substitution trends, and localized production incentives are gradually reshaping procurement patterns. Organizations evaluating market entry, capacity relocation, or partner selection must therefore treat regional analysis as a dynamic variable rather than a static ranking.
Competitive Landscape: Strategic Postures of Leading Players
The laminator market is characterized by moderate concentration, with the top three players accounting for approximately 26.5 percent of revenue and the top five collectively capturing around 30.1 percent. This structure signals a market where incumbents hold meaningful positional advantage but where specialization, regional reach, and technology differentiation remain viable pathways for competitive traction.
Several companies illustrate the strategic diversity shaping the sector. GBC maintains a strong presence in office and print shop thermal pouch and roll laminators, with product lines such as the LamPrix 100 and Catena series tailored to schools, offices, and small commercial production environments. Autobond focuses on print enhancement lamination machines, thin and thick film encapsulators, and reel-to-reel and reel-to-sheet systems designed for commercial printing and graphics protection. Cellcoat Systems operates at the intersection of thermal lamination and coating machinery, emphasizing roll-to-roll and bespoke applications across packaging and graphic arts.
On the industrial and packaging side, Uteco Converting S.p.a. deploys solventless and multi-technology coaters and laminators, including PrismaLG, DuaLam, and Mistral platforms, targeting flexible packaging and food and pharmaceutical applications. Lamina System AB addresses sheet-to-sheet laminating, mounting, and gluing workflows for printing, corrugated, and folding carton industries. In China, Sunkia Machinery advances automatic thermal film and roll-to-roll lamination machines with patented multi-function systems and ISO/CE certification, positioning itself for international deployment. Wenzhou Guowei Printing Machinery integrates gravure printing and laminating machines with slitting for complete packaging lines, while Wenzhou Feihua Printing Machinery offers automatic and semi-auto laminating machines with UV coating options and embossing capabilities for packaging and printing. Chongqing Sinstar Packaging Machinery concentrates on solventless lamination machines for flexible packaging, including upgraded SUPLOCK solutions.
Recent corporate activity reinforces the market's innovation cadence. In October 2025, 3M Company recalled its Scotch Thermal Laminator model TL909-50 due to overheating hazards affecting approximately 13,440 units, prompting refunds and broader safety compliance reviews across thermal laminator categories. The same period saw Advanced Greig Laminators, Inc. introduce the AGL 80 industrial laminating machine for foam and gasket applications, incorporating UV and UV LED curing technologies. Momentum carried into 2026, with Skandacor showcasing the LAMpro Cheetah S15M versatile laminator capable of both lamination and digital foil processing at C!Print 2026, and Jialite demonstrating the NFY-S540 Automatic Film Laminating Machine live at DPRINT SOUTH 2026. These developments highlight a sector where safety compliance, curing technology integration, multi-function versatility, and live demonstration-driven commercialization are increasingly intertwined.
Market Dynamics: Restraints, Catalysts, and Procurement-Relevant Risks
Strategic planning in this market cannot isolate equipment specifications from the environmental and operational forces that shape adoption. Raw material volatility remains a recurring constraint, particularly for laminating films including polypropylene and polyester, where price instability limits development potential in packaging applications and compresses margin flexibility. Adhesive pricing tied to oil-based inputs introduces additional friction, especially for flexible packaging workflows where solventless and lamination adhesive economics directly influence line profitability. High manufacturing costs and volatile raw material conditions are frequently cited as key restraints limiting the broader expansion of thermal lamination film adoption, reinforcing the case for long-term supply agreements, material substitution evaluation, and lifecycle cost modeling.
Regulatory and safety dynamics add another layer of complexity. The October 2025 CPSC recall of 3M Scotch thermal laminators due to overheating and burn hazards triggered safety compliance reviews and reminded procurement teams that thermal-based equipment must be evaluated not only for throughput and finish quality but also for thermal management reliability, certification status, and post-market support responsiveness. At the same time, companies such as Sunkia Machinery have emphasized ISO and CE certifications for international deployment, signaling that compliance readiness is becoming a competitive differentiator in cross-border sales and integrator partnerships.
Infrastructure and cost considerations further shape adoption curves. High manufacturing costs and material volatility can slow the rollout of advanced thermal lamination film solutions, particularly in price-sensitive segments where buyers prioritize immediate cost control over long-term performance gains. Conversely, regions and verticals with stronger capital availability, tighter quality requirements, and integrated production line strategies are better positioned to absorb upfront investment in exchange for throughput stability, material protection, and reduced rework.
Strategic Imperatives for 2026 Decision-Making
As organizations map their laminator procurement and capacity strategies for 2026 and beyond, several decision frameworks emerge from the market structure:
- Align machine selection with workflow intensity rather than uniform specifications. Automatic, manual, and industrial configurations serve distinct throughput, material, and compliance requirements, and procurement misalignment can generate hidden operating costs.
- Integrate raw material exposure into total cost of ownership models. Film chemistry, adhesive pricing, and curing technology requirements influence both acquisition decisions and multi-year operating economics, particularly in packaging and flexible packaging applications.
- Treat safety compliance and certification status as procurement gate criteria. Thermal management reliability, recall risk awareness, and international certification readiness should inform vendor evaluation alongside technical performance.
- Assess regional demand architecture when planning capacity, partnerships, or market entry. Revenue distribution across North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa reflects different production ecosystems, regulatory environments, and adoption maturities.
- Monitor competitive activity through a technology-integration lens. UV and UV LED curing, multi-function lamination and foil processing, solventless systems, and integrated print-laminate-slitting lines are reshaping value propositions across commercial printing and packaging.
What the Full Study Delivers
This market research extends well beyond headline revenue figures and broad segmentation labels. It provides an operational intelligence framework designed for procurement leads, capital planners, competitive intelligence teams, and market entry strategists. The full study maps machine-type revenue distribution, application-level demand concentration, and regional revenue splits with the precision required to support scenario planning and vendor benchmarking. It profiles core companies with operational context, recent product and compliance developments, and strategic posture analysis. It further examines market concentration dynamics, raw material and regulatory pressures, and the interplay between manufacturing costs and adoption feasibility across thermal, solventless, and industrial lamination categories.
For decision-makers seeking to convert market momentum into disciplined capital allocation, the complete report delivers the segmented intelligence, competitive mapping, and dynamic risk assessment necessary to act with confidence. To access the full dataset, company profiles, segmentation breakdowns, and forecast architecture, visit the Laminator Market research page and secure the complete intelligence package.
For detailed analysis of this topic, please visit the official page: Laminator Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com