

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: FOS Market to Hit $440 Million by 2032 at 8.25% CAGR

The Prebiotic Pivot: Why the Fructooligosaccharide Market Demands Strategic Attention in 2026
The global food and nutrition industry is currently navigating a structural transformation where functional benefit is no longer a differentiator but a baseline expectation. Within this landscape, Fructooligosaccharide (FOS) has emerged as a critical ingredient bridging the gap between sugar reduction mandates, gut health trends, and regulatory compliance in sensitive categories like infant nutrition. As we move into 2026, the velocity of this market expansion is accelerating, driven by converging consumer demands and sophisticated supply chain adaptations.
This article serves as a strategic preview to the latest comprehensive market research published by PW Consulting. Our analysis is designed to equip executives, R&D directors, and investors with the macro-level intelligence necessary to navigate the 2026-2032 forecast period. While specific granular data points require the full report, the macro trajectory and competitive dynamics outlined below underscore the urgent need for data-backed decision-making in this sector.
A Trajectory of Resilient Growth: The 2026 Outlook
The financial momentum behind Fructooligosaccharides is not merely cyclical; it is structural. Based on our analysis of historical performance from 2020 through 2025, the market has demonstrated remarkable resilience even amidst raw material volatility. The market size, valued in millions of USD, has climbed steadily, reflecting a compound annual growth rate (CAGR) of 8.25% projected through 2032.
For strategic planners, this growth rate signals more than just revenue expansion. It indicates a deepening penetration of FOS across diverse value chains. The baseline year of 2025 establishes a new equilibrium, setting the stage for a forecast period where the market is expected to reach significant valuation milestones by the early 2030s. This growth is underpinned by a shift from niche health stores to mainstream food and beverage formulations, driven by the dual pressures of clean label initiatives and functional health claims.
However, interpreting these top-line figures requires nuance. The aggregate market size masks varying growth velocities across different forms and applications. Understanding which segments are driving the bulk of this value expansion versus which are stabilizing is crucial for capital allocation. Our full report dissects these streams without revealing the specific percentages in this summary, ensuring that stakeholders understand the magnitude of opportunity while reserving the precise market share data for the confidential intelligence package.
Competitive Landscape: Consolidation and Innovation
The Fructooligosaccharide market is characterized by a moderately concentrated competitive environment. With the top three players holding a combined market share that reflects significant influence and the top five controlling a majority of the landscape, barriers to entry remain non-trivial. This concentration suggests that supply security and regulatory approvals are key leverage points for the incumbents.
Several key enterprises define the current operational standards and innovation pace within this sector. Beneo GmbH, headquartered in Germany, continues to be a pivotal player, particularly with its Beneo-scL85 short-chain FOS which is integral to sugar reduction strategies and infant nutrition. Their European production facilities provide a logistical advantage for serving the high-regulation markets of the West.
Simultaneously, Meiji Holdings Co., Ltd. from Japan represents the strength of the Asian market and branded ingredient solutions. Their Actilight and Meioligo brands have set benchmarks in functional foods and supplements. Recently, Meiji demonstrated the application potential of FOS by launching a functional chocolate line in July 2024, utilizing FOS to achieve significant sugar reduction while maintaining gut health benefits. This move highlights the trend of FOS migrating from health-specific products into indulgence categories.
On the global supply side, giants like Cargill and Ingredion maintain broad portfolios that ensure availability across infant formula, dietary supplements, and functional beverages. Ingredion's focus on GRAS-supported formulations and multiple product grades allows for flexibility in customer formulation. Tate & Lyle PLC has also been active, particularly regarding regulatory clearance. In March 2025, Tate & Lyle filed a GRAS notice for short-chain FOS for use in infant products and conventional food and beverage categories, with safety data reviewed up to February 2025. This regulatory step is critical as it expands the viable application space for their enzymatic short-chain FOS (scFOS).
Other notable contributors include Galam Group, which has highlighted clinical research on their GOFOS™ FOS stimulating GLP-1 hormone levels for metabolic health, and COSUCRA Groupe Warcoing SA, which continues to supply chicory-derived FOS. Roquette Frères and Quantum Hi-Tech (China) Biological Co., Ltd. round out the landscape, with the latter focusing heavily on Asian market needs and prebiotic oligosaccharides for food, feed, and supplements.
Strategic Implications of Recent Developments
The recent activities of these companies point to three major strategic themes. First, regulatory fortification is accelerating; the GRAS notifications and EU approvals since 1999 for baby formula create a safer environment for large-scale adoption. Second, product innovation is shifting towards metabolic health, evidenced by the clinical highlights regarding GLP-1 stimulation. Third, capacity investments are being made to handle sugar reduction demands, as seen in Beneo's 2024 production capacity expansions.
Market Dynamics: Regulatory and Cost Headwinds
While the growth narrative is positive, the operational environment is fraught with complexities that require sophisticated risk management. Regulatory compliance remains the primary gatekeeper for market access, particularly in sensitive categories. For instance, FOS maintains GRAS status for use in infant formula at specific limits—up to 400 mg/100 ml in starter formula and 500 mg/100 ml in follow-on formula as consumed. These limits, documented in FDA GRAS Notice GRN 537 from February 2015, dictate formulation constraints that companies must adhere to strictly.
Fructooligosaccharide (FOS) Market
In the European Union, FOS has been approved for addition in restricted amounts to baby formula and follow-on formula sold since 1999, establishing a long-standing precedent there. Meanwhile, in Canada, FOS is permitted as a medicinal and non-medicinal ingredient in Natural Health Products. These varying regional requirements create a fragmented compliance landscape that increases the cost of market entry for new players and rewards incumbents with established regulatory dossiers.
Supply chain stability presents another layer of challenge. High production costs and seasonal fluctuations in chicory root supply continue to challenge the scaling of inulin-derived FOS. This volatility impacts pricing strategies and margin protection across the value chain. Companies that rely on a single source of raw material face heightened risk compared to those with diversified sourcing strategies or enzymatic production capabilities that bypass some agricultural dependencies.
Furthermore, the distinction between powder and liquid forms adds another dimension to logistics and formulation. While specific market split data is reserved for the full report, it is evident that the choice of form influences distribution channels and end-user acceptance, particularly in liquid versus solid food applications.
Strategic Value of the 2026-2032 Forecast Report
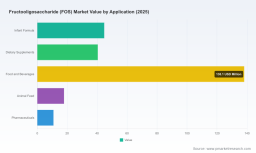
For decision-makers, the value of this comprehensive study lies in its ability to translate high-level trends into actionable intelligence. The market is not growing uniformly; certain applications are leveraging the prebiotic boom more aggressively than others. The food and beverages category, alongside infant formula and dietary supplements, represents a substantial portion of the demand drivers, but the dynamics within each segment differ radically in terms of margin structure and regulatory hurdle rates.
Our report provides a deep dive into these segmentations. It analyzes the form preferences that are gaining traction in specific regions without disclosing the exact regional revenue splits here. This allows you to understand where the liquidity is flowing—whether towards powder forms favored in supplements or liquid forms suited for beverages—without relying on assumptions.
The competitive analysis section goes beyond listing major players. It evaluates their strategic positioning, capacity expansions, and recent moves such as the product launches by Meiji in 2024 and capacity strengthening by Beneo. Understanding who is filing for new GRAS notifications, like Tate & Lyle in March 2025, versus who is focusing on clinical research like Galam Group, allows companies to anticipate competitor moves in their own product roadmaps.
Additionally, the report addresses the production cost dynamics head-on. By contextualizing the chicory root supply fluctuations against the backdrop of growing demand, we provide a framework for assessing supplier viability and long-term contract negotiations. The market concentration data reveals how much power suppliers hold versus buyers, informing procurement strategies for the next five to seven years.
Conclusion: Navigating the Next Horizon
The Fructooligosaccharide market in 2026 is at an inflection point. The convergence of regulatory clarity, consumer awareness regarding gut health, and the industry-wide push for sugar reduction creates a fertile ground for expansion. However, the path to capturing value in this 8.25% CAGR environment requires more than just general optimism. It demands granular insight into segmentation strengths, regulatory boundaries, and competitive moats.
The data presented in this overview highlights the scale and direction of the opportunity. From the historical recovery post-2022 to the robust forecasts leading to 2032, the trajectory is clear. Yet, the specific regional allocations, the precise value of each application segment, and the detailed comparative financial strengths of the key players remain part of the confidential depth of our full market research publication.
For organizations looking to secure their supply chains, formulate new products, or identify M&A opportunities within the prebiotic sector, relying on aggregated data is insufficient. The nuances of GRAS approvals, the impact of chicory root seasonality on specific regions, and the shifting preferences between short-chain and longer-chain variations require the detailed scrutiny provided in the PW Consulting Fructooligosaccharide Market Report. We invite stakeholders to engage with the full dataset to transform these industry insights into concrete strategic advantage.
Worldwide Short Chain Fructooligosaccharides Market
For detailed analysis of this topic, please visit the official page: Fructooligosaccharide (FOS) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com