

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Metallocene Catalyst Market Hits $302.45M in 2025,CAGR 6.85% Forecast to 2032

Strategic Horizon: Why Metallocene Catalyst Intelligence Defines 2026 Decision-Making
The global metallocene catalyst industry stands at a pivotal inflection point. As we transition into the forecast horizon of 2026 through 2032, the market is projected to expand from a 2026 baseline to a substantial 2032 valuation, reflecting a compound annual growth rate of 6.85%. This trajectory is not merely a statistical projection; it represents a structural recalibration of polyolefin manufacturing, driven by precision chemistry, evolving regulatory mandates, and shifting raw material economics. Our newly released market research study dissects this evolution with granular rigor, delivering an actionable intelligence framework designed specifically for executive decision-makers navigating capital allocation, product portfolio optimization, and competitive positioning in the coming decade.
For industry leaders, 2026 is not simply another planning cycle. It is a year where feedstock cost volatility, regional capacity expansions, and sustainability-driven specification shifts will converge to redefine margin structures and technology adoption curves. The metallocene catalyst segment, historically positioned as a premium alternative to conventional polymerization systems, is now experiencing accelerated commercial validation across high-performance film, specialty packaging, and advanced polyolefin grades. Understanding where value pools are forming, which technological architectures are gaining commercial traction, and how competitive players are structuring their go-to-market strategies requires more than high-level industry commentary. It demands a systematically constructed analytical scaffold that maps historical performance, forward-looking consumption patterns, and strategic inflection points onto executable business intelligence.
This research publication has been engineered to serve as that scaffold. By integrating a decade of historical performance data alongside a seven-year forward projection, the study captures both the stabilizing forces and the disruptive currents reshaping the catalyst landscape. The narrative that follows outlines the structural components of the report, highlights the competitive architecture defining the sector, and contextualizes the macroeconomic and regulatory currents that will dictate pricing dynamics, capacity utilization, and technology selection through 2032.
Decoding the Growth Trajectory: From Historical Momentum to Forward Outlook
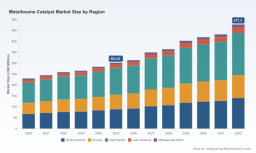
The market's historical arc from 2020 through 2025 establishes a clear foundation of sustained expansion. Revenue progression over this period demonstrates consistent upward momentum, reflecting the gradual but decisive penetration of metallocene-enabled polymer grades into mainstream industrial applications. By 2025, the market had consolidated its position at a meaningful valuation, setting the stage for an accelerated deployment phase in the forecast window. The projected growth curve through 2032 indicates a market that will not only maintain its expansion tempo but will also experience structural shifts in consumption geography, product architecture preference, and end-use specification requirements.
A compound annual growth rate of 6.85% signals more than steady demand; it reflects a compounding effect of technology adoption, downstream converter requirements for thinner-gauge and higher-performance films, and the ongoing substitution of conventional catalyst platforms in targeted high-margin applications. This growth rate is particularly significant given the premium positioning of metallocene chemistry and the inherent cost differentials that have historically constrained broader adoption. As manufacturing scale improves, process integration deepens, and downstream demand for precision polymer architecture intensifies, the economic equation surrounding metallocene catalyst deployment continues to realign.
Metallocene Catalyst Market
Report Architecture: What Decision-Makers Will Find Inside
Our market research publication has been structured to translate complex market signals into executable strategic insight. Rather than presenting static figures in isolation, the study constructs a multi-dimensional analytical framework that enables leadership teams to evaluate opportunity, assess risk, and benchmark competitive positioning with precision. The report encompasses the following core components:
- Historical Baseline and Forward Projection Modeling : A comprehensive dataset tracing revenue evolution across the historical observation window and extending through the full forecast horizon, allowing stakeholders to stress-test growth assumptions and map capacity planning against projected demand curves.
- Technology Segmentation Analysis : A detailed examination of catalyst architecture classifications, including standard metallocene configurations and dinuclear formulations, with emphasis on performance differentiation, process compatibility, and application-specific performance profiles.
- Application-Driven Consumption Mapping : An exploration of how metallocene catalysts are distributed across polymer production pathways, including polyethylene, polypropylene, broader polyolefin manufacturing, and specialized industrial uses, highlighting where performance premiums justify technology investment.
- Competitive Landscape Profiling : Company-level assessments of leading catalyst producers and integrated polymer players, capturing product portfolio strategies, regional manufacturing footprints, partnership ecosystems, and recent commercial developments that signal future market directionality.
- Market Concentration and Structural Dynamics : Analytical perspective on industry consolidation patterns, competitive intensity, and the strategic implications of concentrated market share among top-tier participants.
- Regulatory and Raw Material Context Integration : A synthesized view of environmental compliance trajectories, packaging mandates, feedstock cost movements, and price transmission mechanisms that will influence catalyst economics and downstream adoption velocity.
Each section is designed to operate independently as a reference module while functioning cohesively as an integrated strategic dashboard. Executive teams can extract standalone insights for functional planning or leverage the full architecture for enterprise-level scenario modeling and investment prioritization.
Competitive Architecture: Key Players and Strategic Positioning
The competitive landscape is defined by a cohort of technology-focused catalyst producers, integrated chemical manufacturers, and regional specialty players, each pursuing distinct go-to-market strategies and innovation roadmaps. Leadership in this space is not solely determined by scale; it is increasingly shaped by catalytic precision, process compatibility, customer-specific formulation capabilities, and the ability to align catalyst performance with downstream polymer grade requirements.
Among the prominent participants shaping the market's trajectory are Univation Technologies, W.R. Grace and Company, LyondellBasell Industries, Nouryon, Mitsui Chemicals, Ube Industries, Prime Polymer, Zibo Xinsu Chemical, Chevron Phillips Chemical, Daelim Industrial, SK Chemicals, and Mitsubishi Chemical. These firms operate across North America, Europe, and Asia, with product portfolios spanning gas-phase single-site catalyst systems, custom-synthesized metallocene architectures, specialty polyolefin catalyst formulations, and ligands engineered for activation and performance optimization. Their strategic differentiators range from proprietary process integration and high-extrusion-rate film architectures to custom manufacturing capabilities for complex organic intermediates and single-site catalyst activation systems.
Recent commercial events underscore the accelerating pace of technology selection and grade innovation. In September 2024, Indian Oil Corporation Ltd. selected Univation Technologies' UNIPOL PE Process integrated with metallocene catalyst technology for a world-scale polyethylene production line at Paradip, India, signaling robust demand for single-site catalyst deployment in large-capacity Asian manufacturing projects. Shortly thereafter, in October 2024, TotalEnergies SE launched a new metallocene polyethylene grade, Advanced Supertough 12AST05, targeting film and packaging applications with enhanced performance characteristics. These developments illustrate how catalyst architecture, process selection, and downstream grade innovation are converging to create differentiated value propositions in competitive procurement environments.
Metallocene Polyethylene Market
From a structural perspective, market concentration remains notably elevated among top-tier participants, with leading firms commanding a significant share of industry revenue. This concentration carries strategic implications for procurement stability, technology licensing dynamics, and the pace at which new entrants or regional specialty producers can capture share in high-specification segments. Understanding these competitive fault lines is essential for organizations evaluating supplier diversification, partnership strategies, and long-term technology roadmaps.
Market Dynamics: Pricing, Regulations, and the Cost Equation
The operating environment for metallocene catalysts is shaped by a continuously evolving set of cost, regulatory, and downstream specification pressures. Raw material economics play a central role in determining margin resilience and adoption velocity. Recent market indicators from March 2026 highlight that mLLDPE pricing in Northeast Asia moved to approximately 1.19 USD per kilogram, reflecting a modest downward adjustment driven by declining upstream ethylene and metallocene catalyst feedstock costs at key producing facilities. While lower feedstock expenses can ease input pressure, the broader cost equation remains nuanced, particularly when evaluating the relative premium of metallocene systems compared to conventional catalyst alternatives.
Industry data indicates that metallocene catalysts generally carry a cost premium of approximately 30-40% relative to traditional Ziegler-Natta systems used in LLDPE production. This differential has historically positioned metallocene chemistry as a selective rather than universal solution, reserved for applications where precision polymer architecture delivers measurable performance advantages in film clarity, mechanical properties, downgauging potential, or processing efficiency. As downstream converters increasingly pursue thinner films, mono-material packaging, and enhanced recyclability, the economic justification for premium catalyst platforms is undergoing reconsideration, with performance-per-unit-cost becoming a central evaluation criterion.
Regulatory developments are compounding this shift. The European Union's Packaging and Packaging Waste Regulation requires recyclable and mono-material packaging solutions by 2030, creating a compliance-driven demand tailwind for metallocene catalyst-derived polyolefins that can meet stringent structural and recyclability specifications. Concurrently, stricter EU environmental regulations on single-use plastics are compelling converters to seek recyclable monomaterial packaging architectures, further reinforcing the role of precision catalyst chemistry in enabling specification-compliant output. These regulatory currents are not confined to Europe; they are influencing global packaging design standards and accelerating technology alignment across export-oriented manufacturing hubs.
Strategic Imperatives for 2026 Enterprise Planning
As organizations prepare their 2026 planning cycles, the metallocene catalyst market presents a distinct set of strategic considerations. First, technology selection decisions must be evaluated against long-term regulatory trajectories rather than short-term cost differentials alone. Catalyst platforms that enable recyclable mono-material structures and high-performance film specifications are likely to secure preferential positioning as compliance requirements tighten.
Second, regional capacity deployment and supplier diversification strategies should be informed by a clear understanding of where demand growth is concentrating and which catalyst architectures are gaining commercial validation in those environments. The interaction between regional pricing dynamics, feedstock cost movements, and downstream grade requirements will increasingly determine which supply relationships deliver sustainable margin resilience.
Third, competitive intelligence must extend beyond product specifications to encompass process integration capabilities, custom formulation responsiveness, and partnership ecosystems that shape commercial deployment velocity. Companies that can align catalyst performance with client-specific processing conditions and downstream end-use requirements will be best positioned to capture premium segments and defend against substitution risk.
Finally, scenario planning should incorporate both upside demand drivers, such as sustainability mandates and high-performance packaging growth, and downside pressures, including feedstock volatility, cost premium sensitivity, and competitive intensity among concentrated market leaders. The organizations that thrive in this environment will be those that treat catalyst strategy not as a procurement footnote but as a core component of polymer production economics and product differentiation planning.
Conclusion: Navigating the Forecast Window with Confidence
The metallocene catalyst market is entering a phase of accelerated structural evolution. Growth trajectory, competitive positioning, regulatory pressure, and raw material dynamics are converging to create a landscape where strategic foresight directly translates into commercial advantage. Our comprehensive market research study provides the analytical depth, segmentation clarity, and competitive context necessary to navigate this environment with confidence. For executive teams seeking to validate investment assumptions, optimize supplier strategy, and align technology adoption with downstream market demand, the full report delivers the granular intelligence required to convert insight into action.
To access detailed segmentation breakdowns, regional development patterns, application-specific consumption profiles, and complete competitive benchmarking data, we invite you to explore the complete publication through our official research portal. The full intelligence suite is designed to support executive planning, procurement strategy, and long-range technology roadmap development across the 2026-2032 forecast horizon.
For detailed analysis of this topic, please visit the official page: Metallocene Catalyst Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com