

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Cable Glands Market Hits $1.8B in 2025, Projects 6.5% CAGR to 2032

Cable Glands Market Strategic Outlook 2026: Navigating Growth, Compliance, and Competitive Intensity
Executive Summary: Why This Research Matters Now
The global cable glands market stands at a pivotal inflection point as industries confront tightening safety regulations, volatile raw material costs, and accelerating infrastructure modernization. For executives planning capital allocation, supplier diversification, and product roadmap investments through 2032, fragmented intelligence is no longer sufficient. Our latest market research translates macroeconomic trajectories into actionable strategic frameworks, enabling leadership teams to anticipate compliance shifts, optimize material sourcing, and position portfolios against entrenched competitors. This article previews the analytical depth available in the full study, highlighting the structural drivers, competitive dynamics, and decision-support tools that will define your 2026 planning cycle.
Market Trajectory: From Recovery to Sustained Expansion
Between 2020 and 2025, the cable glands sector demonstrated consistent revenue expansion, climbing from approximately USD 1.5 billion to an estimated USD 1.8 billion. The upward momentum is projected to accelerate through the forecast window ending in 2032, with a compound annual growth rate of 6.5 percent. By the close of the projection period, total market revenue is expected to approach USD 2.78 billion. This trajectory is not merely a reflection of incremental demand; it signals a structural upgrade cycle across industrial, energy, and infrastructure sectors where cable entry integrity, environmental sealing, and hazardous-location compliance have become non-negotiable design parameters.
Several converging forces underpin this expansion. Global electrification initiatives continue to drive cable deployment in power distribution, manufacturing automation, and renewable energy installations. Simultaneously, regulatory frameworks governing explosive atmospheres, moisture ingress, and electromagnetic compatibility are pushing engineers toward certified cable gland solutions rather than generic hardware. Raw material cost fluctuations—spanning brass, aluminum, plastic polymers, and nickel-plated steel—remain a persistent pressure point for manufacturers, influencing both pricing strategies and margin management. Yet, demand resilience across end-use sectors has consistently absorbed these inputs, reinforcing a market environment where scale, certification breadth, and supply chain agility determine competitive outcomes.
Strategic Implications of the Growth Curve
A 6.5 percent CAGR in a mature industrial hardware category is meaningful only when mapped to specific investment horizons. For procurement leaders, the forecast underscores the urgency of locking in long-term supplier agreements before capacity constraints tighten. For product managers, the growth window creates room to differentiate through specialized certifications, modular gland designs, and material innovations that reduce total cost of ownership. For corporate development teams, the expansion trajectory suggests that consolidation, geographic capacity expansion, and portfolio adjacencies will remain active themes among well-capitalized incumbents. The full research study quantifies these pathways without relying on speculative assumptions, anchoring each recommendation in observable market behavior and regulatory timelines.
Segmentation Architecture: Where Value Is Created and Captured
The market’s structural composition reveals clear concentration patterns that influence pricing power, innovation pacing, and customer acquisition strategies. Demand is distributed across multiple dimensional axes—by region, by type, by cable construction, by material, and by end-use industry—each carrying distinct margin profiles and compliance requirements. Understanding how these segments interact enables companies to avoid the common pitfall of treating cable glands as a commodity line item rather than a engineered interface with safety-critical performance expectations.
Hazardous Versus Non-Hazardous Applications
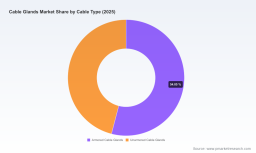
The split between hazardous-area and non-hazardous-area cable glands reflects a fundamental divergence in engineering requirements. Non-hazardous applications dominate overall volume, driven by general industrial, commercial, and infrastructure deployments where environmental sealing and strain relief are the primary value drivers. Hazardous-area solutions, while smaller in aggregate share, command premium positioning due to the rigorous certification burdens, specialized materials, and testing protocols required for explosive atmospheres. The strategic question for manufacturers is whether to deepen expertise in high-compliance niches or to scale broadly across standard applications while offering certified options as a differentiated tier. The research study maps the competitive positioning within each segment, highlighting where certification breadth, lead-time reliability, and technical support create durable barriers rather than transient price advantages.
Material and Cable Construction Dynamics
Material selection continues to shape both cost structures and end-customer preferences. Brass, stainless steel, and plastic nylon each offer distinct trade-offs in corrosion resistance, mechanical durability, weight, and procurement cost. Armored and unarmored cable constructions further differentiate installation requirements, clamping mechanisms, and sealing performance. Price volatility in base metals and polymer feedstocks has forced manufacturers to reassess bill-of-materials strategy, inventory buffering, and regional sourcing mixes. Companies that have integrated material forecasting with production scheduling are better positioned to stabilize pricing and maintain service levels during supply disruptions. The full report examines how leading producers are recalibrating material portfolios in response to these pressures, including the strategic use of nickel-plated brass, aluminum alternatives, and high-temperature polyamide formulations for specialized applications.
End-Use Industry Exposure
Demand flows from a diversified industrial base, with oil and gas, power and utilities, manufacturing and process industries, construction, and other sectors each contributing distinct growth drivers. Oil and gas operations prioritize flameproof and intrinsically safe glands for upstream and downstream environments, while power and utilities focus on long-term durability, weather resistance, and compliance with grid-installation standards. Manufacturing and process industries require glands that support automation density, frequent maintenance cycles, and chemical exposure resistance. Construction and ancillary segments often emphasize cost efficiency, ease of installation, and broad dimensional coverage. The research study isolates the demand signatures of each sector, helping executives align product lines, certification investments, and channel strategies with the industries where their capabilities generate the strongest competitive advantage.
Competitive Landscape: Incumbent Strength and Regional Diversification
Market concentration data indicates that the top three participants command roughly 45 percent of total revenue, while the top five collectively account for approximately 60 percent. This concentration level suggests a market where scale, global certification portfolios, and established distribution networks provide meaningful advantages, yet it also leaves substantial room for specialized manufacturers and regional players to compete through niche engineering, service responsiveness, and localized compliance expertise.
Global Incumbents and Specialty Leaders
Several established manufacturers illustrate the range of competitive strategies shaping the market. Hawke International has built a leading position in Exd and Exe cable glands and connection solutions for hazardous locations, leveraging deep expertise in explosion protection and global type approvals. HELUKABEL distinguishes itself through plastic and metal gland solutions that emphasize airtight seals, dust and moisture protection, and strain relief, supported by a broad industrial portfolio. ABB supplies industrial cable glands with widespread certifications and type approvals across wet, dry, indoor, outdoor, and corrosive environments, aligning its offerings with large-scale infrastructure and process deployments. Cembre contributes nickel-plated brass MAXIBRASS series glands with IP and EMC protection levels, appealing to customers seeking robust mechanical performance and standardized protection ratings. Phoenix Contact and Lapp Group both maintain strong positions in high-quality industrial cable connections, with Lapp Group’s SKINTOP® line spanning plastic, nickel-plated brass, and stainless steel metric glands, reinforcing a reputation for specification-grade reliability.
Regional and specialty manufacturers add further complexity to the landscape. AerosUSA serves as the exclusive U.S. supplier of AGRO Syntec and Syntec Anti-Kink polyamide glands featuring lamellar technology for multiple cable diameters, targeting buyers who value compact design and flexible diameter accommodation. Weyer Electric and Shanghai Weyer Electric Co., Ltd. operate as high-tech enterprises producing nylon, metal, and high-temperature multi-core glands, with an expanding footprint across new energy, railway, aerospace, and industrial applications. CGS Cable Glands has established itself as a leading Indian manufacturer with more than 28 years of experience in weatherproof, EMC, and flameproof solutions, reflecting the growing importance of Indian production capacity in both domestic and export markets. CMP Products, headquartered in Johannesburg, maintains a global leadership position in cable glands, cleats, and accessories, underscoring the strategic relevance of African manufacturing hubs in supply chains serving mining, energy, and industrial sectors.
Recent Market Activity and Momentum Signals
Competitive intensity is visible not only in product portfolios but in external engagement and innovation visibility. In June 2026, AerosUSA exhibited at RSSI to showcase cable glands and industrial wire protection solutions, signaling sustained attention to North American industrial buyers and specification communities. HELUKABEL participated in multiple international trade shows during the same period to demonstrate its cable glands portfolio and product innovations, reinforcing a market-presence strategy designed to capture cross-regional demand. The Lapp Group presented SKINTOP® cable glands and related products at AUTOMATE 2026 in Chicago, aligning its offerings with automation-focused audiences and underscoring the connection between cable management reliability and industrial control system performance. These visible activities are indicative of a broader pattern: manufacturers are increasingly using trade presence, technical demonstrations, and application-focused messaging to differentiate in a category where specifications and certifications often dominate purchasing decisions.
Regulatory and Technical Compliance: The Hidden Architecture of Demand
Compliance is not a peripheral concern in the cable glands market; it is a core determinant of market access, procurement eligibility, and risk exposure. Recent regulatory developments have sharpened the focus on certification rigor and documented conformity. In October 2025, the CSA issued a Certificate of Compliance for cable glands intended for external connections in Zone 1/Div 2 hazardous locations, reinforcing the importance of region-specific approvals for North American installations. At the same time, cable glands must comply with CAN/CSA-C22.2 No. 60079 series standards for use in explosive environments, a requirement that remains an active and enforceable benchmark for manufacturers serving hazardous-location customers.
Globally, the certification landscape continues to demand alignment with UL, CSA, UR, and ATEX/IECEx standards where applicable, especially for products destined for hazardous locations and safety-critical electrical installations. These certifications influence everything from material selection and production process controls to labeling, documentation, and post-market traceability. For buyers, the presence or absence of recognized certifications can determine whether a product enters the specification sheet at all. For manufacturers, maintaining certification breadth across multiple standards bodies is both a competitive asset and an operational burden, requiring sustained investment in testing, quality systems, and regulatory monitoring. The research study examines how certification portfolios are being used strategically, including where companies are expanding approvals to unlock new geographies, and where regulatory divergence is creating friction in cross-border supply chains.
Tubular Cable Lugs Market
Raw Material and Supply Chain Considerations
In addition to compliance, raw material dynamics remain a structural factor in manufacturing economics. Brass, aluminum, plastic, and nickel-plated steel form the core input base for cable glands, and global price fluctuations directly affect production costs and margin stability. Trade and import-export policies for these materials further influence manufacturing cost structures and supply availability, particularly for producers operating across multiple jurisdictions. Companies that have diversified supplier bases, implemented forward purchasing strategies, or redesigned product lines to accommodate alternative materials are better insulated against cost shocks. The full analysis connects these raw material pressures to segment-level margin behavior, regional sourcing patterns, and the pricing strategies that differentiate resilient competitors from those forced into reactive discounting.
What the Full Research Study Delivers
The complete market research report moves beyond high-level trends to provide operational decision support across multiple planning dimensions. It includes a detailed forecast model spanning the 2026–2032 period, built on a transparent methodology that links historical demand behavior to forward-looking assumptions. The study decomposes market size by region, type, cable construction, material, and end-use industry, allowing executives to test strategic scenarios against the segments most relevant to their portfolios. Competitive profiles extend beyond summary descriptions to evaluate positioning strength, certification coverage, material strategies, and visible market activities that signal near-term momentum.
Beyond market sizing, the report integrates regulatory tracking, raw material cost context, and trade-policy considerations into a unified view of market risk and opportunity. This integrated approach enables users to evaluate questions such as which certifications are becoming table stakes in specific geographies, where material substitution can reduce exposure to volatile inputs, and which competitors are building durable advantages through scale, technical service, or compliance breadth. For corporate strategy teams, the study provides a structured basis for market entry, product line rationalization, supplier negotiation, and M&A screening. For commercial leaders, it offers a clearer map of where specification ownership, channel relationships, and application-based selling can translate into share gains.
Cable Glands Market
How to Use This Intelligence in 2026 Planning
The strategic value of this research lies in its ability to convert broad market movement into focused action. Executives can use the forecast framework to align capacity planning, inventory policy, and procurement timelines with demand trajectories rather than short-term price signals. Product and engineering teams can prioritize certification investments and material decisions based on the segments where compliance and performance differentiation command premium returns. Sales and channel leaders can refine targeting by understanding which end-use industries are generating the most reliable demand growth and which competitive players are most active in those spaces. Procurement and supply chain managers can incorporate raw material and trade-policy context into sourcing decisions, reducing exposure to shocks that often disrupt reactive purchasing models.
The full report is designed to support these decisions with granular segmentation data, company-level benchmarking, and forward-looking scenario analysis that remains grounded in observable market behavior. It does not simply describe growth; it explains where growth is concentrated, why it is concentrated there, and how organizations can respond with disciplined investment rather than generalized optimism.
Conclusion: Positioning for the Next Phase of Market Evolution
The cable glands market is entering a period in which compliance rigor, material cost management, and competitive specialization will matter as much as baseline demand growth. A 6.5 percent CAGR through 2032 signals a meaningful expansion opportunity, but the real strategic challenge is to identify which segments, certifications, materials, and geographies align with an organization’s capabilities and risk tolerance. Market concentration among leading players indicates that scale and certification breadth remain powerful advantages, yet the presence of focused regional and specialty manufacturers demonstrates that targeted engineering and service excellence can still secure strong positioning.
For decision-makers preparing 2026 plans, the difference between reactive participation and strategic leadership will come down to the quality of market intelligence guiding capital, product, and supply chain choices. The full study provides the segmentation detail, competitor context, regulatory mapping, and forecast structure necessary to make those choices with confidence. Organizations that treat cable glands as a safety-critical, specification-driven interface rather than a commoditized fastener category will be better positioned to capture margin, defend share, and expand into the applications where performance requirements are intensifying.
For detailed analysis of this topic, please visit the official page: Cable Glands Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com