

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: IP Camera Market to Reach $32.22B by 2032, Driven by 13.0% CAGR

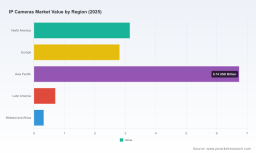
Unlocking the Strategic Value of the Global IP Cameras Market: A 2026 Decision-Maker’s Guide
The surveillance ecosystem is undergoing a structural transformation. What was once a straightforward security expenditure is now a strategic infrastructure investment, driven by artificial intelligence, cloud management, regulatory compliance, and expanding use cases across commercial, residential, and government environments. PW Consulting’s latest research on the IP Cameras Market is designed to convert this complexity into actionable intelligence for enterprise leaders, procurement teams, investors, and technology strategists navigating the 2026 decision cycle.
This flagship report does not merely chart historical trajectory; it equips stakeholders with the analytical scaffolding required to allocate capital, shape product roadmaps, anticipate regulatory shifts, and position against an increasingly concentrated competitive field. Below, we outline the strategic architecture of the study, the operational content it delivers, and why its insights will prove indispensable for organizations operating through 2026 and beyond.
The Macro Trajectory: Why 2026 Is a Strategic Inflection Point
Drawing on historical data spanning 2020 through 2025 and a forward-looking forecast window extending to 2032, the research captures a market that has demonstrated remarkable resilience and compounding momentum. Over the past half-decade, global IP camera revenue has expanded from $8.15 billion in 2020 to $13.72 billion in 2025, reflecting sustained demand across both mature deployment zones and rapidly emerging end-user segments.
The forward curve continues this acceleration. Forecasts indicate the market will reach $15.99 billion in 2026 and scale to $32.22 billion by 2032, underpinned by a compound annual growth rate of 13.0 percent. This trajectory is not simply a function of incremental unit growth; it reflects structural adoption drivers including AI-enabled analytics, cloud-native management platforms, heightened safety and compliance mandates, and the integration of visual surveillance into broader operational and clinical workflows. For enterprise decision-makers, understanding the timing, pacing, and underlying catalysts of this expansion is essential. Misjudging the velocity of adoption can result in misaligned capital deployment, obsolete product strategies, or missed partnership opportunities.
Industrial Cameras Market
Importantly, the research contextualizes these headline figures within the operational realities that shape procurement cycles, budget approvals, and regional rollout strategies. It examines how evolving reimbursement environments, capital expenditure constraints, and compliance requirements intersect with technology refresh timelines, giving leaders a grounded view of what is commercially viable and strategically advisable in 2026.
Report Content Overview: Operational Intelligence You Can Deploy
Designed for practitioners rather than passive observers, the report translates market signals into structured, operational content. Stakeholders will find a comprehensive framework built around the following deliverables:
- Market sizing and historical reconstruction (2020–2025): A rigorous baseline that reconciles retrospective revenues with documented adoption patterns, providing auditable reference points for internal forecasting models and investment committees.
- Forward-looking forecast (2026–2032): Scenario-grounded projections that illuminate pathway dependencies, growth inflection points, and the pacing of demand across evolving technology and compliance landscapes.
- Segmentation architecture: A multi-dimensional breakdown examining how different camera types, application environments, and regional dynamics interact to shape total addressable demand. The report shows how segment performance diverges, where adoption accelerates, and which structural factors constrain or amplify growth in specific deployment contexts.
- Competitive landscape and concentration analysis: Detailed profiles of leading manufacturers and platform providers, combined with market concentration metrics that reveal the balance between established incumbents and emerging challengers. This section helps readers assess competitive moats, partnership viability, and supplier diversification strategies.
- Regulatory and compliance mapping: A structured view of the legal and procurement frameworks influencing IP camera selection, including federal buying rules, healthcare data protection requirements, and region-specific certification mandates that reshape eligibility and deployment risk.
- Technology and product development tracking: Coverage of recent product launches, sustainability initiatives, and platform innovations that signal where manufacturers are directing R&D investment and how those decisions cascade into customer value propositions.
- Decision-support frameworks: Practical tools to evaluate vendor selection, compliance readiness, total cost of ownership, integration complexity, and upgrade pathways, enabling procurement and IT leaders to move from strategic intent to execution.
Rather than presenting isolated data points, the study threads these elements together into a coherent narrative about how market forces, technology maturity, regulatory pressure, and competitive positioning converge to define winning strategies in 2026.
Navigating the Competitive Landscape
The IP cameras market is defined by a blend of deep vertical expertise, platform differentiation, and intensifying strategic positioning. Market concentration data included in the report reveals a landscape where a relatively small group of players accounts for a substantial share of total revenue, reinforcing the importance of supplier evaluation, partnership architecture, and long-term vendor risk management.
Several manufacturers have built identifiable strengths around specific deployment contexts and compliance pathways. Axis Communications, based in Lund, Sweden, has strengthened its reputation around ARTPEC-based network IP cameras optimized for sensitive environments, including healthcare surveillance and privacy-compliant installations. Its September 2025 launch of an environmentally sustainable IP camera line using recycled materials reflects broader industry movement toward responsible manufacturing and product lifecycle considerations.
Hanwha Vision, headquartered in South Korea, continues to advance AI-enabled IP cameras and modular systems with integration pathways that support hospital safety, fall detection, and clinical workflows, including connections with Epic EHR environments. This illustrates a growing trend in which IP camera providers are no longer fulfilling a purely observational role but are becoming embedded participants in operational and safety workflows.
Dahua Technology, based in Hangzhou, China, has expanded its footprint through video-centric AIoT IP cameras and security solutions aimed at operational efficiency and regulatory compliance within hospital facilities. Bosch Security Systems, from Stuttgart, Germany, develops advanced IP camera systems tailored for healthcare security monitoring and integration with hospital infrastructure, reinforcing the importance of systems-level interoperability.
Pelco, operating from Fresno, California, produces IP camera series specifically engineered for patient safety monitoring and regulatory-compliant applications, while Hikvision has long maintained a presence in network IP cameras and facility-oriented hospital solutions focused on patient and visitor security and operational oversight. Verkada, based in San Mateo, represents the cloud-managed segment with platforms that incorporate HIPAA compliance and privacy features for healthcare facility security. Honeywell International, from Charlotte, North Carolina, contributes Performance Series and explosion-proof IP cameras suited for secure healthcare environments and facility upgrades. Arecont Vision, a U.S.-based manufacturer, is recognized for megapixel IP cameras selected for high-quality video coverage and system upgrades within hospital surveillance environments.
These profiles are not presented merely as company summaries. The report uses them to illustrate how different firms compete on architecture, compliance readiness, vertical integration, cloud versus on-premises models, and ecosystem partnerships. It also examines how procurement eligibility rules and regional certification requirements alter the competitive field, shaping which manufacturers can realistically participate in certain buyer segments.
Regulatory Dynamics and Compliance as Strategic Risk
One of the most consequential themes for 2026 is the rise of compliance as a gating factor in procurement. Federal buying environments increasingly require selection of NDAA-compliant IP cameras, with eligibility considerations that directly influence supplier eligibility for public-sector and contractor-adjacent deployments. At the same time, healthcare-focused deployments face HIPAA-driven expectations around data handling, access controls, and privacy-preserving features such as face blurring and secure authentication.
Beyond North America, regulatory momentum is reshaping deployment speed and product eligibility in other markets. From April 2026, STQC Essential Requirements compliance for CCTV and IP cameras becomes mandatory in India for all healthcare facility deployments. This creates a compliance deadline that procurement teams, system integrators, and technology vendors must plan around when evaluating rollout schedules, certification pathways, and vendor selection.
These regulatory layers cannot be treated as afterthoughts. They affect design requirements, supplier shortlists, integration complexity, renewal cycles, and total cost of ownership. The report structures compliance considerations as a strategic dimension rather than a legal footnote, giving leaders a clearer view of where risk concentrates and how to build procurement frameworks that remain resilient under evolving policy conditions.
IP Cameras Market
Technology Trends and Deployment Realities
The market’s growth is being reshaped not only by demand volume but by how the technology is deployed and valued. Fixed dome IP cameras continue to dominate many hospital installations because their discreet design, vandal resistance, and reliable coverage suit corridors and waiting areas where operational visibility must coexist with a patient-facing environment. This preference illustrates a broader principle: the winner in a given deployment scenario is often determined by installation constraints, environmental factors, and integration needs as much as by raw specification comparisons.
At the same time, the shift toward AI-powered IP camera systems with analytics capabilities introduces a strategic tension. Hospitals and other organizations want the operational efficiency and safety gains these analytics can provide, yet they frequently face capital expenditure constraints when upgrading legacy surveillance infrastructure. The report examines this dynamic in detail, exploring how organizations sequence upgrades, justify investments, and balance immediate security needs against longer-term analytics ambitions.
Cloud-managed platforms, privacy-preserving features, and sustainability-oriented product design are additional vectors shaping buyer preferences. Recent product activity, including sustainability-focused launches and platform-level compliance enhancements, signals that manufacturers are competing not only on image quality and reliability but on lifecycle impact, management simplicity, and regulatory readiness. For decision-makers, these qualities increasingly influence vendor selection because they affect long-term operating costs, audit exposure, and organizational alignment with internal sustainability or risk mandates.
Why This Report Matters for 2026 Decision-Making
The IP Cameras Market research is built for leaders who need more than a top-line number. Whether the objective is to plan a procurement cycle, prioritize product roadmap investments, evaluate market entry, assess supplier diversification, or prepare for regulatory deadlines, the study provides the context required to make those decisions with confidence.
Specifically, the report helps organizations:
- Understand where market momentum is strongest and what structural factors are propelling it.
- Evaluate competitive positioning with attention to concentration, vertical specialization, and platform differentiation.
- Anticipate compliance obligations and incorporate them into procurement and deployment planning.
- Align technology refresh strategies with budget cycles, operational priorities, and analytics roadmaps.
- Identify where sustainability, cloud management, and privacy features are becoming decisive purchase criteria.
By connecting market size, segmentation logic, competitive behavior, and regulatory dynamics within a single analytical frame, the report converts fragmented signals into a coherent strategy input. That integration is especially critical in 2026, when procurement teams and technology leaders must make multi-year commitments in an environment shaped by fast-moving compliance requirements, shifting deployment norms, and increasingly concentrated supplier options.
Next Steps: Accessing the Full Intelligence
This overview has outlined the strategic architecture of the study and the operational value it delivers. It has deliberately avoided itemizing the granular segment breakdowns, individual regional revenue figures, and detailed application-level splits that form the analytical backbone of the full report. Those specifics are essential for precise planning, but they are also the kind of proprietary intelligence that warrants deeper examination within the complete research package.
For decision-makers ready to move from strategic awareness to execution, the full report provides the detailed segment mapping, competitive profiles, compliance timelines, and forecast pathways needed to support board-level discussion, procurement selection, and product strategy formulation. Accessing the complete publication will give your team the specificity required to translate 2026 market momentum into disciplined, evidence-based decisions.
The IP cameras market is expanding with clarity and momentum. The question for enterprise leaders is no longer whether the category is growing, but how to position intelligently within it. PW Consulting’s research is designed to answer that question with the depth, discipline, and decision-ready structure your organization needs.
For detailed analysis of this topic, please visit the official page: IP Cameras Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com