

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Regenerative Medicine Market Hits $30B in 2025, Projected 22.5% CAGR Through 2032

Navigating the Regenerative Medicine Inflection Point: Strategic Intelligence for 2026 Decision-Makers
The regenerative medicine sector has graduated from a promising niche to a defining pillar of global healthcare. As we move through 2026, the convergence of advanced cell and gene therapies with robust tissue engineering platforms is fundamentally reshaping therapeutic paradigms, manufacturing economics, and competitive positioning. For corporate strategists, investors, and R&D leaders, navigating this complexity requires more than high-level trends; it demands granular, actionable intelligence calibrated for immediate decision-making.
Our latest market research study, Regenerative Medicine Market: Strategic Outlook 2026-2032 , delivers precisely that. This report serves as a comprehensive navigation system for organizations operating at the intersection of biotechnology, advanced manufacturing, and healthcare delivery. By synthesizing historical trajectory analysis, macroeconomic forecasting, competitive mapping, and granular regulatory assessment, we provide the analytical rigor necessary to navigate an environment characterized by rapid innovation cycles, evolving policy frameworks, and intense competitive jockeying.
A Market on a Compounding Growth Trajectory
The macroeconomic architecture of the regenerative medicine landscape has demonstrated remarkable resilience and expansion momentum. Over the historical evaluation window of 2020 through 2025, the sector's revenue base scaled from approximately 12.5 billion USD to 30.0 billion USD, reflecting a sustained compound annual growth trajectory that has consistently outpaced broader biopharma benchmarks. This foundational expansion has established a critical inflection point entering the current forecast horizon.
The forward-looking projections through 2032 illustrate a market poised for structural acceleration. Starting from a 2025 baseline of 30.0 billion USD, revenue trajectories are expected to climb to 37.16 billion USD in 2026, with compounding momentum driving valuations to 45.17 billion USD by 2027, and continuing upward through the latter half of the decade. The established forecast compound annual growth rate of twenty-two and a half percent underscores an environment where revenue generation mechanisms are scaling faster than traditional therapeutic categories. This growth velocity is not merely a statistical projection; it represents a fundamental recalibration of therapeutic economics, where the convergence of autologous and allogeneic platforms, advanced manufacturing capabilities, and expanding clinical applications creates compounding value streams.
However, translating top-line growth forecasts into executable corporate strategy requires more than directional numbers. It demands a precise understanding of where capital efficiency, therapeutic differentiation, and regulatory tailwinds intersect. Our analysis isolates the structural drivers enabling this sustained expansion, providing decision-makers with the contextual clarity needed to allocate resources, prioritize pipeline development, and position portfolios against emerging competitive threats.
Architects of Competitive Advantage in an Evolving Landscape
The regenerative medicine competitive arena is characterized by a distinguished blend of pharmaceutical legacy players, specialized cell and gene therapy developers, and tissue-engineering innovators. The sector exhibits moderate concentration dynamics, with the top three market participants collectively commanding forty-five percent of total revenue share, while the top five entities extend that influence to sixty-two percent. This concentration pattern reflects a landscape where established biopharma organizations leverage scale, regulatory expertise, and commercial infrastructure, while agile mid-tier developers capitalize on scientific novelty and niche therapeutic positioning.
Leading the pharmacological forefront, Novartis AG has cemented its position through pioneering autologous CAR-T cell therapies and breakthrough gene therapy modalities, including landmark treatments for hematologic malignancies and spinal muscular atrophy. The company's recent regulatory milestone involving expanded-use authorizations for next-generation neuromuscular therapies exemplifies how strategic lifecycle management drives sustained market relevance. Similarly, Gilead Sciences, Inc. has engineered a formidable presence in the cell therapy space through its portfolio of autologous CAR-T interventions targeting hematologic cancers, demonstrating the commercial viability of highly specialized manufacturing ecosystems. Bristol-Myers Squibb Company continues to advance its cell and gene therapy portfolio, particularly in multiple myeloma and related indications, while Amgen Inc. pushes the boundaries of allogeneic and autologous cellular platforms for refractory oncology applications.
In the tissue engineering and regenerative scaffolding domain, Smith+Nephew plc and Integra LifeSciences Corporation provide critical infrastructure for wound healing, orthopedic reconstruction, and neurosurgical applications, leveraging biologic matrices and engineered products that bridge acute care and long-term tissue restoration. Organogenesis Holdings Inc. and Cook Biotech, Inc. further reinforce this segment through advanced cellular and tissue-based product development, addressing complex wound management challenges and surgical regeneration requirements. Specialized innovators such as Mesoblast Ltd. and Vericel Corporation have carved out defensible positions in allogeneic mesenchymal stromal cell therapies, cartilage repair, and severe burn interventions, illustrating how therapeutic specificity can command premium positioning. Astellas Pharma Inc. remains focused on cardiovascular and orthopedic regenerative applications, while Pfizer Inc. continues commercializing gene therapy solutions for rare genetic disorders. Together, these organizations represent a multidimensional competitive mosaic where differentiation spans scientific platform type, therapeutic application breadth, manufacturing modality, and commercial execution capability.
Navigating the Decision Matrix: What Our Report Delivers
Translating macro-level growth trajectories and competitive overviews into boardroom-ready strategies requires a structured analytical approach. Our research methodology is designed to function as a strategic decision-support toolkit, delivering precisely the information layers that executives need to move from awareness to action.
The study begins with a comprehensive market sizing and forecasting architecture that maps historical performance from 2020 through the immediate 2025 baseline, then projects forward through a seven-year forecast horizon extending to 2032. This temporal framing allows organizations to stress-test growth assumptions, benchmark pipeline commercialization timelines against anticipated market absorption curves, and identify inflection windows where strategic investment yields maximum leverage. Crucially, the analytical structure avoids superficial aggregation; instead, it deconstructs revenue generation pathways, identifies the therapeutic and technological vectors that will dictate share allocation, and highlights the operational prerequisites required to capture disproportionate value.
Stem Cell Therapy Market
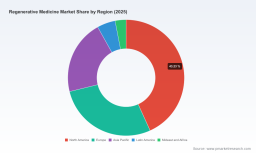
Our segmentation analysis dissects the commercial landscape across core therapeutic categories, delivery and application domains, and geographic dimensions. Rather than presenting fragmented percentage breakdowns, the report synthesizes these dimensions into an integrated strategic map that reveals where platform maturity, clinical demand, and manufacturing feasibility align. This approach enables R&D pipeline managers to evaluate therapeutic area prioritization with greater precision, while commercial leadership teams can assess geographic expansion timing against evolving reimbursement landscapes and regulatory readiness. The analysis also quantifies cross-segment dependencies, illustrating how innovations in one domain—such as advanced autologous manufacturing—create cascading effects across adjacent product categories and regional commercialization strategies.
Competitively, the report provides detailed corporate profiling for the sector's most influential participants, mapping their strategic positioning, pipeline emphasis, manufacturing modalities, and recent commercial milestones. Each profile is structured to support benchmarking exercises, partnership evaluation, and competitive response planning. By contextualizing recent corporate developments, regulatory interactions, and therapeutic approvals within broader market dynamics, the analysis reveals not just who is competing, but how competitive advantage is being constructed and defended in real time.
The 2026 Inflection: Regulatory Tailwinds, Operational Friction, and Strategic Imperatives
The current market environment is being actively reshaped by a series of interconnected dynamics that demand strategic recalibration. Regulatory frameworks are evolving to accommodate the unique scientific and manufacturing realities of regenerative interventions. In September 2025, the U.S. Food and Drug Administration issued draft guidance detailing expedited development programs for regenerative medicine therapies targeting serious conditions, explicitly outlining Regenerative Medicine Advanced Therapy designations and accelerated approval pathways. This guidance was followed in January 2026 by the agency's announcement of increased flexibility regarding Chemistry, Manufacturing, and Controls requirements for cell and gene therapies, including permissive release criteria within investigational new drug applications and reduced comparability data expectations. These regulatory shifts collectively lower historical barriers to clinical progression while signaling a more adaptive review environment for developers capable of demonstrating robust clinical benefit.
Commercialization, however, still encounters structural friction. High treatment costs and inconsistent reimbursement policies continue to constrain broader adoption of regenerative medicine therapies, particularly for cell and gene interventions that demand specialized manufacturing workflows and stringent cold-chain logistics. The financial structures supporting patient access remain fragmented across payers and health systems, creating variable adoption velocities that differ significantly by therapeutic category and geographic market. Simultaneously, supply chain resilience has emerged as a critical operational vulnerability. Approximately thirty-five percent of regenerative medicine manufacturers rely on imported key starting materials, a dependency that becomes particularly acute given the small-batch, patient-specific nature of many production processes and the narrow operational windows between apheresis collection, manufacturing completion, and clinical delivery. Manufacturing economics further compound these challenges, with per-batch cell therapy costs spanning a wide range driven by labor-intensive processing, specialized technical expertise, and scalability constraints inherent to small patient populations.
Recent corporate and regulatory developments throughout late 2025 and early 2026 illustrate how these dynamics are actively unfolding in practice. Regulatory approvals expanded into novel therapeutic territories, with non-profit-led gene therapy initiatives gaining authorization pathways and taxpayer-funded translational programs achieving their first commercial clearances. Industry participants navigated complex submission cycles, including priority-reviewed biologics license applications with accelerated review timelines. Manufacturing and commercial organizations simultaneously adjusted operational frameworks in response to evolving regulatory expectations, recalibrating quality systems, comparative data requirements, and supply chain contingencies to align with the new regulatory posture.
For strategic planners, the implication is clear: the companies that will capture disproportionate value in this environment are those treating regulatory engagement, reimbursement strategy, manufacturing scalability, and supply chain redundancy as integrated strategic pillars rather than isolated operational functions. Our report maps these interconnections explicitly, providing scenario-based guidance on how to align pipeline development, commercial launch sequencing, and partnership strategy with the evolving regulatory and reimbursement architecture.
Regenerative Medicine Market
From Insight to Execution: Why This Report Matters Now
In a market expanding at a twenty-two and a half percent compound annual rate through the end of the decade, the cost of strategic misalignment compounds rapidly. Organizations that rely on fragmented data sources, outdated competitive assessments, or generalized growth narratives risk misallocating capital, missing regulatory windows, and ceding positioning to competitors with more precise market intelligence. Our research is engineered to eliminate that uncertainty.
The report functions as a centralized strategic resource for multiple decision-making workflows. Corporate development teams can utilize the competitive mapping and segmentation architecture to evaluate acquisition targets, identify partnership opportunities, and assess white-space positioning within therapeutic categories where platform maturity and demand intensity converge. R&D and pipeline leadership can leverage the regulatory timeline assessment and manufacturing economics analysis to prioritize internal programs, design clinical development strategies that align with expedited pathway eligibility, and structure manufacturing workflows that balance scalability with patient-specific customization. Commercial and market access leadership can draw on the reimbursement and adoption friction analysis to design launch strategies that anticipate payer engagement requirements, optimize pricing architectures, and sequence geographic rollouts according to regulatory readiness and reimbursement maturity.
Furthermore, the report's forward-looking scenario construction extends beyond static forecasting. By modeling how regulatory flexibility, supply chain restructuring, and competitive concentration dynamics will interact across the 2026 to 2032 horizon, the analysis enables organizations to prepare for multiple plausible futures rather than betting exclusively on a single trajectory. This scenario-based approach is essential in a sector where scientific breakthroughs, policy adjustments, and manufacturing innovations can rapidly alter competitive positioning and market absorption velocity.
Access the Complete Strategic Intelligence
The regenerative medicine landscape is entering a decisive phase where competitive advantage will be determined by the precision of strategic intelligence, the agility of operational response, and the sophistication of cross-functional alignment. High-level trend awareness is no longer sufficient. Executives require detailed, integrated analysis that connects market sizing architecture, competitive positioning, regulatory evolution, reimbursement friction, and manufacturing economics into a coherent decision-making framework.
Our full report delivers that framework. It expands upon the market trajectory, segmentation dynamics, competitive profiles, regulatory and operational developments, and strategic recommendations outlined here, providing the comprehensive intelligence necessary to plan, execute, and defend strategic initiatives through 2032 and beyond. To access the complete analysis, including granular segmentation breakdowns, detailed competitive benchmarking, scenario modeling, and actionable strategic recommendations, visit the PW Consulting research portal and secure your copy of the Regenerative Medicine Market Strategic Outlook. Equip your organization with the intelligence required to navigate this inflection point with confidence.
For detailed analysis of this topic, please visit the official page: Regenerative Medicine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com