

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Print Quality Inspection Market to Reach $300M by 2032, Growing at 5.8% CAGR

Navigating the Print Quality Inspection System Market: Strategic Intelligence for 2026 Decision-Makers
The global manufacturing landscape is undergoing a profound transformation. As production lines accelerate and regulatory scrutiny intensifies, the Print Quality Inspection System market has emerged as a critical enabler of operational excellence. For executive teams, capital allocators, and strategic planners, understanding the trajectory of this market is no longer optional. It is a prerequisite for competitive positioning, supply chain resilience, and long-term value creation.
PW Consulting has published a comprehensive market research report that maps the Print Quality Inspection System market from historical baselines through 2032. This article serves as an executive preview of the research. It outlines the macro architecture of the market, highlights the competitive forces and technological inflection points shaping the sector, and explains why the full report delivers the granular intelligence required for actionable planning in 2026 and beyond.
A Decade of Resilient Expansion: Mapping the Macro Trajectory
Over the past half-decade, the market has demonstrated steady growth, reflecting the sector's embedded role in quality assurance across printing, packaging, and industrial inspection workflows. Historical data from 2020 through 2025 shows a consistent upward trajectory, with total market revenue progressing from approximately 148.5 million USD to 201.5 million USD by the base year. This sequence underscores a market that has weathered supply chain disruptions, component constraints, and shifting production priorities without losing structural momentum.
The forward outlook reinforces this trajectory. Forecasts for the 2026 to 2032 period project continued expansion, with total market revenue climbing from an estimated 216.69 million USD in 2026 to approximately 300.0 million USD by the end of the forecast horizon. This progression translates to a compound annual growth rate of 5.8 percent, a figure that positions the Print Quality Inspection System market as a steady, mid-single-digit growth segment within the broader industrial automation and quality control ecosystem.
For strategy leaders, these figures carry implications beyond headline sizing. They signal durable demand for inspection hardware, software, and integrated solutions across print and packaging value chains. The growth profile also suggests that market share dynamics will increasingly favor firms that can combine precision, speed, and software-driven flexibility rather than those competing solely on hardware specifications. As the market advances, the margin between incremental adoption and strategic deployment will widen, and the firms that act early will capture the benefits of scale, learning, and ecosystem positioning.
The full report provides the detailed historical-to-forecast bridge, sensitivity considerations, and scenario framing that enable finance and strategy teams to build defensible internal models. The macro numbers presented here establish the scale and pace of the opportunity; the report supplies the structural context needed to translate those numbers into decisions.
What the Report Delivers: Operational Content for Real-World Planning
Market data alone does not equip leadership to act. The strategic value of this research lies in its operational depth. The report is structured to support cross-functional usage, from procurement and engineering to product strategy and corporate development. It goes beyond aggregate sizing to examine how adoption patterns differ across system architectures, deployment contexts, and end-use requirements.
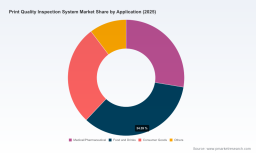
The segmentation analysis breaks the market into actionable dimensions. By system type, the research distinguishes between in-line and off-line inspection approaches, capturing the operational tradeoffs between continuous production monitoring and batch-oriented verification. By application, the report evaluates how demand varies across medical and pharmaceutical workflows, food and beverage packaging, consumer goods, and other industrial use cases. By geography, it maps regional dynamics to help leaders assess market maturity, competitive pressure, and growth potential in different operating environments.
Importantly, the report is designed to preserve analytical integrity while protecting commercially sensitive detail. It presents the framework and directional insights that executives need to prioritize internal work, while reserving the full breakdown of regional and application-level proportions, specific revenue figures, and granular share data for the authenticated report. This approach ensures that strategic conversations can begin with credible context, while the precise numbers remain tied to the official intelligence asset.
In addition to segmentation, the research integrates market structure indicators. Concentration metrics such as the combined share of leading competitors provide a lens on fragmentation, competitive intensity, and the room available for new entrants or consolidation plays. The report also addresses the practical constraints that influence deployment velocity, including the capital intensity of high-speed line scan imaging modules, integration requirements, and infrastructure readiness. These factors matter because adoption is rarely a pure function of demand; it is shaped by investment cycles, change management, and manufacturing economics.
The end result is a research deliverable that can support a range of planning activities: demand forecasting, capacity and investment timing, vendor evaluation, partnership scouting, and market entry analysis. It provides the scaffolding for informed decisions without reducing a multidimensional market to a single headline figure.
Competitive Landscape: Who Shapes the Market Today
No assessment of this market is complete without a clear view of the competitive field. The Print Quality Inspection System sector is populated by a mix of specialized inspection providers, vision technology leaders, and broader industrial automation companies. Each brings a distinct value proposition, from AI-enabled defect detection to prepress verification, web monitoring, tension control, and integrated quality management software.
Several firms illustrate the range of strategic positions in the market. EyeC GmbH, based in Hamburg, has built recognition around inspection and prepress verification solutions, including series architectures designed for defect detection and artwork verification. Its recent emphasis on cloud-based prepress inspection software reflects a wider industry movement toward hardware-independent inspection workflows and software-led differentiation. AVT Inc., headquartered in Israel, serves the label and flexible packaging industries with inspection and color measurement solutions focused on real-time defect detection and waste reduction, and has recently undergone a corporate transformation that refocused the business on dedicated inspection solutions.
LUSTER, operating out of China, has gained attention for AI-driven vision inspection systems that target high-speed printing and packaging workflows. Its product activity underscores the growing role of artificial intelligence in automating visual quality control. Procemex, based in Finland, offers web monitoring and inspection systems for pulp, paper, and printing applications, with defect detection solutions that extend beyond print alone into wider web processing. Erhardt+Leimer, also based in Germany, integrates web inspection and tension control with print quality solutions, a combination that resonates in paper, printing, and packaging environments where process stability and quality assurance are tightly linked.
Print Quality Inspection System Market
Other significant participants reinforce the breadth of the competitive set. Nireco Corporation from Japan supplies inspection systems for web and surface applications. Lake Image Systems in the United Kingdom provides comprehensive inspection solutions that span web and sheet monitoring, with product lines tailored to printing and packaging. Baldwin Vision Systems in the United States delivers defect detection systems for web and sheet-fed printing. Futec, also from Japan, focuses on inspection and control systems for high-speed printing processes. Esko, based in Belgium, contributes prepress and print quality inspection solutions, particularly around artwork and packaging verification. Omron, through its Microscan business in the United States, offers machine vision systems for automated inspection and verification in packaging and labeling. Cognex Corporation, likewise based in the United States, develops AI-powered vision systems for automated inspection and defect detection.
The competitive field is not static. Recent developments show a sector in motion. In March 2025, AVT Inc. announced its acquisition by Porat Itay Holdings and its transformation into an independent company, a move intended to sharpen its focus on print quality inspection solutions. In June 2025, LUSTER introduced the VisionPrint 8 AI Inspection System at CHINA PRINT 2025, highlighting next-generation AI for printing visual quality control. EyeC GmbH has continued to expand its software footprint, including the introduction of Proofiler Graphic Connect, a cloud-based prepress inspection tool designed to operate independently of hardware and systems. In May 2026, both Procemex and EyeC showcased inspection and monitoring solutions at major industry events, signaling continued emphasis on live demonstration, customer engagement, and ecosystem visibility.
This competitive mosaic matters because procurement and strategy teams rarely select a supplier in isolation. Decisions are shaped by integration requirements, regional service capabilities, software roadmaps, and compatibility with existing line architectures. The full report provides a structured competitive profile framework that supports vendor benchmarking and partnership evaluation, while the overview here establishes the breadth and dynamism of the market's key participants.
Forces Reshaping Demand: Technology, Regulation, and Manufacturing Economics
Market growth is not merely a function of capacity expansion. It is being reshaped by intersecting forces that influence both the pace and the nature of adoption. At the technology level, artificial intelligence is becoming a defining element of inspection systems. AI-powered defect detection, automated visual quality control, and software-driven verification are reducing reliance on manual inspection and enabling higher throughput with greater consistency. As these capabilities mature, they are changing the value proposition of inspection systems from reactive defect capture to proactive process assurance.
Regulatory and standards-driven factors are equally important. Quality management expectations continue to evolve across manufacturing sectors, and print quality inspection systems increasingly sit within broader compliance frameworks. International standards such as ISO 9001:2015 serve as a foundational reference for quality management across global manufacturing, while sector-specific requirements add further discipline. In regulated pharmaceutical and medical applications, compliance expectations tied to FDA and EMA standards create additional demands on packaging and print verification workflows. In February 2026, the Quality Management System Regulation took effect, amending device CGMP requirements and incorporating ISO 13485:2016 into quality management expectations. These dynamics reinforce the strategic relevance of inspection systems as instruments of documentation, traceability, and consistency.
X-ray Inspection Systems Market
Manufacturing economics also influence adoption patterns. Rising labor shortages in manufacturing environments are a material consideration, as they heighten the appeal of automated inspection and reduce the feasibility of manual quality checks at scale. At the same time, high capital equipment costs and the infrastructure investment required for high-speed line scan imaging modules can act as deployment barriers. This tension between labor-related pressure and capital-related constraints creates a nuanced demand environment in which adoption depends not only on technical merit but also on financing strategies, production planning, and total cost of ownership assessments.
Together, these forces create a market where intelligence must be both technical and commercial. Leaders need to understand how regulation, labor dynamics, and technology roadmaps will interact with segment-specific requirements and regional operating conditions. The report is built to address that complexity directly. It connects market structure to the operational realities that determine whether an inspection investment succeeds in a given environment.
Why This Report Matters for 2026 Strategy
For organizations planning in 2026, the Print Quality Inspection System market represents more than a niche equipment segment. It sits at the intersection of quality, automation, compliance, and production economics. That positioning makes it relevant to a wide range of decision-makers, including operations leaders evaluating line upgrades, procurement teams comparing inspection vendors, product strategists assessing adjacent opportunities, and investors modeling exposure to industrial automation and packaging technologies.
The strategic value of this research lies in its ability to convert broad market movement into practical decision support. The forecasting framework provides a defensible path from historical performance to forward expectations, enabling internal models that are grounded in documented market data rather than anecdotal assumptions. The segmentation architecture helps teams identify where growth is concentrated, where system preferences differ, and where application-specific requirements create differentiation opportunities. The competitive analysis supports vendor evaluation, partnership strategy, and positioning decisions. The integration of regulatory and operational context ensures that market size discussions are linked to the realities that shape deployment timing and success.
At the same time, the report respects the difference between directional intelligence and proprietary detail. It establishes the analytical frame, the competitive logic, and the operational levers that matter, while holding back the full regional and application-level breakdowns, precise revenue splits, and granular share figures for the authenticated version. This design is intentional. It allows leaders to assess the relevance of the research quickly and to justify deeper engagement with the complete dataset where decisions demand precision.
Moving from Context to Precision
Market research is most valuable when it shortens the distance between uncertainty and action. The Print Quality Inspection System market is expanding with steady discipline, shaped by AI-enabled inspection, evolving quality management expectations, manufacturing labor dynamics, and the capital considerations that accompany high-speed imaging infrastructure. The competitive field is diverse and active, and recent corporate and product developments indicate that software, cloud integration, and AI are becoming central to differentiation.
This overview provides the executive context needed to understand the market's scale, structure, and strategic significance. It frames the opportunity and explains how the full report extends that framing into actionable detail. For teams that need to make investment, procurement, product, or partnership decisions with confidence, the next step is to access the complete dataset, segmentation depth, competitor profiles, and scenario analysis contained in the full PW Consulting research. The macro story is clear; the detailed intelligence required to act on it awaits in the report.
For detailed analysis of this topic, please visit the official page: Print Quality Inspection System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com