

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Category: market research
Worldwide Bathroom Product Market 2026: 5.85% CAGR Growth Drivers & Key Shifts Until 2032
By pmarketresearch, 2026-09-18
The Changing Face of the Global Bathroom Product Market: Strategic Trends and Commercial Opportunities
Market Landscape: Size, Growth, and Structural Headwinds
The worldwide bathroom product market has transitioned from a mature, slow-growth sector into a structurally expanding market defined by steady capital deployment, product differentiation, and regional recalibration. Over the past half-decade, the industry moved from just under 100 billion USD in 2020 to approximately 128 billion USD in 2025, reflecting consistent annual expansion despite periodic supply disruptions and shifting demand patterns. The forward trajectory points to continued growth, with the market projected to reach roughly 137 billion USD by 2026 and approach 191 billion USD by 2032. This implies a compound annual growth rate of approximately 5.85 percent across the forecast horizon, a pace that signals more than cyclical recovery and instead indicates underlying shifts in how bathroom spaces are designed, purchased, and experienced. Growth is being distributed across the full product spectrum, from foundational ceramic sanitaryware to faucets, showers, vanities, and bathtubs, with the mix continually weighted by regional consumption habits and construction activity.
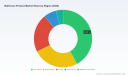
The regional footprint of the market reflects long-standing demand centers alongside faster-moving emerging corridors. Asia Pacific currently accounts for the largest share of global consumption, supported by strong residential construction, urbanization, and increasing per-capita spending on bathroom upgrades. North America and Europe together represent a substantial portion of the market, anchored by replacement demand, renovation cycles, and a consumer base that increasingly values design-led and water-efficient solutions. Latin America and the Middle East and Africa, while smaller in absolute scale, contribute meaningful pockets of growth tied to infrastructure development and expanding middle-class households. Distribution channels remain anchored in offline retail and wholesale networks, reflecting the tactile, specification-driven nature of many bathroom purchases, though digital channels continue to gain traction for catalog browsing, comparison, and direct-to-consumer experimentation. The market remains relatively fragmented, with no single company commanding dominant share, and the top few players collectively representing a modest concentration. This open structure creates room for new entrants, brand differentiation, and targeted geographic expansion.
Despite the favorable growth trajectory, the market faces several structural challenges that will shape competitive outcomes over the next several years. First, input cost volatility and material availability continue to pressure margins across ceramic production, metal fabrication, and finishing processes. Fluctuations in raw material pricing and energy costs have forced manufacturers to balance price increases with consumer sensitivity, particularly in mid-tier segments where substitution and deferred purchases are more likely. Second, regulatory pressures around water efficiency, safety, and sustainability are reshaping product requirements and compliance timelines. Buyers and specifiers increasingly expect fixtures that reduce consumption without compromising performance, while safety standards in certain categories, including infant and baby bath products, have drawn heightened scrutiny and recall activity. Third, trade policy uncertainty adds complexity to cross-border sourcing strategies. Announcements regarding potential tariffs on imported bathroom vanities and related products illustrate how quickly cost structures and supply routes can be disrupted, prompting companies to reconsider manufacturing footprints, inventory buffers, and regional sourcing mixes. These challenges do not threaten the overall growth narrative, but they do raise the bar for operational agility, product planning, and market entry timing.
Core Drivers Reshaping Demand and Competitive Advantage
Technology innovation is moving from a differentiator to a baseline expectation in bathroom products. Smart fixtures, sensor-based faucets, thermostatic shower controls, and integrated hygiene features are increasingly appearing across premium and mid-premium segments, driven by consumer interest in convenience, water management, and modern aesthetics. Recent trade show activity highlights how quickly product roadmaps are evolving. At the International Bathroom Exhibition in Milan in 2026, multiple manufacturers showcased sustainable materials, connected functions, and refined design language as central themes. The same pattern appeared at the Kitchen & Bath Industry Show in Orlando in 2026, where launches emphasized smart fixtures and sustainable solutions. These events reflect a broader shift in product strategy: companies are no longer treating smart features as isolated gadgets, but as part of integrated bathroom experiences that combine water efficiency, user interface design, and durability. TOTO’s unveiling of next-generation smart, sustainable, and luxury innovations, including matte color vessel lavatories at KBIS in 2025, illustrates how leading brands are pairing surface aesthetics with functional sophistication to capture attention in crowded showrooms and specification processes.
Policy and regulatory dynamics are equally influential in shaping product selection and market access. Water-saving requirements, safety mandates, and sustainability certifications are becoming more visible in procurement criteria and consumer preferences. The broader industry context is also seeing sustainability move into event and supply-chain standards themselves, as reflected by CERSAIE’s ISO 20121:2024 certification for sustainable event management in the ceramic tile and bathroom furnishings sector. Such signals matter because they indicate that sustainability is being institutionalized across the value chain, not simply used as a marketing message. For manufacturers and distributors, this means that compliance readiness, documentation, and transparent sustainability claims are becoming part of competitive positioning. Regulatory attention in specific categories can also have immediate commercial consequences. Recent safety warnings and recalls involving unstable infant and baby bath seats point to the importance of design validation and post-market monitoring, especially for products used by vulnerable populations. Companies that embed rigorous testing and usability review into product development are better positioned to avoid disruptions and protect brand trust.
Consumer and specifier behavior is shifting in ways that favor design coherence, performance reliability, and total cost perception. In renovation and new-construction settings, bathroom decisions are increasingly made with a broader view of water usage, maintenance, and long-term durability rather than initial sticker price alone. Ceramic continues to hold strong appeal in sanitaryware due to its durability and chemical resistance, a reputation that supports its continued dominance in many markets. At the same time, consumers are responding to broader style shifts, including matte finishes, integrated vanities, and coordinated fixture families that make smaller or aging bathrooms feel more contemporary. The purchasing journey is also evolving. Offline retail and wholesale channels still handle the majority of transactions because bathroom products often require physical evaluation, measurement, and installation coordination. Yet online channels are growing as a discovery and comparison layer, and in some cases as a transaction channel for accessories, replacement parts, and simpler fixtures. This dual-channel reality means that brands must maintain consistent product information, visual presentation, and availability signals across both environments to avoid losing prospects during the specification journey.
Supply chain and cost structure changes are becoming a strategic variable rather than a background condition. Tariffs and trade policy risk can quickly alter the economics of imported vanities and related bathroom products, and operators in North America and other import-dependent markets have had to plan for potential cost shocks. In parallel, producer price movements in key manufacturing regions have affected the economics of ceramic sanitary fixtures. Recent eurozone data showed producer prices for ceramic sanitary fixtures in France at elevated index levels in late 2025, underscoring how regional cost conditions can differ materially even within a globalized industry. These dynamics are encouraging companies to diversify sourcing, consider regional production or assembly where feasible, and improve demand forecasting to reduce inventory risk. For suppliers that can manage cost, quality, and lead times simultaneously, the current environment offers an opportunity to win share from competitors that are slower to adapt their sourcing or pricing models.
Competitive Landscape: Positioning, Differentiation, and Structural Shifts
The competitive field is broad and geographically diverse, with strong representation from established multinational brands and increasingly capable regional players. Kohler continues to compete on the strength of a comprehensive product range spanning faucets, showers, sinks, toilets, bidets, and smart fixtures, with emphasis on design, water efficiency, and the residential and commercial segments. TOTO has built a reputation around advanced sanitaryware, smart toilet systems, and water-saving technology that links hygiene, sustainability, and luxury performance. LIXIL operates through a portfolio of well-known brands and offers complete bathroom solutions across faucets, showers, sanitaryware, and water-efficient systems for global use. Roca combines ceramic sanitaryware, faucets, showers, and bathroom furniture with a focus on design, sustainability, and quality. Geberit is distinct in its emphasis on concealed plumbing systems and innovative bathroom technologies for both commercial and residential installations. European premium players such as Villeroy & Boch and Duravit compete through luxury design, high-quality materials, and modern aesthetics, while Hansgrohe focuses on premium shower systems and faucets with water-saving technology and design-led positioning. In the North American market, American Standard and Moen maintain strong recognition for reliable, accessible fixtures, and Masco plays a significant role through brands that serve residential plumbing needs. In emerging markets, RAK Ceramics, Jaquar, CERA, and Hindware are expanding the middle-to-premium pipeline, using local market knowledge and scale to compete across sanitaryware, faucets, and related products.
The differentiating success factors in this landscape are becoming clearer. First, product breadth and system thinking matter. Companies that can offer coordinated faucets, showers, sanitaryware, and vanities reduce friction for specifiers and renovators who want a unified look and predictable installation outcome. Second, technology integration and water efficiency are increasingly linked to brand relevance. Smart functions, flush performance, sensor-based hygiene, and reduced water consumption are no longer niche features; they are central to winning in premium and semi-premium segments where buyers expect a combination of comfort and sustainability. Third, regional credibility remains powerful. Multinational brands benefit from global scale and design language, but regional players often win by tailoring products to local tastes, price points, and installation practices. This is especially visible in markets where bathroom styles, water conditions, and consumer price sensitivity differ substantially from the global average.
Bathroom Vanities Market
The market structure is evolving through a mix of consolidation pressure and segmentation depth. Concentration remains moderate, which leaves space for brand specialization and regional expansion, but the competitive center of gravity is shifting toward companies that can manage design, technology, and supply chain performance at the same time. Recent industry events suggest that innovation is being presented in more integrated ways, with sustainability, technology, and design presented as a combined narrative rather than separate product claims. This points to a future in which the winners are less defined by a single hero product and more by the ability to deliver consistent experiences across categories. At the same time, new entrants and brand extensions continue to test niche positioning in wellness, designer collaborations, and smart home connectivity, keeping the market dynamic. The most important structural question for incumbents is whether they can scale innovation without eroding the margin and quality control that support premium positioning.
Forward Outlook: Three Trends Shaping the 2026–2030 Horizon
One of the clearest forward trends is the accelerating normalization of smart and water-conscious bathroom products as mainstream expectations rather than premium add-ons. Over the next few years, sensor-driven fixtures, efficient flush technologies, and more intuitive control interfaces are likely to move further down the price pyramid as manufacturing processes mature and component costs stabilize. This will create opportunity for brands that can deliver reliability and simple user experiences rather than feature-heavy products that complicate installation or maintenance. The commercial opportunity lies in specification-friendly systems that help contractors and renovators meet efficiency goals without sacrificing design quality, especially in multifamily housing, hospitality, and renovation programs where long-term operating costs matter.
A second trend is the growing importance of regional supply resilience and pricing agility. Trade policy uncertainty, raw material price variation, and shifting production costs will continue to reward companies that can adjust sourcing strategies and portfolio pricing with speed. This does not necessarily mean abandoning global sourcing, but it does favor organizations that maintain flexible manufacturing networks, clear visibility into cost drivers, and disciplined portfolio management. Businesses that can hold quality steady while responding to tariff exposure and input price movement will gain share in markets where competitors are slower to recalibrate. There is also an opportunity in mid-market segments, where consumers may delay upgrades if price increases outpace perceived value, making value engineering and design coherence particularly important.
A third trend is the continued blending of hygiene, wellness, and design in bathroom product offers. Post-pandemic attention to cleanliness did not disappear; it evolved into broader expectations for easy-to-clean surfaces, controlled water contact, and finishes that support both aesthetics and maintenance. Combined with consumer interest in spas, relaxation, and contemporary interiors, bathroom products are increasingly positioned as part of a wellness experience rather than purely utilitarian fixtures. The risk here is that trend-led launches can outpace practical performance, especially if features add complexity or reduce durability. Companies that balance style with robust engineering and clear installation guidance will be better positioned to convert interest into repeat business and favorable specification outcomes. A related uncertainty is the pace of regulatory change and trade policy adjustments, which can alter regional economics quickly and require companies to revise launch timing, channel strategy, and sourcing plans with limited lead time.
Actionable Priorities for Decision-Makers
For manufacturers, the priority is to strengthen portfolio coherence and reduce friction across the specification-to-installation journey. That means aligning faucets, sanitaryware, showers, and vanities in ways that make it easier for buyers to choose a complete solution, while ensuring that smart and water-saving features add genuine value rather than complexity. Equally important is building flexibility into sourcing and pricing so that potential tariff exposure and raw material movement can be managed without sudden erosion of margin or inconsistent product availability. Companies that can demonstrate reliable lead times, stable quality, and clear sustainability and safety documentation will have an advantage when specifiers compare options.
PW Consulting
For investors, the opportunity lies in identifying operators with durable brand relevance, disciplined cost structures, and the ability to scale innovation without compromising quality. The market’s moderate concentration and continued growth create room for selective value creation, especially where companies have strong regional positioning or differentiated technology in water efficiency, hygiene, or designer appeal. Attention should be paid to supply chain resilience and product mix, since businesses overly reliant on a narrow set of cost-sensitive inputs or import-heavy routes may face more volatility than peers with diversified production and channel strategies.
For procurement and retail leaders, the strategic task is to keep product information, availability, and visual presentation consistent across offline and online touchpoints while managing exposure to policy and cost shocks. This includes developing clear category plans that balance replacement demand with upgrade cycles, maintaining relationship strength with installation partners, and using flexible sourcing options to reduce vulnerability to tariff-related price increases. For deeper segmentation detail, regional sizing, competitive share estimates, and channel-specific scenarios, the full research report provides the supporting data and structured frameworks needed for more precise portfolio and sourcing decisions.
Toilet Seat Market
For detailed analysis of this topic, please visit the official page: Worldwide Bathroom Product Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Worldwide Fluorozirconic Acid Market: Asia Pacific's 4.6% CAGR Leads to $71.8M by 2032
By pmarketresearch, 2026-09-18
Scaling Production, Navigating Volatility: Strategic Dynamics in the Global Fluorozirconic Acid Market
The worldwide fluorozirconic acid market has entered a phase of measured expansion, characterized by steady revenue growth, shifting regional purchasing patterns, and evolving supply chain economics. From 2020 through 2025, the sector demonstrated consistent demand absorption across industrial and specialty applications, with total market revenue reaching approximately 52.4 million in the most recent base year. Looking ahead to the forecast horizon ending in 2032, the market is projected to maintain a compound annual growth rate of 4.6 percent, gradually scaling toward the mid-70 million range. This trajectory reflects a market that is neither in hyper-growth nor in structural decline, but rather in a maturation stage that rewards disciplined capacity planning, application diversification, and supply chain resilience.
Current industry conditions present a set of interlocking challenges that will define competitive outcomes over the next several years. First, raw material input volatility remains a persistent pressure point. The primary feedstocks required for fluorozirconic acid synthesis have experienced notable price fluctuations, particularly in key producing regions, forcing manufacturers to navigate margin compression while attempting to preserve pricing stability for downstream buyers. Second, regulatory and environmental compliance requirements are tightening across multiple jurisdictions, altering procurement standards and raising the operational baseline for production facilities. Third, the market is experiencing a gradual realignment in how purchasing organizations evaluate supply partners, shifting from pure price optimization toward reliability, technical support, and consistent specification compliance. These forces are compelling companies to recalibrate their operating models rather than rely on historical growth assumptions.
The broader market structure also reflects meaningful concentration dynamics. A relatively small group of established participants accounts for a substantial share of total industry revenue, indicating that scale, technical reputation, and long-standing distribution networks continue to exert strong influence on commercial positioning. At the same time, the presence of mid-tier manufacturers and regional suppliers signals an ecosystem that retains room for specialized entrants, particularly those capable of serving specific application verticals or concentration requirements. This combination of concentration and fragmentation creates a competitive environment where differentiation is increasingly tied to execution quality rather than product novelty alone.
For executives and strategic planners, the immediate implication is clear: the market rewards operators who can balance cost discipline with service reliability. Companies that treat fluorozirconic acid as a commodity input risk exposure to margin swings and supply disruptions, while those that integrate the chemical into broader application ecosystems—such as surface treatment workflows, specialty glass processing, or catalyst formulations—can capture more defensive margin profiles. Similarly, procurement teams face a market in which supplier selection has become a strategic decision, not a routine purchasing task. Understanding where capacity is expanding, where feedstock economics are shifting, and how regional demand is evolving will separate organizations that simply absorb cost pressure from those that convert market dynamics into commercial advantage.
Key Drivers Reshaping Market Trajectory
Market movement in fluorozirconic acid is being shaped by a combination of technical, regulatory, demand-side, and cost-structure factors. These drivers do not operate in isolation; they interact in ways that determine which applications grow, which production regions gain leverage, and how suppliers position themselves for the forecast period.
PW Consulting
Technical Innovation and Application Expansion
Advancements in process efficiency and application engineering are gradually reshaping how fluorozirconic acid is produced and utilized. On the production side, manufacturers are increasingly focused on optimizing concentration consistency, reducing impurity profiles, and improving batch-to-batch reliability. These improvements matter particularly for industries where chemical performance directly affects downstream outcomes, such as metal surface treatment and optical glass manufacturing. In parallel, application-side innovation is expanding the relevance of fluorozirconic acid beyond legacy use cases. Surface treatment formulations continue to evolve as manufacturers seek stronger corrosion resistance, better adhesion characteristics, and more controlled conversion coating performance. In ceramics and glass segments, the chemical's functional role in specialized processing has supported steady demand from producers looking to maintain material quality while managing cost structures.
For businesses, this means the value of fluorozirconic acid is increasingly tied to performance reliability rather than volume alone. Suppliers that can demonstrate consistent specifications, provide technical guidance, and adapt to formulation changes are better positioned to retain and expand account relationships. Conversely, buyers that standardize on poorly characterized supply risk quality variability that can cascade into production inefficiencies.
Policy and Regulatory Environment
Regulatory expectations are becoming a more prominent factor in procurement and manufacturing decisions. Environmental compliance, chemical handling standards, and industrial safety requirements are influencing how producers operate and how end-users qualify suppliers. In several regions, tighter oversight of fluoride-related chemicals and related industrial processes has raised the bar for documentation, traceability, and operational controls. These requirements are not uniform across markets, which creates a differentiated landscape where companies with stronger compliance systems can use them as a commercial asset rather than viewing them purely as cost centers.
The policy environment also interacts with trade dynamics. Cross-border supply arrangements are increasingly evaluated through the lens of regulatory alignment, customs considerations, and long-term supply assurance. As a result, organizations that depend on imported fluorozirconic acid are placing greater emphasis on supplier consistency, certification coverage, and regional availability. This dynamic favors established distributors and manufacturers with clear compliance records, while raising the entry threshold for less-documented supply sources.
Demand-Side Behavior and Industrial Purchasing Patterns
End-user demand is evolving in ways that influence both volume and purchasing behavior. In metal surface treatment, continued industrial activity and maintenance-driven coating requirements sustain baseline consumption, while performance expectations push buyers toward products that deliver predictable results across varied substrates and process conditions. In specialty applications such as ceramics, glass, and chemical catalysis, demand tends to be more sensitive to production cycles, capital investment patterns, and formulation changes. This creates a market where some segments behave as steady industrial consumables, while others are more cyclical or innovation-driven.
A notable shift in purchasing behavior is the growing preference for suppliers who can support application-specific needs rather than simply offer the lowest unit price. Procurement teams are increasingly weighing specification consistency, availability, technical communication, and delivery reliability. This trend rewards suppliers with stronger customer-facing capabilities and creates an opportunity for manufacturers to differentiate through service, not just chemical grade.
Supply Chain and Cost Structure Dynamics
Cost structure remains one of the most important market levers, and feedstock economics are central to that picture. Hydrofluoric acid, a primary input for fluorozirconic acid production, has experienced meaningful price movements in recent periods. In the Chinese domestic market, prices moved upward over the course of 2025, reflecting broader input cost pressures and regional supply conditions. By early 2026, fluorozirconic acid-linked feedstock pricing in China was observed in a higher range than historical norms, tightening cost calculations for producers and affecting the economics of export-oriented supply. In Europe, intra-EU hydrofluoric acid transaction prices remained elevated at the start of 2026, sitting substantially above pre-2019 levels and reinforcing cost challenges for regional manufacturers.
At the same time, upstream zirconium mineral availability has provided a degree of feedstock foundation for zirconium-based chemicals. Global mine production of zirconium mineral concentrates rose to an estimated 1.5 million tonnes in 2024, supporting broader feedstock availability for downstream chemical processing. This does not eliminate cost volatility, but it does indicate that the raw material base underpinning zirconium chemistry remains functional and, in aggregate, expanding. The market implication is nuanced: availability is not the primary constraint, but price transmission from feedstock markets to finished fluorozirconic acid is a persistent factor that operators must manage through pricing strategy, contract structuring, and production efficiency.
Competitive Landscape and Strategic Positioning
The competitive environment in fluorozirconic acid is defined by a mix of established manufacturers, regional producers, and distribution-focused suppliers. Market concentration is significant, with a relatively small set of participants capturing a majority share of industry revenue. This structure reflects the importance of production experience, specification reliability, and established commercial relationships in a market where downstream users place high value on consistency.
European-based manufacturers continue to hold a recognized position in the market, particularly where high-quality production standards and long-standing supply track records matter. Companies operating from Spain and the broader European region have built reputations around industrial-grade reliability and global distribution capability, often aligning their commercial positioning with compliance, product consistency, and established customer relationships. Their strategic advantage typically lies in perceived quality assurance and the ability to serve industrial customers that prioritize specification stability over aggressive price competition.
Hydro Fluoric Acid Market
Chinese manufacturers represent a substantial portion of the supply landscape, reflecting both domestic demand and export-oriented production. Several firms based in Foshan, Nantong, Hunan, Yixing, and other industrial centers supply fluorozirconic acid for metal surface treatment, optical glass, fluorozirconate production, and related industrial applications. These producers often compete on a combination of pricing, production scale, and the ability to serve multiple downstream verticals. Their market role is shaped by access to feedstock inputs, production flexibility, and the capacity to support both wholesale and industrial-grade requirements. In many cases, Chinese suppliers have become integral to global supply chains by offering a broad range of concentration options and application-aligned product formats.
Outside of Europe and China, other regional players contribute to the market's diversity. Indian manufacturers supplying multiple concentration grades for technical applications have built export-oriented businesses that serve a range of international buyers. In the United States, certified distributors and global raw material suppliers provide fluorozirconic acid through established logistics and quality management frameworks, often positioning themselves as reliable intermediaries for industrial customers that need documented compliance and consistent availability. In the United Kingdom, distributors focused on bulk industrial packaging and customer-specific delivery configurations add further supply chain flexibility, particularly for buyers that prioritize handling convenience and large-volume order execution.
The strategic differences among these participants are instructive. Some compete primarily through production efficiency and price competitiveness; others differentiate through certification, documentation, technical support, or specialized packaging and logistics. The most resilient players tend to combine several of these strengths rather than rely on a single attribute. A manufacturer that can offer consistent specifications, maintain dependable lead times, and respond to application-specific requirements is better positioned than one competing on price alone, especially in a market where feedstock cost volatility can quickly erode thin margins.
Market evolution is likely to continue along two parallel paths. On one hand, consolidation pressure may intensify among smaller operators facing rising compliance costs, feedstock volatility, and the need for stronger quality systems. On the other hand, the market retains space for specialized or regional entrants that can serve distinct application needs, offer differentiated concentration grades, or provide strong local service and logistics. New entry is not impossible, but success will increasingly depend on credible production capability, clear quality assurance, and the ability to integrate into downstream procurement systems. The overall pattern suggests a landscape that is concentrated at the top, active in the middle, and selective at the edges.
Forward-Looking Trends and Commercial Implications
Over the next three to five years, several trends are likely to shape how the fluorozirconic acid market develops and where commercial opportunities emerge.
One important trend is the continued elevation of supply chain reliability as a competitive differentiator. As feedstock costs remain sensitive and regulatory expectations persist, buyers will place greater weight on suppliers that can deliver predictable availability and consistent specifications. This will favor organizations that invest in production discipline, inventory planning, and transparent communication with customers. For suppliers, the opportunity lies in building long-term account trust rather than competing transaction-by-transaction.
A second trend is gradual application-driven demand evolution. Metal surface treatment is expected to remain a core demand anchor, but growth will be influenced by industrial maintenance cycles, coating performance expectations, and the willingness of manufacturers to standardize on reliable chemical inputs. In ceramics, glass, and catalyst-related uses, demand will likely track more closely with specialty production activity and formulation innovation. This creates an environment where companies with stronger application knowledge and closer customer collaboration can capture more resilient demand than those relying solely on commodity-style selling.
Zirconium Oxychloride Market
A third trend is the ongoing pressure on cost management and pricing strategy. Feedstock volatility, regional price divergence, and compliance-related operating costs will continue to shape margin dynamics. Businesses that succeed will need to combine efficient production, disciplined commercial pricing, and flexible contract structures. There is also an opportunity for suppliers to create value through concentration specialization, packaging optimization, and technical service, all of which can support healthier margin profiles in a market where pure price competition is increasingly risky.
Potential risks should not be overlooked. Feedstock price shocks, changes in regulatory interpretations, trade friction, or abrupt shifts in downstream demand could disrupt otherwise steady market conditions. In addition, overconcentration of supply dependence on a limited number of sources can heighten vulnerability for buyers and create pricing leverage for suppliers during tight periods. Organizations that monitor these risks early and build contingency options will be better prepared to navigate periods of uncertainty.
Strategic Guidance for Decision-Makers
Market participants should approach fluorozirconic acid with a clear understanding of where value is created and where exposure accumulates. For manufacturers and suppliers, the priority is to strengthen production consistency, compliance readiness, and customer-facing technical capability. Differentiation through specification reliability and service responsiveness is likely to be more durable than competing on price alone, especially given ongoing feedstock cost volatility and the importance of long-term buyer trust.
For investors and corporate development teams, the market warrants attention to companies with credible production bases, diversified application exposure, and the ability to manage input cost transmission. The most attractive positions are often those that combine scale with application relevance and supply chain discipline, rather than those that depend on a single thin-margin commodity pathway. Monitoring feedstock trends, regional pricing divergence, and capacity changes will be essential for assessing where competitive advantage is likely to intensify or erode.
For procurement and operations leaders, supplier selection should be treated as a strategic function. Evaluating suppliers on specification consistency, availability, documentation, and technical support can reduce downstream risk and improve overall process stability. Diversifying supply options where feasible, understanding regional feedstock dynamics, and aligning purchasing terms with realistic cost conditions can help organizations avoid overreliance on fragile supply arrangements.
Detailed segment-level data, regional demand patterns, concentration-grade breakdowns, and application-specific volume dynamics can materially improve planning quality, but they require a more granular view than market-level indicators alone can provide. Decision-makers seeking to translate these trends into precise sourcing, investment, or product strategy will benefit from fuller market detail, including the kind of segmented analysis that supports scenario planning and competitive benchmarking. For teams that need deeper visibility into submarket size, application demand splits, regional pricing context, and company-level positioning, the complete PW Consulting research report provides the structured detail necessary to move from directional insight to operational decision-making.
For detailed analysis of this topic, please visit the official page: Worldwide Fluorozirconic Acid Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Construction Smart Wearables: Why an 11.5% CAGR Reshapes Safety and Productivity Through 2032
By pmarketresearch, 2026-09-18
The Worldwide Construction Smart Wearable Market: Strategic Shifts and Commercial Opportunities (2025–2032)
The global construction industry is undergoing a quiet but profound transformation. After years of incremental adoption, smart wearable technologies have crossed a strategic inflection point. From connected hard hats that detect fatigue and hazardous gases to exoskeletons that reduce musculoskeletal strain and wrist-worn devices that track lone-worker safety in real time, these tools are shifting from experimental pilots to mission-critical operational infrastructure. The market trajectory reflects this maturation. Revenue climbed steadily from 350.0 million in 2020 to 780.0 million in 2025, with the growth curve accelerating into the forecast period. By 2032, the sector is projected to reach 1,671.17 million, expanding at a compound annual growth rate of 11.5 percent from 2025 through 2032. This is not merely a hardware procurement cycle; it represents a structural reorientation of how construction firms manage risk, productivity, and workforce welfare.
The scale of this expansion masks several structural frictions that determine which players will capture value and which will face margin compression. The market remains moderately fragmented, with the top three players holding approximately 25.5 percent of revenue and the top five reaching 34.2 percent. Such concentration leaves substantial runway for consolidation, but it also underscores that scale alone does not guarantee defensibility. The real competitive moats are being built through data integration, regulatory alignment, and site-level operational fit. Meanwhile, the sector is navigating a set of intertwined challenges that will shape investment priorities and product roadmaps over the next half-decade.
Operational Realities and Structural Friction Points
Three interlocking challenges are defining the current market environment. The first centers on rugged reliability versus technological ambition. Construction environments impose extreme thermal cycling, dust exposure, vibration, and continuous physical stress. Hardware designs must balance sensor richness with field durability, and the tension is most visible in power architecture. Continuous biometric and environmental monitoring draws substantial current, and battery endurance in many deployed units remains constrained to roughly 12–24 hours under real-site conditions. For contractors running multi-day shifts or remote operations with limited charging infrastructure, this creates a practical adoption ceiling that no amount of feature marketing can override.
The second challenge lies in data utility and workflow integration. A wearable that streams location, impact, vitals, or environmental readings generates data, but data does not automatically become operational value. Site supervisors, safety managers, and project controls teams are overloaded with fragmented inputs. Devices that cannot push contextual alerts into existing safety management, scheduling, or field execution platforms tend to become underutilized assets rather than risk-mitigation multipliers. The organizations gaining traction are those treating the wearable not as a standalone gadget but as a sensor node within a broader site intelligence stack.
Worldwide Military Smart Wearable Devices Market
The third challenge is regulatory and ethical complexity. Compliance expectations are tightening on multiple fronts simultaneously. Occupational safety rules increasingly expect hazard detection and personal protective equipment that meets documented performance thresholds. Standardization frameworks are incorporating connected monitoring into occupational health and safety management practices. Wireless deployments must satisfy electromagnetic compatibility and certification requirements to avoid interference on dense job sites. At the same time, biometric and location tracking raise worker privacy questions, especially in jurisdictions where consent and data minimization are enforced stringently. Companies that treat compliance as a checkbox will face adoption friction; those embedding privacy-by-design and clear governance models will reduce procurement hesitation.
Key Drivers Reshaping the Market
Underlying these challenges is a set of forces that are accelerating adoption and redefining what “smart PPE” must deliver to justify procurement budgets.
Technology Innovation Moving From Detection to Prediction
The technology stack is shifting along a clear trajectory: from passive monitoring toward predictive and context-aware capability. Early-generation devices excelled at logging falls, man-down events, exposure excursions, or location drift. The next wave integrates onboard analytics and tighter sensor fusion so that devices can flag deteriorating conditions before they become incidents. In practice, this means combining heart-rate variability, motion signatures, environmental gas readings, and site-specific hazard maps into a single risk signal. Suppliers that operationalized this shift in mid-2025 have shown how predictive safety analytics can move the conversation from incident response to proactive intervention.
Worldwide Military Wearable Market
Equally important is the maturation of PPE-adjacent electronics. Miniaturized inertial sensors, improved low-power radios, and more robust enclosure designs are allowing manufacturers to embed intelligence without compromising the primary protective function of helmets, vests, gloves, and belts. The commercial implication is significant: value is migrating from the physical shell toward the sensing and analytics layer. That migration changes product economics, service models, and upgrade cycles.
Policy and Standards as Adoption Accelerators
Regulation and standardization are no longer external constraints to be managed; they are becoming adoption accelerators. Occupational safety expectations increasingly mandate hazard detection and personal protective equipment suited to modern site risks. At the same time, occupational health and safety management frameworks are evolving to treat connected monitoring as a legitimate input for risk control and continuous improvement. When structured correctly, these expectations reduce the burden of internal justification for adoption. Safety leadership can point to external baselines for equipment performance, interoperability, and data governance.
Certification requirements also shape market access. Wireless construction wearables must clear regulatory hurdles around electromagnetic compatibility to coexist with radios, signaling systems, and dense equipment fleets on active sites. Meanwhile, biometric and location data collection invites consent and privacy obligations, particularly across European markets. The firms that design for these requirements from the outset are shortening procurement cycles and reducing legal review friction.
PW Consulting
Demand-Side Shifts: Workforce, Liability, and Site Complexity
The demand picture is being rewritten by three operational pressures. First, labor dynamics continue to strain site productivity. Skills shortages, turnover, and an aging workforce elevate the cost of preventable injuries and downtime. Smart wearables directly address this by reducing exposure to high-risk behaviors and by improving situational awareness for both workers and supervisors. Second, liability and insurance expectations are becoming more data-driven. Insurers and risk managers increasingly look for evidence that site operators are actively monitoring conditions, enforcing protocols, and responding faster to incidents. Connected wearables provide auditable signals that can strengthen risk profiles. Third, construction sites are growing more complex, with concurrent trades, tighter schedules, and tighter safety perimeters. In that environment, knowing where people are, whether they have taken a fall, and whether environmental thresholds are being breached becomes a coordination tool, not just a safety tool.
Supply-Side and Cost Structure Evolution
On the supply side, the economics of smart wearables are normalizing as sensors, connectivity modules, and rugged enclosures move down the cost curve. Yet the more important shift is in total cost of ownership. Procurement teams are increasingly evaluating devices through the lens of integration costs, maintenance downtime, battery replacement logistics, and training burden rather than sticker price alone. That perspective favors designs that minimize site friction: longer practical runtime, simpler charging routines, durable components that reduce failure rates, and firmware that can be updated without pulling devices out of service. It also favors vendors that can document reliability under harsh conditions, since failure in a safety-critical device has consequences far beyond warranty claims.
Another evolving dynamic is the relationship between hardware and software. As more devices feed into site platforms, the marginal value of a unit rises when it interoperates smoothly with scheduling, safety incident management, and field coordination tools. That creates an incentive for partnerships and platform-level integration rather than purely device-level competition.
Competitive Landscape and the Logic of Differentiation
The current market is shaped by a mix of specialized wearable firms, industrial safety incumbents, and large electronics and industrial groups applying their sensor and manufacturing expertise to construction contexts. The strategic positions vary, but a few patterns are clear.
Differentiated Positions Across the Field
Several companies have built identities around specific use cases rather than broad commodity wearables. One U.S.-based firm has focused on connected hard hats that combine vital-sign monitoring, environmental hazard detection, and lone-worker protection, recently extending the concept with onboard predictive analytics for proactive risk flagging. Another U.S. player has concentrated on a rugged wearable tag that tracks location, fall events, and impact signals, with strong emphasis on integrating those outputs into safety management workflows. A UK supplier has carved out a clear niche in lone-worker protection, pairing duress alarms, no-motion detection, and GPS tracking for environments where personnel may operate in isolation.
On the industrial PPE side, a major gas detection and safety technology provider has extended its connected portfolio into construction-relevant monitoring, leveraging brand trust in hazardous-environment sensing. A large diversified materials and safety company has advanced connected welding helmets and PPE that embed arc-flash detection and worker health monitoring, including recent certification-aligned updates for construction-grade protection. Further along the value chain, a South Korean manufacturer has emphasized smart helmets with IoT sensors for fall detection, fatigue monitoring, and environmental hazard alerts, while a Japanese industrial group has focused on wearable safety devices such as positioning and fall-prevention belts for site coordination.
What separates these players is not the presence of sensors alone, but the clarity of the operational problem they solve and the strength of their integration story. A device that addresses a well-scoped risk and slots neatly into existing site processes tends to gain faster traction than a generic multi-feature offering with weak workflow fit.
Recent Moves That Signal Where Value Is Being Built
Three recent developments illustrate how the field is evolving. A connected hard-hat supplier extended its platform with AI-driven predictive safety analytics designed to turn continuous site data into earlier risk intervention. A wearable tracking provider announced deeper integration with a widely used construction management platform, reinforcing the idea that device value multiplies when it feeds into project execution systems. A large PPE and welding-helmet manufacturer updated a flagship connected helmet to align with recognized construction safety standards, signaling that regulatory alignment remains a commercialization prerequisite as much as a technical specification.
Beyond these specific moves, the broader pattern is a shift toward ecosystems. Vendors are increasingly judged on how well their devices connect with site safety platforms, incident management tools, and field coordination workflows. That reality is reshaping competitive advantage: hardware quality still matters, but interoperability, data governance, and platform relationships are becoming the sharper differentiators.
Consolidation, Fragmentation, and the Opening for New Entrants
The market structure suggests room for both consolidation and targeted fragmentation. Moderate concentration among leading players leaves substantial opportunity for larger safety, connectivity, or industrial hardware firms to acquire specialized capabilities and accelerate platform play. At the same time, fragmentation persists at the application layer, where niche providers can thrive by solving narrow, high-value problems exceptionally well, such as lone-worker protection in remote environments or fatigue monitoring in continuous-shift operations.
New entrants face a meaningful barrier in rugged validation and site adoption, but the barrier is not insurmountable if they enter with a tightly defined use case, strong regulatory posture, and a plan for platform interoperability. The more dangerous strategic mistake is entering as a generic device maker without a clear path to data use, consent management, and integration. In a market where procurement teams care deeply about total cost of ownership and operational fit, the winners will be those who can demonstrate reliability in the field and value in the workflow.
Forward Outlook: Three Trends to Watch (2026–2032)
The next several years will likely be defined by the transition from device adoption to system-level value creation. Three trends stand out.
Predictive and context-aware safety becomes the baseline expectation. As sensor fusion and onboard analytics mature, the market will increasingly reward devices that can anticipate risk rather than merely log it. This trend will shift procurement conversations toward accuracy, false-alarm management, and response integration. The commercial opportunity lies in combining wearable data with site schedules, environmental inputs, and incident history to create actionable risk views. The uncertainty is in operational overload: if predictive signals are noisy or poorly prioritized, adoption can stall regardless of technical sophistication.
Platform interoperability becomes a commercial prerequisite. Construction firms are unlikely to build entirely new data ecosystems around wearables. They will expect devices to connect cleanly with safety management, field coordination, and project controls tools. This creates a durable advantage for suppliers that invest early in integration pathways and data-export flexibility. The risk is fragmentation of integration standards, which could raise implementation costs and slow procurement if buyers must manage multiple bespoke connections across vendors.
Regulatory and privacy expectations become a competitive filter. Compliance around emissions, equipment performance, and biometric data handling will continue to harden. Organizations that build consent workflows, data minimization, and clear retention policies into their products will reduce deployment friction. Those that treat privacy and certification as afterthoughts will face increasing procurement resistance, particularly in multi-jurisdiction operations. The commercial upside is that well-governed products can become preferred choices for risk-averse buyers, turning compliance into differentiation rather than cost.
Together, these trends point to a market where success is less about selling more hardware and more about enabling safer, faster, better-coordinated site operations. That shift opens opportunities for product-led service models, analytics add-ons, integration partnerships, and subscription-style support that reduces the operational burden on contractors.
Strategic Recommendations for Decision-Makers
For manufacturers and product developers, the priority is to anchor innovation in operational reality. Design for rugged runtime, simple charging, and durable construction first; then layer predictive analytics and integration capabilities that solve a clearly defined site problem. Validation under harsh conditions and transparent data governance should be treated as core product features rather than compliance extras.
For investors, the most compelling value creation will likely come from firms that combine reliable hardware with defensible data workflows and platform relationships. Evaluate potential targets and partnerships not only on sensor count or feature breadth, but on site adoption likelihood, integration readiness, and the ability to reduce total cost of ownership for contractors. Look particularly closely at companies that can demonstrate repeatable deployment patterns in complex, multi-trade environments.
For procurement and construction operators, the practical path is to treat smart wearables as part of a site intelligence strategy rather than a safety-equipment purchase in isolation. Prioritize devices that integrate with existing safety management and field coordination tools, that have credible field durability, and that provide clear data-use and consent frameworks. Pilot in high-value risk scenarios where faster detection or better coordination has measurable impact, then scale based on operational evidence rather than feature lists.
Detailed segmentation data, regional revenue breakdowns, product-type splits, connectivity preferences, company-level profiles, and scenario-based forecasts can sharpen these decisions considerably. Readers seeking a deeper, numbers-backed view of growth corridors, competitive positioning, and tailored strategic options can review the full PW Consulting report, which compiles the underlying market sizing, segmentation, and company intelligence behind the trends outlined here.
For detailed analysis of this topic, please visit the official page: Worldwide Construction Smart Wearable Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Flexible Intermediate Bulk Containers Market: Why 6.15% CAGR Reshapes Demand by 2032
By pmarketresearch, 2026-09-18
Navigating the Global Flexible Intermediate Bulk Containers Market: Strategic Shifts and Commercial Opportunities Through 2032
Market Landscape and Critical Inflection Points
The worldwide flexible intermediate bulk containers (FIBC) market has demonstrated resilient growth, expanding from approximately $4.6 billion in 2020 to an estimated $6.2 billion in 2025. This trajectory reflects a compound annual growth rate of 6.15%, projecting the market to surpass $9.4 billion by 2032. The steady expansion underscores FIBCs' entrenched role in bulk material logistics, bridging the gap between rigid containers and loose bulk handling while offering cost efficiency, transport optimization, and adaptable load capacities.
Despite the upward baseline, the industry stands at a structural crossroads. The first challenge lies in raw material price volatility and supply chain fragility. Woven polypropylene remains the dominant fabrication material, capturing roughly 78 percent of volume share. However, regional pricing divergences have intensified. North American polypropylene prices climbed to $1.43 per kilogram in early 2026, marking a 20.2 percent increase, while European markets faced steeper pressure at $2.1 per kilogram. Such cost asymmetry compresses margins for manufacturers heavily reliant on virgin resin and complicates procurement planning for end-users operating across multiple geographies.
The second inflection point is regulatory tightening around circularity and extended producer responsibility. The European Union's Packaging and Packaging Waste Regulation, effective from February 2025 and applicable from August 2026, mandates EPR schemes with fees directly modulated by recyclability performance. This legislation extends to plastic-based packaging, including FIBCs, compelling manufacturers and brand owners to rethink design-for-recycling, material traceability, and end-of-life management. Companies that treat compliance as a checkbox risk higher fee exposure, while those embedding circularity into product architecture can translate regulatory pressure into cost advantages and procurement preference.
A third challenge emerges from trade policy friction. US imports of bulk bags under HTS Code 6305.32.0010 currently encounter approximately 8.4 percent tariffs alongside ancillary fees. This framework reshapes regional cost competitiveness, incentivizing localized production, supply chain dual-sourcing, or design modifications that reduce import dependency. For multinational buyers and manufacturers, tariff exposure is no longer a peripheral concern but a core variable influencing capacity siting, inventory strategy, and product mix decisions.
Core Drivers Reshaping the FIBC Value Chain
Technological Innovation in Material Performance and Circular Design
Material engineering continues to redefine what FIBCs can deliver beyond conventional load containment. The adoption of advanced woven polypropylene structures, reinforced lifting loops, and multi-layer barrier liners is addressing longstanding performance gaps in food safety, pharmaceutical compliance, and chemical containment. Recent product introductions illustrate how performance and circularity are converging rather than competing. In January 2025, Greif introduced the GCUBE Flex intermediate bulk container, featuring an enhanced aseptic liner and a two-layer polypropylene construction tailored for food and pharmaceutical handling. This launch signals a broader industry direction: FIBCs are evolving from commoditized bulk sacks into engineered packaging systems that meet stringent hygiene, traceability, and contamination-control requirements.
Simultaneously, recycled-content engineering is moving from pilot initiatives to commercial scale. Packem Umasree commissioned India's first fully integrated bottle-to-bag rPET FIBC manufacturing plant in Ahmedabad in 2025, achieving a capacity of 3.5 million bags. This facility demonstrates that post-consumer recycled inputs can be integrated into FIBC production at meaningful volumes without sacrificing structural integrity. Such capability expansion is critical because it creates upstream supply of recycled resin tailored to bulk bag specifications, reducing reliance on virgin resin price swings and enabling manufacturers to offer lower-carbon alternatives to procurement teams under internal or regulatory sustainability mandates.
Regulatory Momentum Accelerating Circular Economy Adoption
Policy is no longer a distant backdrop; it is actively reallocating competitive advantage. The EU PPWR's fee modulation based on recyclability performance creates a financial gradient that rewards designs with higher recycled content, simpler material assemblies, and documented end-of-life pathways. This regulatory logic is reinforced by growing market expectations that packaging should incorporate post-consumer recycled material wherever technically feasible. The result is a dual pressure: manufacturers must redesign products for recyclability while simultaneously securing reliable recycled feedstock streams.
Market reactions confirm this shift. Gravis launched the Sustainabulk 100 percent recycled PET FIBC in May 2025, claiming up to a 70 percent carbon footprint reduction compared with virgin polypropylene bags. This product positioning reflects an emerging commercial logic in which environmental performance becomes a procurement differentiator, particularly for chemical, food, and pharmaceutical users who must report on lifecycle emissions or comply with customer sustainability clauses. For producers, the opportunity lies in certifying recyclability claims, standardizing recycled-content grades, and aligning product documentation with audit requirements from downstream buyers.
Demand-Side Transformation in Application Sectors
End-user behavior is shifting from viewing FIBCs as interchangeable transport units to selecting them based on sector-specific performance, compliance, and sustainability criteria. Chemicals remain a major application area, driven by the need for reliable bulk handling of dry flowable materials, powders, and granular substances. Food and pharmaceutical demand is intensifying around contamination control, liner integrity, and inspection-friendly designs. Agriculture and construction continue to generate steady volume, yet even these traditional segments increasingly evaluate bulk bag suppliers on total cost of ownership, delivery reliability, and environmental footprint.
Worldwide Industrial Flexible Hose Market
This segmentation is reshaping procurement behavior. Buyers are more willing to pay for engineered features such as Type C and Type D conductive configurations, custom spout and top designs, or aseptic liners when those features reduce operational risk, improve handling efficiency, or satisfy regulatory expectations. For manufacturers, the implication is clear: competitive differentiation is migrating from unit price toward specification reliability, compliance documentation, and lifecycle performance. Suppliers that can articulate application-specific value and evidence-based sustainability attributes are gaining preference in tenders and long-term supply agreements.
Cost Structure Reconfiguration and Regional Production Dynamics
Cost structures are being recalibrated by the intersection of raw material inflation, energy differentials, and trade policy. Polypropylene price divergence between North America and Europe creates uneven cost bases across manufacturers, prompting some to optimize production footprints, adjust pricing mechanisms, or shift toward blended or recycled resin mixes where feasible. At the same time, tariff exposure on bulk bag imports into the United States encourages regional capacity expansion or nearshore sourcing strategies. Several US-based manufacturers have emphasized standard and custom FIBC production with domestic or regional supply chains, aligning cost predictability with faster fulfillment and lower logistics risk.
For the broader market, this dynamic favors players that can balance scale with flexibility. Large producers with integrated recycling loops, diversified resin sourcing, and multi-region manufacturing can better absorb input volatility and tariff effects. Smaller or highly specialized manufacturers can compete by offering rapid customization, food-grade certifications, and application-engineered solutions that larger generalist players may standardize away. The net effect is a market in which cost leadership and differentiation are increasingly interdependent rather than mutually exclusive.
Competitive Landscape and Strategic Positioning
The FIBC industry remains moderately fragmented, with a five-firm concentration ratio of about 24 percent and a three-firm ratio near 18 percent. This fragmentation provides room for regional specialists, application-focused manufacturers, and export-oriented producers, but it also intensifies the need for clear strategic positioning. Leading companies are not competing solely on bag specifications; they are building value through service architecture, recycling infrastructure, and sector-specific credibility.
Greif exemplifies a strategy centered on circular reconditioning and engineered product platforms. By reporting the reconditioning or recycling of over 4.5 million containers across its global industrial packaging network in September 2025, Greif has reinforced a circular economy narrative that links reuse capability with cost recovery and sustainability metrics. Combined with the GCUBE Flex launch targeting food and pharmaceutical performance, this dual emphasis on circularity and specialized containment illustrates how incumbents can defend scale while moving up the value curve. Berry Global maintains a broad flexible packaging portfolio, leveraging durable woven polypropylene designs across industrial, chemical, food, and construction segments. Its breadth supports cross-segment supply resilience, though it also requires disciplined specification management to avoid commoditization.
FIBC (Flexible Intermediate Bulk Container) Market
Several producers are building differentiation through application focus and manufacturing localization. Conitex Sonoco emphasizes US-based BulkSak and FIBC production, offering standard, custom, food-grade, and on-demand inventory programs that appeal to industrial buyers prioritizing responsiveness and compliance. LC Packaging International BV anchors its positioning in European and global distribution with standard and customized bulk bags, benefiting from proximity to markets facing stringent recyclability expectations. Global-Pak Inc. and Palmetto Industries International Inc. concentrate on high-performance woven polypropylene containers and tailored top and spout configurations for industrial use, respectively, reflecting demand for load stability and handling efficiency. JohnPac, LLC extends its differentiation across the full FIBC specification range, including 4-panel, baffle, circular, food-grade, Type C, and Type D bags, enabling customers to source multiple technical variants from a single supplier relationship.
Export-oriented manufacturers from India and Turkey are expanding their relevance by combining cost efficiency with growing specification capabilities. Rishi FIBC Solutions Pvt. Ltd. serves chemical, food, pharmaceutical, and agricultural applications with an export focus, while Isbir Sentetik Dokuma Sanayi A.S. produces woven polypropylene fabrics and FIBCs with significant export-oriented production. These players benefit from relative input cost advantages and scale flexibility, though sustained competitiveness depends on consistent quality, certification reliability, and the ability to meet increasingly demanding recycled-content and traceability expectations. Codefine's emphasis on sustainable options, including recycled PET bulk bags, reflects another competitive vector: offering lower-carbon alternatives within a standard product portfolio. In the United States, manufacturers such as Bulk Lift International LLC, Langston Companies Inc., Halsted Corporation, and Dewitt Company maintain specialized bulk bag production for industrial, chemical, food, and construction markets, often competing on customization, capacity reliability, and regional fulfillment speed.
The competitive outlook points toward selective consolidation in mature regions alongside continued emergence of niche specialists. Larger players may pursue acquisitions to secure recycling infrastructure, geographic coverage, or application expertise. Mid-tier manufacturers may differentiate by depth in food-grade, conductive, or aseptic solutions. New entrants are most likely to succeed where they solve a specific procurement pain point: verified recycled content, improved liner performance, faster custom turnaround, or documented compliance with evolving EPR requirements. The market is moving toward a landscape in which scale, circular capability, and application credibility must be managed together rather than in isolation.
Forward Outlook: Trends, Opportunities, and Risks
Over the next three to five years, the FIBC market is likely to be shaped by three interconnected trends. First, circular design and recycled-content integration will shift from optional features to baseline expectations in many procurement categories. As EPR fee modulation takes effect and customer sustainability requirements deepen, manufacturers that can reliably supply certified recycled-content FIBCs and document recyclability performance will gain preference in competitive bidding. This creates opportunities for producers with access to rPET or post-consumer recycled polypropylene streams, as well as for service models that combine bulk bag supply with reconditioning or return logistics.
Second, regulatory and tariff divergence will accelerate regionalized supply chains and segmented product strategies. The EU PPWR implementation timeline and ongoing US import duties make it increasingly important to align production footprints, resin sourcing, and product specifications with destination-market requirements. Manufacturers that can offer region-appropriate grades, adjusted recycled-content mixes, and transparent compliance documentation will reduce friction for multinational buyers and protect margin stability in volatile input environments. This trend favors suppliers with multi-region capacity or strong partner networks that can localize fulfillment without sacrificing specification consistency.
Third, application-engineered FIBCs will capture a growing share of value as buyers prioritize performance reliability and compliance over lowest unit cost. Food and pharmaceutical segments will continue to drive demand for aseptic liners, contamination-control features, and inspection-friendly designs. Chemical and construction sectors will reward durable woven structures, tailored lifting configurations, and consistent load integrity. The commercial opportunity lies in defining clear grade families, linking them to documented performance attributes, and supporting procurement teams with specification guidance that reduces risk and simplifies vendor consolidation. At the same time, uncertainty persists around resin price trajectories, the pace of recycled feedstock availability, and the practical interpretation of EPR fee modulation across jurisdictions. Companies that monitor these variables closely and build flexible sourcing and product architectures will be better positioned to manage downside risk while capturing upside from sustainability-driven demand.
Strategic Actions for Decision Makers
For FIBC manufacturers, the priority is to translate circularity and application performance into repeatable product architectures rather than isolated launches. Establish clear recycled-content grades, secure traceable feedstock arrangements, and align product documentation with EPR and customer audit expectations. Where feasible, integrate reconditioning or return pathways that convert sustainability claims into operational value and improve total cost positioning. At the same time, protect margin resilience by diversifying resin sourcing and aligning production footprints with the regulatory and tariff realities of key destination markets.
PW Consulting
For investors, the most attractive opportunities are likely in companies that combine scale with circular capability or that occupy strong positions in high-specification segments such as food-grade, pharmaceutical, and conductive FIBCs. Due diligence should focus on recycled-content supply security, certification integrity, regional cost structures, and exposure to tariff or EPR-related cost shifts. Capital allocation should favor businesses that can demonstrate sustainable differentiation beyond commodity bag pricing, particularly where sustainability attributes are already influencing procurement decisions.
For procurement and supply chain leaders, the strategic task is to move beyond unit-price comparison toward total-cost and risk-based evaluation. Assess suppliers on specification reliability, compliance documentation, recycled-content options, and fulfillment consistency across regions. Where possible, consolidate categories around suppliers that can provide multiple FIBC types with clear performance grades and verified sustainability attributes, reducing vendor complexity while improving traceability. Procurement teams should also pressure-test supply continuity plans against raw material volatility and tariff exposure, ensuring that lower headline pricing does not obscure logistics risk or future compliance costs.
For decision makers seeking to translate these dynamics into actionable plans, detailed segmentation data, regional cost modeling, specification benchmarking, and supplier evaluation frameworks can materially accelerate strategy development. Access to granular market intelligence supports more precise capacity planning, product mix decisions, and procurement negotiations, particularly in a market where regulatory timelines, resin pricing, and circular-content expectations are changing simultaneously.
For detailed analysis of this topic, please visit the official page: Worldwide Flexible Intermediate Bulk Containers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Worldwide Aluminium Tert Butoxide Market: 5.48% CAGR and Regional Shifts
By pmarketresearch, 2026-09-18
Navigating the Aluminium Tert-Butoxide Market: Strategic Trends and Commercial Opportunities Through 2032
The global market for aluminium tert-butoxide has entered a period of structured expansion, driven by its indispensable role as a catalyst and reagent in high-performance chemical synthesis. Valued at approximately 112.55 million USD in the base year, the market has demonstrated steady growth from its 2020 baseline of 86.25 million, reflecting consistent demand pull across industrial and scientific applications. Projections indicate a compound annual growth rate of 5.48 percent, positioning the sector to reach 163.51 million USD by 2032. This trajectory is not merely a function of incremental volume increases; it represents a structural shift toward specialized organometallic intermediates that enable precision manufacturing in emerging technology sectors. The convergence of advanced materials development, regulatory tightening around legacy chemical processes, and the globalization of specialty chemical supply chains has created a favorable environment for sustained commercial activity.
Despite the favorable growth outlook, industry participants are navigating a complex landscape defined by cost volatility, concentration dynamics, and evolving application requirements. One of the most pressing challenges lies in the sensitivity of production economics to raw material pricing. The cost structure for aluminium alkoxides is inherently tied to upstream inputs, and recent market movements have introduced significant uncertainty into margin forecasting. Simultaneously, the market exhibits a moderate-to-high degree of concentration, with the top three participants capturing over half of total industry revenue and the top five controlling nearly seventy percent. Such concentration creates both stability for established players and barriers for new entrants, while also raising questions about supply resilience and pricing power in an increasingly fragmented demand environment. A second critical juncture involves the divergence in purity requirements across end-use sectors. High-purity grades now dominate commercial activity, reflecting the needs of advanced electronics and precision catalysis, while standard grades maintain relevance in broader industrial applications. This bifurcation requires manufacturers to maintain distinct production protocols, quality assurance frameworks, and inventory strategies, complicating operational scaling.
The third challenge centers on geographic demand distribution and the corresponding need for localized supply capabilities. While demand is dispersed across multiple regions, the Asia Pacific corridor continues to account for the largest share of commercial activity, reflecting both manufacturing density and accelerating industrial modernization. Europe and North America maintain substantial footholds, supported by established laboratory networks and specialized chemical synthesis ecosystems. Latin America and the Middle East and Africa represent smaller but growing nodes of activity, often tied to regional industrial initiatives and imported specialty chemical demand. This geographic footprint necessitates a nuanced approach to distribution, regulatory compliance, and customer engagement. Companies must balance centralized production efficiency with regional responsiveness, particularly as procurement teams increasingly prioritize supply reliability over pure cost minimization. The interplay between demand concentration, purity segmentation, and regional cost structures defines the current market reality and will shape competitive positioning in the years ahead.
Key Drivers: What Is Really Moving the Market
Technological innovation continues to serve as the primary engine of commercial expansion, particularly in the realm of catalytic precision and materials science. Aluminium tert-butoxide functions as a critical reagent in esterification, transesterification, and the synthesis of advanced polymers and fine chemicals. Recent advancements in process chemistry have amplified its utility, enabling more efficient reaction pathways and reduced byproduct formation. In the semiconductor and electronics domain, the compound's role in precursor chemistry and surface treatment processes has gained renewed attention as device architectures become increasingly complex. Manufacturers that invest in controlled-atmosphere handling, particle-size consistency, and trace-metal reduction are capturing premium positioning, particularly among customers operating at the intersection of research and pilot-scale production. The shift toward continuous flow chemistry and automated synthesis platforms is also reshaping demand patterns, favoring suppliers capable of delivering consistent batch-to-batch performance and technical documentation that aligns with modern quality management expectations.
Regulatory and policy environments are simultaneously reweighting the competitive landscape, particularly around chemical safety, environmental compliance, and procurement transparency. Stricter handling requirements for organometallic compounds have elevated the importance of supplier documentation, safety data alignment, and packaging integrity. In several major markets, procurement frameworks now prioritize vendors that can demonstrate robust traceability, controlled storage specifications, and compliance with evolving occupational exposure standards. These requirements do not merely add administrative burden; they function as de facto barriers to entry that reward established players with mature quality systems and disciplined distribution networks. At the same time, sustainability mandates are influencing formulation choices across downstream industries, indirectly supporting demand for reagents that enable cleaner reaction pathways and reduced waste streams. The policy environment is therefore not simply a constraint but a catalyst for differentiation, favoring companies that integrate compliance into their core operating model rather than treating it as an afterthought.
PW Consulting
Supply-side economics present a further layer of strategic complexity. The cost structure for aluminium tert-butoxide is highly responsive to fluctuations in aluminium-based precursors and alcohol feedstocks. Recent market data underscores this sensitivity: aluminium metal prices reached 3,484.20 USD per tonne in late April 2026, representing a year-over-year increase of 44.45 percent and directly pressuring the production economics of aluminium alkoxides. In parallel, isobutanol, a key alcohol feedstock for tert-butoxide synthesis, traded in the range of 1,640 to 1,750 USD per tonne in Northwest European FOB terms during the same period. Aluminium oxide prices displayed notable regional dispersion, ranging from 0.42 USD per kilogram in Northeast Asia to 0.57 USD per kilogram in India, reflecting divergent local cost environments for aluminium-based precursors. These dynamics create a volatile input environment that rewards manufacturers with flexible sourcing strategies, regional production footprints, and the ability to pass through cost adjustments without sacrificing market share. Companies that rely on single-source procurement or rigid pricing models face heightened margin compression risk, particularly during periods of rapid commodity repricing.
Demand-side behavior is evolving in tandem with these supply and regulatory forces. Procurement teams across chemical synthesis, electronics, and pharmaceutical intermediary sectors are increasingly prioritizing supply reliability, technical support, and format flexibility over lowest-unit-cost acquisition. The compound is consumed across a broad application spectrum, with chemical synthesis and catalysis representing the largest commercial share, followed closely by semiconductor and electronics applications. Pharmaceutical intermediates and specialized industrial uses account for the remainder, each demanding different packaging scales, purity assurances, and delivery cadences. This diversification means that suppliers must operate multi-tiered service models, accommodating both catalog-grade research purchases and bulk industrial deliveries. Customers are also showing greater willingness to engage with suppliers that offer clear documentation, predictable lead times, and responsive technical guidance, particularly when qualifying materials for new production lines or scaling laboratory processes into pilot operations.
Competitive Landscape and the Strategies Defining Leadership
The competitive environment for aluminium tert-butoxide is characterized by a mix of global specialty chemical suppliers, regional distributors, and niche organometallic specialists. American Elements, headquartered in Los Angeles, California, has positioned itself around a broad organometallic portfolio, offering aluminium tert-butoxide in multiple purity grades for non-aqueous applications that span solar energy and water treatment. Its strategic emphasis on application breadth and product availability allows it to serve customers who require consistent supply across varied technical contexts. Ereztech, operating in the United States, focuses on manufacturing and selling aluminium(III) tert-butoxide in both small and bulk volumes, with packaging options that include glass ampules, bottles, and metal bubblers. This flexibility in pack size and delivery format addresses a practical pain point for laboratory and pilot-scale users who need controlled quantities without compromising handling safety.
TCI Chemicals, based in Japan with U.S. operations in Philadelphia, offers aluminium tert-butoxide with purity exceeding 98 percent for laboratory and research use, available in catalog quantities with regional stocking. Its positioning reflects a strong emphasis on research-grade reliability and logistical proximity to scientific customers. Sigma-Aldrich, now part of Merck, supplies technical-grade aluminium-tri-tert-butoxide for chemical synthesis and reagent applications, leveraging a globally recognized brand and extensive distribution infrastructure. Thermo Scientific Chemicals, formerly Alfa Aesar, provides aluminium tert-butoxide at 97 percent purity in various pack sizes, catering to both laboratory and industrial reagent needs with an emphasis on standardized quality and broad catalog availability. ProChem, Inc., operating in the United States, manufactures and supplies aluminium t-butoxide as part of its broader specialty chemical product line, appealing to customers who value integrated sourcing and established industrial relationships.
In the Asia Pacific corridor, Sinochem Nanjing Corporation functions as an industrial supplier and factory manufacturer, offering aluminium tert-butoxide in wholesale quantities and reflecting the region's emphasis on scale and cost-competitive supply. Alfa Chemistry, based in the United States, provides aluminium tert-butoxide for experimental and research use with supporting documentation, targeting customers who prioritize traceability and technical clarity. These companies collectively illustrate a market where differentiation is achieved through a combination of purity assurance, packaging flexibility, regional availability, and application-specific support rather than through price competition alone.
The strategic positioning of leading players reveals several recurring advantages. First, companies that maintain distinct quality tiers and clear documentation protocols are better equipped to serve the divergent needs of research, pilot, and industrial customers. Second, suppliers with flexible packaging and delivery options reduce friction for buyers who require precise quantities or specialized handling formats. Third, organizations that combine manufacturing capability with reliable distribution networks are better positioned to manage supply continuity during periods of raw material volatility. The market concentration pattern, with the top three firms holding over half of revenue and the top five controlling nearly seventy percent, suggests that scale, brand trust, and compliance maturity remain powerful moats. At the same time, the presence of multiple regional and specialty suppliers indicates room for targeted differentiation, particularly for companies that can serve niche purity requirements or offer responsive local logistics.
Looking ahead, the competitive landscape is likely to evolve through selective consolidation, regional supply network expansion, and increased emphasis on technical service. Larger players may pursue acquisitions or partnerships to broaden purity-grade coverage, strengthen geographic reach, or integrate downstream application support. Mid-tier and regional suppliers may differentiate by offering faster turnaround, customized documentation, or specialized handling for sensitive applications. New entrants will face the dual challenge of meeting stringent quality expectations while competing against established distribution channels and customer relationships. The net effect is a market that rewards operational discipline, technical credibility, and customer-centric flexibility over undifferentiated volume competition.
Forward View: Three Trends Shaping the Next Three to Five Years
The first major trend is the continued elevation of purity and consistency as commercial imperatives. As semiconductor, electronics, and advanced catalysis applications mature, downstream customers will increasingly view material variability as a process risk rather than a tolerable compromise. Suppliers that invest in tighter control over trace impurities, moisture sensitivity, and particle uniformity will capture disproportionate value, particularly in applications where reagent performance directly influences yield, device reliability, or regulatory acceptance. This trend will likely accelerate the separation between premium-grade supply chains and standard-grade commodity channels, with margin differentiation widening accordingly.
The second trend is the growing importance of supply chain resilience and regional responsiveness. Given the sensitivity of input costs and the geographic dispersion of demand, procurement teams will continue to favor suppliers that can demonstrate multi-source procurement, regional inventory positioning, and transparent lead-time management. Companies that build flexible sourcing arrangements and maintain buffer strategies for critical feedstocks will be better positioned to navigate commodity repricing events without disrupting customer commitments. This resilience will become a competitive differentiator in its own right, particularly as customers seek to reduce exposure to single-point supply failures.
The third trend involves the expanding intersection of technical service and commercial growth. As applications become more specialized, customers will expect suppliers to provide not only material but also applicable documentation, handling guidance, and qualification support. Suppliers that can align their commercial offerings with the practical needs of research, pilot scaling, and industrial production will build deeper customer relationships and reduce churn. At the same time, potential risks remain. Raw material volatility, regulatory changes around organometallic handling, and shifts in downstream procurement budgets could introduce periodic demand softness or margin pressure. Companies that treat these factors as manageable variables rather than external shocks will be better prepared to sustain growth through cyclical disruptions.
Worldwide Aluminum Alkyls Market
Actionable Guidance for Decision-Makers
For manufacturers and suppliers, the priority is to align production and quality systems with the diverging requirements of high-purity and standard-grade segments while maintaining cost flexibility in the face of input volatility. Diversifying feedstock sourcing, regionalizing inventory where feasible, and investing in documentation and handling protocols will strengthen both margin resilience and customer trust. Differentiation should focus on reliability, technical support, and format flexibility rather than on price alone, particularly as downstream customers increasingly value supply continuity and qualification speed.
For investors, the market presents opportunities in companies with disciplined quality systems, flexible procurement models, and clear application-focused positioning. Attention should be directed toward suppliers that can demonstrate consistent performance across purity tiers, manage raw material exposure effectively, and serve high-growth application corridors without overextending into undifferentiated commodity competition. Due diligence should weigh not only current revenue profiles but also the ability to sustain supply reliability and technical credibility through periods of input cost fluctuation.
For procurement and supply chain leaders, the strategic focus should be on qualifying multiple capable suppliers, establishing clear purity and packaging requirements, and building contingency plans for feedstock-driven price movements. Engaging suppliers that offer transparent documentation, predictable lead times, and responsive technical support will reduce qualification risk and improve operational continuity. Evaluating total cost of ownership, including handling, storage, and qualification overhead, will yield better outcomes than focusing solely on unit price. Detailed segment-level data, regional cost structures, and customized procurement scenarios can further sharpen these decisions, and the full research report provides the granular breakdowns and scenario analysis needed to translate these strategic directions into specific operational plans.
Worldwide Aluminum Dimethyl Isopropoxide Market
For detailed analysis of this topic, please visit the official page: Worldwide Aluminium Tert Butoxide Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Worldwide Rodder Machine Market: Why 5.01% CAGR Rewires the $608M 2032 Outlook
By pmarketresearch, 2026-09-18
Strategic Trends and Commercial Opportunities in the Worldwide Rodder Machine Market
Market Overview and Core Challenges
The global rodder machine market has demonstrated steady expansion over the past half-decade, evolving from a mature, cyclical maintenance sector into a strategically significant equipment segment driven by aging infrastructure and operational efficiency mandates. Recent historical trajectories show consistent revenue growth, with the market surpassing initial estimates as municipalities and industrial operators prioritize mechanical cleaning over chemical or high-pressure alternatives. The compound annual growth rate through the mid-2030s is projected at approximately 5 percent, signaling a transition from flat, maintenance-only spending to more structured capital allocation cycles. This growth trajectory reflects not merely inflationary adjustments but a fundamental shift in how utility operators approach pipeline integrity, wastewater transport reliability, and underground utility access.
Despite the positive momentum, the industry navigates several structural friction points that will define competitive positioning over the next cycle. First, the sector faces a pronounced technological inflection point as municipalities and contractors increasingly evaluate battery-electric and autonomous-assisted rodding platforms. Traditional diesel-driven continuous and sectional rodder systems are being stress-tested by noise ordinances, indoor operating constraints, and evolving emissions standards in dense urban environments. Operators must balance the proven torque and runtime reliability of legacy powertrains against the operational advantages of zero-emission alternatives that demand new servicing protocols, battery lifecycle management, and higher upfront capital outlays.
Second, supply chain volatility in critical input materials directly pressures manufacturing economics and end-user pricing stability. Rodder frames, drive components, and transmission cables rely heavily on steel and aluminum, meaning commodity price swings translate rapidly into cost-of-goods uncertainty. Manufacturers with lean inventory practices or exposure to single-source component suppliers face margin compression during procurement disruptions, while end customers encounter elongated delivery timelines and unpredictable total cost of ownership calculations. This dynamic is forcing both OEMs and procurement departments to reevaluate supplier diversification, long-term service agreements, and equipment financing models.
Third, the market is experiencing a geographic and application-level divergence that complicates consolidated go-to-market strategies. Infrastructure renewal programs in developed regions emphasize compliance-driven preventive maintenance and inspection-linked cleaning cycles, whereas rapidly urbanizing regions focus on capacity expansion and new utility network deployment. Simultaneously, end-use demand patterns are shifting: routine municipal sewer cleaning remains the largest consumption driver, but specialized industrial pipe maintenance and telecommunications ducting workflows are adopting lighter, precision-oriented rodding configurations. Navigating this divergence requires equipment providers and service operators to avoid one-size-fits-all positioning and instead align product portfolios, distribution partnerships, and service capabilities with distinct operational realities.
Key Demand Drivers Shaping Market Direction
Technological Innovation and Platform Evolution
The most consequential driver reshaping competitive expectations is the ongoing transformation of rodder machine architecture. Continuous rodders continue to dominate heavy-duty mainline applications because their uninterrupted cable path delivers consistent torque penetration over extended runs, making them indispensable for bulk debris removal, root cutting, and silt disruption in large-diameter lines. At the same time, sectional rodder platforms retain a strong footprint in scenarios requiring maneuverability, tool interchangeability, and targeted cleaning in constrained access points or shorter pipe segments. The real strategic shift lies in how power delivery, control systems, and cable management are being redesigned. Manufacturers are integrating torque feedback logic, improved drum tensioning, and ergonomic operator controls to reduce fatigue and improve cleaning consistency across varying soil and obstruction conditions. These refinements are not cosmetic; they directly affect cycle time, repeat-clearing incidents, and equipment utilization rates, which are critical metrics for municipal departments managing large route schedules and contractors billing by job efficiency.
Regulatory Pressure and Compliance-Driven Maintenance
Environmental and public health regulations are functioning as a powerful demand anchor, particularly in North America and Europe. Strict wastewater inspection mandates and sanitary sewer overflow prevention requirements are compelling municipalities to maintain more frequent cleaning and inspection cycles. In practice, this means rodding equipment is no longer treated as a discretionary repair tool but as part of a compliance-linked asset management strategy. On the European side, directives favoring non-invasive cleaning methods are accelerating adoption of precision rodder configurations that minimize pipe stress and reduce the need for excavation. The regulatory environment effectively sustains baseline demand while pushing operators toward equipment that can document performance, withstand inspection schedules, and operate within tighter environmental constraints. This creates a durable purchasing rationale even during budget compression cycles, because deferred cleaning can trigger regulatory penalties and higher remediation costs downstream.
Demand-Side Behavior and Operational Priorities
End-user behavior is evolving as municipalities, industrial facilities, and telecommunications contractors recalibrate how they balance labor, downtime, and equipment flexibility. Municipal water and sewer departments are increasingly seeking equipment that can handle mixed debris profiles—stones, grit, sludge, and root intrusion—without switching between multiple specialized machines. This operational reality favors flexible drive configurations, durable cable systems, and tool kits that support rapid attachment changes. Industrial pipe maintenance teams are prioritizing machines capable of reaching longer runs and larger diameters with controlled feed force to avoid damaging sensitive process piping. Meanwhile, ducting and telecom contractors are leaning toward lightweight rodding and pulling systems that support tracer functions and conduit access without disrupting active service corridors. Across these segments, the common theme is predictable performance under variable operating conditions, which elevates the importance of machine reliability, service availability, and operator training support over pure purchase price.
Supply Chain Realities and Cost Structure Pressures
Manufacturing economics are being reshaped by material intensity and component complexity. Steel and aluminum remain foundational to rodder frames, reel structures, and cable assemblies, so raw material price fluctuations directly influence production costing and pricing stability. Beyond commodities, the broader supply chain context is encouraging manufacturers to reconsider sourcing strategies, inventory buffers, and aftermarket parts availability. Service networks are becoming a competitive differentiator because downtime during a peak cleaning season or an emergency blockage event carries disproportionate operational and reputational costs. This environment rewards manufacturers that can provide responsive parts logistics, clear maintenance intervals, and deployable field support. It also encourages fleet operators to evaluate total cost of ownership more carefully, weighing fuel or battery management costs, expected cable life, and servicing lead times rather than focusing solely on sticker price.
Competitive Landscape and Leading Strategies
The competitive field in the rodder machine market is shaped by a mix of established equipment manufacturers, specialized regional players, and emerging suppliers targeting adjacent cleaning and conduit workflows. Market concentration indicates that a handful of leading firms capture a meaningful share of revenue, yet the presence of multiple capable manufacturers suggests room for differentiation through product architecture, powertrain strategy, and service execution rather than pure scale. Leaders are not competing solely on machine size or maximum run length; they are competing on how well their platforms fit the operational environment of the buyer.
Strategic Positioning and Differentiation
Leading manufacturers are defining their advantage through targeted capability sets and clear end-user alignment. RIDGID, for example, has built recognition around heavy-duty sectional rodder systems designed for straight main line work in larger-diameter sewer and drain lines, emphasizing torque delivery, tool kit breadth, and suitability for municipal, institutional, and industrial applications. General Pipe Cleaners has reinforced its position through sectional drain cleaning machines engineered for tough clogs in long runs and larger pipes, with two-way operation supporting professional and municipal use cases. Electric Eel Manufacturing Company continues to serve professional, rental, and municipal markets with drum and continuous cable cleaning platforms that emphasize long-standing product familiarity and broad market accessibility. Sewer Equipment Co. of America positions its rodder series within a broader sewer cleaning lineup, highlighting mechanical rodding approaches that align with water-conserving operational priorities. Spartan Tool rounds out the field by providing rodding machines aimed at professional contractors and municipal users, competing on practical usability and service reach.
Diverging Product and Powertrain Strategies
TSE International illustrates how product strategy is responding to evolving operational constraints. The company continues to promote its diesel OK Champion S660 alongside the battery-electric S660E, positioning the electric variant as a quiet, emission-free option for sewer and conduit maintenance. This dual-track approach reflects a practical market reality: many fleets still require diesel horsepower for demanding heavy-duty work, while certain municipalities and enclosed-site operators increasingly value emission-free, low-noise alternatives that can also serve as complements or substitutes for vacuum truck deployments in specific workflows. The availability of a self-contained battery power source is not merely a product feature; it represents a strategic bet on the growing demand for operational flexibility in areas where noise, emissions, and site access restrictions influence equipment selection. Similarly, Hebei Sinta FRP Co., Ltd. demonstrates how international suppliers are expanding the competitive boundary by focusing on fiberglass duct rodders, cobra cable pullers, and traceable duct rodding accessories for cable laying and pipeline cleaning applications, broadening the competitive conversation beyond traditional sewer cleaning into utility and telecom ducting workflows.
Worldwide Shaper Machine Market
Market Evolution and Structural Shifts
The competitive landscape appears to be moving along two parallel tracks. On one track, established manufacturers are deepening their positions through product refinements, service coverage, and targeted municipal procurement engagement. On the other, new entrants and adjacent-market suppliers are introducing specialized configurations that blur the line between sewer rodding, conduit cleaning, and cable pulling. This combination of deepening incumbency and specialized encroachment is likely to increase segmentation intensity. Expect more emphasis on bundling equipment with accessory ecosystems, training, and service agreements, as well as greater competition around procurement responsiveness, as evidenced by recent municipal bidding activity for integrated truck-mounted rodder systems. Competitive advantage will increasingly belong to organizations that can align hardware, powertrain choice, parts logistics, and bid-ready specification support with the specific operational requirements of each buyer segment.
Forward Trends and Commercial Implications
Over the next three to five years, the rodder machine market is likely to be defined by a small number of intersecting trends that carry clear commercial implications. First, electrification and low-emission platform adoption will broaden beyond niche applications. Battery-electric rodders will continue to gain traction in urban environments, enclosed facilities, and jurisdictions with restrictive noise or emission policies. The commercial opportunity lies not simply in selling electric machines, but in developing battery management services, charging logistics guidance, and application-specific sizing expertise that help buyers avoid underpowered purchases or unrealistic runtime expectations. Manufacturers that bridge the gap between electric capability and real-world job conditions will capture a premium position in an increasingly segmented market.
Second, infrastructure spending and urbanization-driven utility expansion will sustain demand while shifting the purchase rationale toward lifecycle performance. As municipal wastewater networks, storm drain systems, and underground utility corridors receive renewed attention, rodding equipment will be evaluated through the lens of route efficiency, repeatability, and reduced repeat-clearing incidents. This trend favors suppliers and service providers that can demonstrate how machine design, cable durability, and operator ergonomics contribute to measurable operational outcomes. The upside for dealers and manufacturers is stronger aftermarket relevance: spare parts, cable replacement programs, and preventive maintenance contracts will gain importance as fleets look to stabilize uptime across seasonal demand peaks.
Third, procurement processes will become more specification-driven and integrated. Recent municipal bid activity for truck-mounted jet rodder platforms indicates that buyers increasingly view rodding capability as part of a broader vehicle and service configuration rather than an isolated tool purchase. This shift creates opportunities for equipment providers that can support bid documentation, performance specifications, and configuration flexibility tailored to specific debris profiles and line sizes. However, the same trend introduces uncertainty: budget timing, procurement lead times, and evolving municipal priority lists can delay purchase cycles, and commodity-driven cost pressure may complicate pricing commitments. Stakeholders that build flexibility into their supply planning and maintain clear communication around specification trade-offs will be better positioned to convert demand into closed deals.
Strategic Recommendations for Decision-Makers
For equipment manufacturers, the priority is to align product roadmaps with the dual reality of diesel-dependent heavy-duty demand and accelerating interest in low-emission, low-noise operation. Rather than treating electrification as a separate product line, integrate powertrain options into a coherent platform strategy that clarifies application fit, runtime constraints, and service requirements. Invest in parts availability, field support coverage, and configuration guidance that help procurement teams specify the right machine for each use case, because specification confidence is becoming a decisive factor in municipal and contractor purchasing.
PW Consulting
For investors and strategic buyers, the most valuable signals are not headline growth rates alone but the structural durability of demand drivers and the competitive differentiation potential of service ecosystems. Equipment segments tied to compliance-driven maintenance, utility expansion, and specialized ducting workflows offer defensible revenue logic, especially where aftermarket parts, cable replacement cycles, and service responsiveness create recurring value. Evaluate exposure to raw material volatility and assess whether target companies have pricing strategies, supplier diversification, or value-added service models that can protect margins through procurement cycles.
For municipal operators, contractors, and procurement teams, the immediate focus should be on total cost of ownership alignment rather than unit price comparison. Match machine type, cable configuration, and power source to the actual debris mix, pipe diameter range, and site access constraints of the job portfolio. Where possible, structure purchasing decisions to include service response expectations, parts lead times, and operator training support, since these operational factors often determine whether equipment delivers its intended efficiency over multiple seasons. Anticipate tighter specification requirements and longer procurement cycles by engaging early with equipment providers who can translate operational needs into bid-ready configurations.
Worldwide Die Sorters Market
Detailed segmentation data, procurement mapping, and company-specific capability assessment can sharpen these decisions further, particularly when evaluating regional demand intensity, product fit by application, and competitive positioning across the largest revenue pools. More granular analysis is available in the PW Consulting report on the worldwide rodder machine market for teams that need to translate these strategic trends into procurement timing, product portfolio decisions, or investment prioritization.
For detailed analysis of this topic, please visit the official page: Worldwide Rodder Machine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Multivalent Pneumococcal Conjugate Vaccine Market: Why 8.82% CAGR and 19.97B Growth Reshape Strategy
By pmarketresearch, 2026-09-18
Worldwide Multivalent Pneumococcal Conjugate Vaccine Market: Strategic Trends and Commercial Opportunities Through 2032
Market Overview and Core Challenges
The global multivalent pneumococcal conjugate vaccine market has demonstrated consistent expansion, growing from approximately $7.4 billion in 2020 to an estimated $11.1 billion in 2025. Projections indicate the market will reach nearly $20 billion by 2032, reflecting a compound annual growth rate of 8.82 percent. This trajectory underscores the essential role these vaccines play in global public health, as well as the increasing prioritization of pneumococcal disease prevention across diverse population segments. The market structure remains highly concentrated, with a small number of established players controlling the majority of revenue, creating both barriers to entry and opportunities for strategic differentiation.
Despite this favorable growth outlook, the industry faces several structural challenges that will shape competitive dynamics in the coming years. First, cold chain logistics represent a significant cost and operational burden. Pneumococcal conjugate vaccines require strict storage at 2-8°C, with cold chain expenses accounting for approximately 50 to 55 percent of total distribution costs. In developing regions, temperature excursions can compromise 15 to 20 percent of delivered doses, creating reliability gaps that undermine immunization program effectiveness and increase total cost of ownership for procurement agencies.
PW Consulting
Second, regulatory and reimbursement landscapes are evolving rapidly, creating both opportunities and compliance complexity. As of May 2025, 170 of 194 WHO member states have incorporated pneumococcal conjugate vaccines into infant national immunization programs, with 15 additional countries planning introduction. While this expansion drives volume, it also intensifies price pressure in publicly funded markets and requires manufacturers to navigate diverse regulatory pathways, health technology assessment requirements, and tender processes. Reimbursement policies continue to shift, particularly for adult indications, where recommendations such as the CDC ACIP update endorsing 21-valent pneumococcal conjugate vaccine use for adults 50 years and older illustrate how guideline changes can reshape demand patterns overnight.
Third, the expiration of key intellectual property protections introduces competitive disruption. Pfizer's patent for Prevnar 13 is set to expire in 2026, potentially enabling biosimilar or generic 13-valent products to enter the market. This event will test the resilience of incumbent franchise revenues and may accelerate pricing renegotiation in both pediatric and adult segments. Companies that rely heavily on legacy valency products will need to manage portfolio transitions carefully, while new entrants may find targeted opportunities in markets where price sensitivity is high and regulatory pathways for follow-on products are well defined.
Key Growth Drivers
Technological Innovation and Next-Generation Valency Profiles
The most transformative driver in the market is the advancement of higher-valent formulations and novel manufacturing platforms. The shift from 13-valent and 15-valent products toward 20-valent and 21-valent candidates reflects a clear commercial and clinical imperative: broader serotype coverage addresses residual disease burden and strengthens value propositions for both pediatric and adult immunization programs. Recent clinical data support this direction. In September 2025, Merck reported positive Phase 3 STRIDE-13 results evaluating CAPVAXIVE, a 21-valent pneumococcal conjugate vaccine, in children and adolescents at increased risk of pneumococcal disease. This milestone expands the potential indication space for higher-valent products beyond adult populations and signals that broader coverage can be achieved without compromising safety or immunogenicity profiles.
Parallel innovation is occurring in manufacturing technology. Companies such as Inventprise are advancing 25-valent pneumococcal conjugate vaccine candidates using automated manufacturing processes designed to reduce cost and improve scalability for low- and middle-income countries. Meanwhile, Vaxcyte has reported positive topline results from a Phase 2 dose-finding study of VAX-24, a 24-valent candidate, in healthy infants compared to Prevnar 20. These developments suggest that next-generation platforms may eventually offer both broader coverage and more favorable production economics, potentially reshaping cost structures and enabling access in markets that have historically been underserved.
Policy Momentum and National Immunization Program Expansion
Public health policy remains a primary demand catalyst. The widespread adoption of pneumococcal conjugate vaccines into infant national immunization programs across 170 WHO member states creates a stable, volume-driven baseline for market growth. Countries planning introduction represent additional addressable demand, particularly where Gavi support or bilateral funding mechanisms reduce budget constraints. Beyond pediatric programs, adult immunization guidelines are expanding, driven by growing recognition of pneumococcal disease burden in older populations and individuals with underlying risk factors. The CDC ACIP recommendation supporting 21-valent pneumococcal conjugate vaccine use for adults 50 years and older exemplifies how guideline evolution can unlock new commercial pathways and stimulate adult market growth, which currently represents a substantial portion of total revenue.
Demand-Side Shifts and Demographic Trends
Demand patterns are being reshaped by demographic change and heightened awareness of pneumococcal disease across the lifespan. Aging populations in developed markets increase the absolute number of adults eligible for vaccination, while improved disease surveillance and physician education drive higher recommendation rates. In pediatric populations, the focus has shifted from basic serotype coverage to comprehensive protection that minimizes residual invasive disease and non-invasive pneumonia. Healthcare providers and procurement agencies increasingly evaluate vaccines based on total value, including serotype match to local epidemiology, dosing schedules, and real-world effectiveness data. This shift compels manufacturers to generate robust post-marketing evidence and to align product positioning with the specific needs of national immunization technical advisory groups and procurement decision-makers.
Supply Chain Evolution and Cost Structure Dynamics
Supply chain resilience has emerged as a strategic priority following global disruptions that exposed vulnerabilities in centralized manufacturing and distribution models. Complex conjugation technology and capsular polysaccharide production have historically limited the supplier base to organizations with moderate-to-high technical capability. However, new entrants have increased supply diversity since 2019, reducing single-source dependency and introducing competitive pressure on pricing and capacity allocation. At the same time, cold chain requirements continue to inflate distribution costs, particularly in regions with fragmented logistics infrastructure. Companies that invest in temperature-stable formulations, localized fill-finish capabilities, or partnerships with logistics providers specializing in vaccine distribution can differentiate on reliability and total cost, turning a structural cost burden into a competitive advantage.
Competitive Landscape and Leading Strategies
The competitive environment is defined by a small group of multinational innovators holding dominant market positions, complemented by a growing set of regional manufacturers and technology-driven newcomers. Incumbents have built strong franchises around established valency profiles and extensive clinical databases, while newer participants are pursuing differentiation through higher valency, novel platforms, or cost-optimized manufacturing. Understanding the strategic positioning of key players clarifies where value is being created and where competitive pressure is likely to intensify.
Incumbent Strategies and Franchise Management
Pfizer maintains a leading position through its Prevnar 13 and Prevnar 20 portfolios, with the 20-valent product approved for prevention of invasive pneumococcal disease and pneumonia across pediatric and adult populations. The company's strategy centers on leveraging deep clinical evidence, established relationships with immunization programs, and global commercial infrastructure. However, the 2026 patent expiration for Prevnar 13 introduces portfolio management complexity, requiring proactive lifecycle planning, potential label expansions, and strategic pricing approaches to defend market share as follow-on products emerge.
Merck has pursued a differentiated path with VAXNEUVANCE, a 15-valent product for infants, children, and adults, and CAPVAXIVE, a 21-valent vaccine approved for adults 18 and older. The positive Phase 3 STRIDE-13 data in pediatric and adolescent populations at increased risk could broaden the commercial footprint of CAPVAXIVE and strengthen Merck's position in higher-valent segments. By extending indication potential beyond adults, Merck is positioning its portfolio to capture demand from both demographic groups while leveraging the clinical credibility of its broader vaccine franchise.
Collaborative Development and Next-Generation Pipelines
Collaboration has become a defining feature of competitive strategy, particularly for companies seeking to accelerate development and share commercialization risk. Sanofi and SK bioscience expanded their agreement in January 2025 to develop, license, and commercialize next-generation pneumococcal conjugate vaccines, including a 21-valent candidate for pediatric and adult populations. Sanofi initiated its Phase 3 program for this 21-valent candidate in December 2024, marking the first pneumococcal conjugate vaccine candidate with more than 20 serotypes to enter Phase 3 in infants and toddlers. SK bioscience supported this effort by expanding its L HOUSE production facility in Andong in June 2025, strengthening manufacturing capacity to support global supply. This partnership illustrates how combining development expertise, manufacturing scale, and regional capabilities can accelerate time-to-market and expand geographic reach.
Travelers Vaccines Market
Regional Manufacturers and Value-Based Positioning
Regional players are carving out positions by focusing on affordability, supply reliability, and alignment with domestic immunization priorities. GlaxoSmithKline markets Synflorix, a 10-valent product primarily used in pediatric national immunization programs, maintaining a presence in markets where established coverage and cost considerations favor this valency profile. Serum Institute of India produces Pneumosil, an affordable 10-valent conjugate vaccine for pediatric immunization, with additional candidates in development, reinforcing its role as a high-volume supplier for price-sensitive markets. Chinese manufacturers including Walvax Biotechnology, Beijing Minhai Biological Technology, Shenzhen Kangtai Biological Products, and Chengdu Institute of Biological Products are active in producing and developing 13-valent and other pneumococcal conjugate vaccines, primarily for domestic demand. Their continued investment signals a broader trend of regional supply localization and the potential for expanded export capacity as manufacturing scale and regulatory experience grow.
Emerging Entrants and Platform-Based Disruption
New entrants are pursuing higher-valent candidates and innovative manufacturing approaches that could alter long-term market dynamics. Inventprise is advancing a 25-valent pneumococcal conjugate vaccine with automated manufacturing designed to improve affordability in low- and middle-income countries, targeting a segment where cost and supply reliability are decisive factors. Vaxcyte is developing next-generation candidates including VAX-24 and VAX-31 for adult and infant indications, with Phase 3 trials ongoing. The positive Phase 2 data for VAX-24 in healthy infants compared to Prevnar 20 suggests that newer platforms may compete on both coverage and performance, potentially challenging incumbent products if regulatory approval and commercial execution align. These companies represent a longer-term competitive threat to incumbents, particularly in segments where valency leadership and cost efficiency become the primary differentiators.
Future Trends and Commercial Implications
Several converging trends will shape the market over the next three to five years. First, higher-valent products will increasingly become the standard for both pediatric and adult immunization, as clinical data and guideline updates support broader serotype coverage. The commercial implication is clear: portfolios anchored to lower-valent products will face growing pressure to justify their value proposition against newer alternatives, particularly in markets where national advisory bodies prioritize comprehensive protection and where reimbursement decisions are tied to relative effectiveness. Manufacturers with advanced pipeline candidates will have the opportunity to lead category evolution, while those without near-term pipeline momentum may need to rely on pricing, supply reliability, or niche indications to maintain position.
Second, market access and pricing dynamics will become more complex as immunization programs expand and adult demand grows. Public procurement in emerging markets will continue to emphasize affordability, while developed markets may see segmented pricing based on valency, indication, and real-world evidence packages. The CDC ACIP recommendation for 21-valent vaccine use in adults 50 and older illustrates how adult market segments can expand quickly when guidelines evolve, but also how dependent commercial success is on alignment with reimbursement policies and provider behavior. Companies that invest early in health economics data, payer engagement, and guideline-supporting evidence will be better positioned to capture value as these segments mature.
Third, supply chain localization and manufacturing innovation will gain strategic importance. Cold chain costs remain a significant burden, and temperature excursions continue to threaten dose integrity in developing regions. Over time, formulations or delivery approaches that reduce cold chain dependency, combined with distributed manufacturing and regional fill-finish capacity, could lower total program costs and improve reliability. Organizations that anticipate these needs and invest in practical solutions may gain preference in procurement processes, particularly where ministries of health and multilateral agencies prioritize supply security alongside product attributes. A key uncertainty is the pace at which patent expirations and new entrants translate into meaningful price competition, which will depend on regulatory timelines, manufacturing scale-up success, and the willingness of incumbents to defend share through contracting strategies.
Strategic Recommendations for Decision-Makers
Manufacturers should evaluate portfolio strategy against the direction of valency expansion and the timing of patent-related competitive shifts. For incumbents, the priority is to protect franchise value through evidence generation, indication expansion where feasible, and proactive engagement with immunization programs and payers. For companies with pipeline assets, the window to differentiate is narrowing as higher-valent candidates advance through late-stage development, making execution on clinical trials, regulatory strategy, and manufacturing scale-up decisive factors. Investments in cost-optimized production and cold chain resilience can also create durable advantages, especially in markets where procurement decisions weigh total program cost and supply reliability alongside product performance.
Investors should focus on companies with credible higher-valent pipelines, clear regulatory pathways, and manufacturing strategies that address cost and supply constraints. The market's growth trajectory is favorable, but value capture will depend on execution risk, competitive response to patent expirations, and the ability to translate clinical differentiation into reimbursement and procurement outcomes. Monitoring Phase 3 progress, guideline updates, and capacity expansion announcements will provide early signals about which players are likely to gain share and which may face margin pressure.
Procurement organizations and health system leaders should assess vaccine selection based on total value, including serotype coverage aligned with local epidemiology, dosing schedule practicality, supply reliability, and cold chain implications. As more higher-valent options become available, structured evaluation frameworks that incorporate real-world evidence, total cost of ownership, and supply security will support more resilient immunization programs. Engaging early with manufacturers on capacity planning and supply commitments can reduce vulnerability to shortages and price volatility, particularly in markets where demand is growing and supply diversity is still increasing.
For stakeholders seeking a more detailed view of segment-level dynamics, regional demand patterns, pipeline timelines, and company-level competitive assessments, the full PW Consulting report provides deeper data and customized strategic guidance to support planning and investment decisions.
Pneumococcal Vaccination Market
For detailed analysis of this topic, please visit the official page: Worldwide Multivalent Pneumococcal Conjugate Vaccine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Flexible Microporous Insulation Panel Market: Why 4.52% CAGR by 2032 Changes Everything
By pmarketresearch, 2026-09-18
Navigating the Global Flexible Microporous Insulation Panel Market: Strategic Trends and Commercial Opportunities
Market Landscape and Core Challenges
The worldwide market for flexible microporous insulation panels has demonstrated remarkable resilience and steady expansion over the past half-decade. Valued at approximately USD 172.54 million in 2025, the industry has navigated a complex trajectory from its 2020 baseline of USD 138.45 million, reflecting a compound annual growth rate of 4.52 percent through the forecast horizon extending to 2032. This growth trajectory underscores the material's critical role across high-temperature industrial processes, advanced aerospace applications, and emerging energy sectors. The market's evolution from a niche specialized product to a more broadly adopted thermal management solution signals a maturing industry poised for continued innovation and commercial expansion.
Despite the positive outlook, the sector faces structural headwinds that demand strategic attention. First, raw material volatility presents a persistent margin pressure. Fumed silica, the cornerstone of most microporous formulations, has experienced significant price fluctuations, with spot prices oscillating between 5,000 and 6,000 USD per ton during the 2025-2026 period. Regional disparities further complicate procurement strategies, as evidenced by Q3 2025 pricing that saw 6,322 USD per metric ton in the United States, 5,580 USD in Japan, and 5,108 USD in Germany. Simultaneously, precursor chemicals have faced upward cost pressures, with methyltrimethoxysilane and tetraethyl orthosilicate silane precursors climbing 22 percent year-over-year in 2025. These input cost dynamics directly impact production economics and challenge manufacturers to maintain pricing stability while preserving quality standards.
PW Consulting
Second, the industry confronts an evolving regulatory and compliance landscape. Stringent thermal efficiency requirements, combined with increasingly rigorous environmental standards across industrial sectors, are reshaping specifications and qualification processes. The shift toward lower carbon footprints and sustainable manufacturing practices adds complexity to product development cycles, particularly for companies serving multiple geographies with divergent regulatory regimes. Organizations must balance performance optimization with compliance costs, a tension that disproportionately affects smaller producers with limited R&D resources.
Third, the market exhibits moderate concentration dynamics that influence competitive behavior. The top three players command approximately 42 percent of total revenue, while the top five capture roughly 58 percent. This concentration creates both barriers to entry and opportunities for differentiated positioning. Established players benefit from scale economics, extensive qualification portfolios, and long-term customer relationships, yet the remaining market share leaves room for agile entrants and regional specialists to carve out defensible niches. The challenge for incumbents lies in defending share without compromising innovation velocity, while new entrants must navigate qualification timelines and customer trust barriers in highly regulated end markets.
Key Drivers Shaping Market Dynamics
Technological Innovation and Material Science Breakthroughs
Advancements in material formulation and manufacturing processes represent the most potent catalyst for market expansion. The dominance of silica-based compositions, which leverage fumed or precipitated silica combined with specialized opacifiers, reflects decades of refinement in microporous architecture. Recent developments in zirconium-silicate opacifier technology have enabled enhanced thermal reflectivity and structural stability at extreme temperatures, directly addressing performance demands in steel manufacturing and molten metal handling applications. The 18 percent price increase in zirconium-silicate opacifiers during the first quarter of 2026, driven by reduced African ilmenite exports, highlights both the critical nature of these additives and the supply chain vulnerabilities that accompany specialized material dependencies.
Vacuum Insulation Panel (VIP) Market
Beyond raw material composition, manufacturing technique innovation continues to unlock new application possibilities. Flexible panel designs now integrate felt and blanket versatility into unified products that adapt to complex geometries without sacrificing thermal performance. Overstitched, slated, and semi-overstitched configurations address diverse installation requirements, from pipeline wrapping in petrochemical facilities to intricate thermal protection in aerospace assemblies. Companies investing in proprietary production methods that reduce material waste, improve consistency, or enable customized thickness profiles are gaining competitive advantage in sectors where installation efficiency translates directly to total cost of ownership.
Composite Insulated Panels Market
Policy and Regulatory Environment Evolution
Government mandates and industry standards are fundamentally reshaping demand patterns. Energy efficiency regulations in industrial facilities, driven by both economic incentives and sustainability commitments, are accelerating the replacement of conventional insulation materials with higher-performance microporous alternatives. The superior thermal resistance of flexible microporous panels enables facilities to achieve measurable reductions in heat loss, directly impacting operational expenditure and carbon emission profiles. In regions with aggressive decarbonization targets, these regulatory tailwinds create a compulsory upgrade cycle that benefits manufacturers with proven, certified products.
Aerospace and defense sectors present a parallel but distinct regulatory dynamic. Qualification requirements for thermal protection systems in aircraft, spacecraft, and defense platforms involve rigorous testing protocols and lengthy approval cycles. While this creates entry barriers, it also fosters long-term vendor relationships and recurring demand once qualification is achieved. Policy shifts toward domestic manufacturing capabilities in aerospace supply chains, particularly in North America and Europe, are generating incremental opportunities for regional producers who can demonstrate compliance with local content requirements while meeting performance specifications.
Demand-Side Transformation and End-User Behavior
End-user priorities are shifting from pure upfront cost considerations to holistic value assessments that incorporate installation efficiency, maintenance reduction, and lifecycle performance. Industrial operators managing high-temperature pipelines, refractory structures, and process equipment increasingly recognize that flexible microporous panels offer distinct advantages over rigid alternatives in applications requiring movement accommodation, vibration resistance, or irregular surface conformity. The automotive and fuel cell segment exemplifies this evolution, as electrification and hydrogen infrastructure development create novel thermal management challenges that demand lightweight, flexible solutions capable of withstanding rapid temperature cycling.
Aerospace and defense procurement behavior similarly reflects a growing emphasis on weight reduction and multi-functionality. Flexible microporous systems that combine thermal insulation with mechanical durability, fire resistance, and ease of field installation command premium valuation in applications where weight savings translate to fuel efficiency or payload capacity. The demand for quilted flexible composites and vacuum insulation panel cores in aerospace contexts demonstrates how material versatility expands addressable markets beyond traditional industrial insulation boundaries.
Supply Chain Restructuring and Cost Dynamics
The geographic distribution of production capacity is undergoing noticeable realignment. While established European and North American manufacturers maintain strong positions rooted in technological heritage and deep customer relationships, Asian producers have expanded their footprint through competitive pricing, scalable manufacturing, and targeted investment in product development. China-based companies now offer a broad spectrum of flexible microporous panels spanning high-temperature refractory grades, specialized aerospace formulations, and cost-optimized industrial solutions. This geographic diversification provides end-users with more sourcing options but also introduces quality variability and qualification complexity that procurement teams must navigate carefully.
Cost structure evolution reflects the interplay between raw material markets, energy inputs, and manufacturing efficiency. Fumed silica pricing volatility remains a central concern, with regional arbitrage opportunities creating strategic procurement considerations for globally distributed operations. Precursor chemical cost increases have compressed margins for producers unable to pass through price adjustments or offset input costs through process optimization. Companies that have secured long-term raw material agreements, invested in vertical integration, or developed formulations that reduce dependency on volatile inputs are better positioned to maintain margin stability during periods of market turbulence.
Competitive Landscape and Leading Strategies
The competitive environment reflects a blend of established multinational players, specialized regional manufacturers, and emerging entrants targeting specific application niches. Understanding the strategic postures of key participants provides valuable context for assessing market direction and identifying positioning opportunities.
Promat, operating under the Etex Group umbrella and headquartered in Belgium, has built a reputation around comprehensive product portfolios that span MICROTHERM slatted, floppy, semi-overstitched, and AEROGUARD flexible microporous insulation panels. The company's strength lies in its ability to serve diverse high-temperature industrial, pipeline, two-dimensional shape, and aerospace applications with a unified technology platform. This breadth enables cross-selling opportunities and positions Promat as a one-stop solution provider for customers managing multiple insulation requirements across facilities. Morgan Advanced Materials, based in the United Kingdom, competes through specialized systems including Min-K and WDS flexible microporous insulation solutions. The company's quilted flexible Min-K composites and Vacupor VIP cores demonstrate particular strength in aerospace, industrial, and high-temperature contexts where composite material performance and vacuum insulation integration create differentiated value propositions. Morgan's focus on engineered solutions rather than commodity insulation positions it favorably in applications where performance requirements exceed standard specifications.
The Asian manufacturing landscape features several notable participants with distinct strategic orientations. Zhengzhou Firebird New Material Co., Ltd. emphasizes the MIP-1050 Flex and related flexible microporous panels and boards that combine felt and blanket versatility for refractory and industrial applications. This product philosophy targets customers seeking adaptable solutions for high-temperature environments where installation flexibility matters. Unicorn Insulations Limited, with operations spanning China, Malaysia, and Spain, focuses specifically on flexible microporous panels for high-temperature pipes in petrochemical, power generation, and industrial sectors. This application concentration allows the company to develop deep expertise and tailored solutions for pipeline insulation challenges. North Refractories Co., Ltd. manufactures flexible microporous boards and panels across multiple temperature grades, ranging from 1,000 to 1,200 degrees Celsius, catering to thermal insulation applications that demand reliable performance at elevated temperatures. ThermoDyne, headquartered in the United States, supplies DynaGuard and Excelflex flexible microporous insulation systems designed for industrial, commercial, and aerospace environments characterized by high vibration and temperature extremes. The company's emphasis on durability under mechanically demanding conditions differentiates its offerings in niche segments where conventional flexible insulation would degrade prematurely.
Additional players enrich the competitive fabric through specialized capabilities. Luyang Energy-Saving Materials Co., Ltd. offers Luyang Nano and microporous soft boards and panels in flexible forms covered with glass fiber cloth for refractory high-temperature insulation, emphasizing cost-effective solutions for demanding thermal environments. Wedge Industries Limited, operating from India, manufactures and imports flexible microporous insulation overstitched panels, slated panels, and blankets using Microtherm raw materials for energy-saving applications, leveraging established material partnerships to deliver recognized quality standards. Siltherm Group Holdings Ltd. produces Siltherm AluFlex flexible microporous panels developed specifically for steel industry and molten metal high-temperature applications, demonstrating how application-focused product development can create defensible market positions. Nanovix Thermal Insulation Co., Ltd. specializes in flexible microporous insulation panels and tailor-made products for high-temperature industrial uses, with customization capabilities that address unique customer requirements.
Several strategic patterns emerge from this competitive mosaic. First, application specialization is becoming an increasingly attractive positioning strategy. Companies that concentrate on particular end-use sectors—whether aerospace thermal protection, pipeline insulation, or steel industry refractory applications—develop deeper customer intimacy, more targeted product development, and stronger qualification portfolios than generalist competitors. This specialization can create sustainable competitive advantages in sectors where application knowledge and proven performance history carry significant weight in procurement decisions.
Second, geographic expansion and local presence are gaining importance. As end-users across industrial, aerospace, and energy sectors prioritize supply chain resilience and responsive service, manufacturers with regional production facilities, technical support teams, and qualified product availability in key markets gain procurement preference. The presence of multiple Chinese manufacturers with international operations, combined with European and North American incumbents maintaining global footprints, reflects a market where geographic coverage and local capability increasingly influence competitive outcomes.
Third, the market structure suggests continued evolution toward both consolidation and fragmentation simultaneously. Larger players with broad portfolios and global reach may pursue acquisitions to expand application coverage, geographic reach, or technological capabilities. Simultaneously, smaller specialized producers and regional manufacturers can thrive by serving niche applications, offering customized solutions, or providing cost-competitive alternatives in less regulated segments. The moderate market concentration indicates room for both dynamics to coexist, with competitive outcomes determined by execution quality, customer relationships, and adaptability to changing requirements.
Future Outlook and Emerging Trends
Looking ahead across the 2026-2032 forecast horizon, several trends will likely shape market trajectories and create distinct commercial opportunities. The first and most consequential is the acceleration of high-performance insulation adoption driven by energy efficiency mandates and total cost of ownership calculations. As industrial operators, power generation facilities, and infrastructure developers face mounting pressure to reduce energy consumption and emissions, flexible microporous panels' superior thermal performance will increasingly justify premium pricing. Organizations that can demonstrate quantifiable energy savings, reduced maintenance requirements, and extended service life will capture growing demand from procurement teams evaluating insulation investments through lifecycle costing frameworks rather than initial price comparisons. This trend favors manufacturers with robust documentation, third-party certifications, and field performance data that substantiate performance claims.
A second trend involves the expansion of application boundaries into emerging sectors. The automotive and fuel cell segment, currently representing a meaningful share of market activity, is poised for growth as hydrogen infrastructure development and electric vehicle thermal management requirements create new demand vectors. Flexible microporous materials that can withstand rapid thermal cycling, resist chemical exposure, and conform to compact packaging constraints position well for these applications. Similarly, aerospace and defense activities will likely see sustained demand as next-generation aircraft, spacecraft, and defense systems require advanced thermal protection that balances weight, durability, and performance. Companies that invest early in qualifying products for these emerging applications and building relationships with design engineers and procurement teams will establish footholds that translate into long-term revenue streams.
A third trend concerns raw material supply chain restructuring and its implications for competitive dynamics. The volatility in fumed silica pricing, precursor chemical costs, and opacifier availability will likely persist, driven by geopolitical factors, regional production constraints, and changing demand patterns from adjacent industries. Manufacturers that develop alternative formulations, secure diversified supply sources, or create value-added products that reduce raw material intensity will gain margin resilience. Conversely, producers heavily dependent on single-source inputs or exposed to regional price spikes without mitigation strategies face ongoing profitability challenges. This dynamic may accelerate industry consolidation as larger players acquire smaller competitors to achieve supply chain scale, or alternatively, spur innovation as companies seek formulation efficiencies to offset input cost pressures. The zirconium-silicate opacifier price increase observed in early 2026 illustrates how specific raw material disruptions can ripple through product economics and necessitate strategic responses.
Potential risks and uncertainties warrant careful monitoring. Regulatory changes that alter qualification requirements or restrict certain material compositions could disrupt product development timelines and market access. Economic downturns affecting industrial capital expenditure could temporarily dampen demand growth, particularly in segments tied to facility construction and equipment installation cycles. Competitive entry from adjacent insulation technologies, including advanced ceramic fibers and aerogel-based solutions, could erode market share in applications where flexible microporous panels face performance or cost comparisons. Organizations operating in this market must maintain awareness of these risk factors and develop contingency strategies that preserve flexibility and optionality.
Strategic Recommendations for Decision Makers
For manufacturers and product developers, the priority is investing in application-specific innovation that addresses evolving performance requirements while managing raw material exposure. Developing formulations that reduce dependency on volatile inputs, expanding qualification portfolios in high-growth segments like aerospace and fuel cell applications, and strengthening regional presence in key markets will enhance competitive positioning. Companies should also evaluate vertical integration opportunities or long-term supplier partnerships that provide cost stability and supply assurance. Building technical support capabilities that help customers optimize installation and achieve target performance outcomes creates differentiation beyond product specifications and fosters enduring relationships.
For investors evaluating opportunities in this sector, the focus should be on companies demonstrating sustainable competitive advantages through technology differentiation, application specialization, or geographic reach that aligns with demand growth patterns. Assess raw material management strategies, qualification portfolios, and customer concentration risks to gauge resilience against market volatility. Companies with diversified application exposure, strong regional execution capabilities, and clear innovation pipelines present more attractive risk-return profiles than undifferentiated commodity producers. Monitor consolidation activity and strategic moves by leading players that may reshape competitive dynamics or create acquisition opportunities.
For procurement leaders and end-users selecting insulation solutions, the imperative is moving beyond initial price comparisons to comprehensive total cost of ownership evaluations. Evaluate suppliers based on proven field performance in relevant applications, qualification status for specific operating conditions, installation efficiency, maintenance requirements, and long-term availability guarantees. Diversifying supplier relationships across geographic regions can mitigate supply chain risks while maintaining access to specialized products. Engaging with manufacturers early in facility design or equipment specification processes enables optimization of insulation selection for performance, cost, and installation considerations. For those seeking deeper intelligence on specific sub-segments, regional dynamics, competitor benchmarking, and customized strategic guidance, the complete research report provides granular data and actionable frameworks to support informed decision-making.
For detailed analysis of this topic, please visit the official page: Worldwide Flexible Microporous Insulation Panel Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Phlegm Suction Tube Market Set to Hit $926.88M by 2032: Shifts Beyond the 5.2% CAGR
By pmarketresearch, 2026-09-18
Strategic Trends and Commercial Opportunities in the Worldwide Phlegm Suction Tube Market
Market Snapshot and Core Challenges
The global phlegm suction tube market is navigating a phase of steady expansion, characterized by a compound annual growth rate that reflects the underlying health of respiratory care infrastructure worldwide. Revenue projections over the coming decade indicate a market trajectory moving toward higher valuation thresholds, driven by consistent demand across established healthcare economies. This growth is not uniform but rather paced by regional healthcare spending patterns, procurement cycles, and the gradual modernization of acute care facilities in developing regions.
Worldwide Expectoration Machine Market
A defining feature of the current landscape is the concentration of market value among a relatively small group of major players, reflecting consolidated distribution channels and entrenched supplier relationships in key hospital networks. This concentration shapes pricing dynamics and creates barriers for new entrants seeking to scale without established clinical references. At the same time, the product mix continues to shift as clinicians weigh the clinical outcomes of closed versus open suction approaches, particularly in environments where infection control protocols carry significant operational weight.
Despite steady growth, the sector faces three pressing inflection points. First, sterility assurance remains a persistent operational risk. A high-profile recall involving closed suction catheter systems, linked to potential sterility lapses from gamma irradiation process variations, underscored how quality control failures can erode clinical trust and disrupt supply continuity across multiple product lines. Second, regulatory and reimbursement frameworks are evolving in ways that reward specific design attributes. Standards governing dimensional precision, flow resistance, leakage performance, and protective sleeve integration are increasingly treated as baseline expectations rather than optional enhancements. Reimbursement policies tied to suction pumps and designated catheter categories further influence purchasing decisions, requiring manufacturers to align product portfolios with coding and coverage parameters in major markets. Third, raw material sourcing introduces cost and flexibility trade-offs. Medical-grade PVC and silicone dominate production, yet the broader medical tubing supply environment carries volatility tied to petrochemical feedstock pricing, capacity constraints, and shifting demand for biocompatible, flexible materials in single-use devices.
For executives and planners, the central question is how to navigate these pressures while capturing growth from expanding respiratory care volumes, procedural complexity, and the gradual shift of certain suction needs into lower-acuity and home-based settings. Success increasingly depends on anticipating quality scrutiny, aligning with evolving standards, and positioning product offerings where clinical and economic value intersect.
Key Drivers Shaping Market Dynamics
Technology innovation is reshaping how airway secretion management is approached, with design refinement taking center stage. Closed suction systems continue to gain clinical preference in intensive care and mechanically ventilated environments, where minimizing circuit disconnection reduces exposure to contaminants and supports ventilator-associated pneumonia prevention strategies. Integrated suction control features, reinforced lumens, and protective sleeve architectures are becoming standard expectations rather than premium add-ons. At the same time, open suction catheters remain relevant in specific procedural and emergency scenarios, particularly where rapid access, tactile feedback, or compatibility with certain airway configurations is prioritized. Manufacturers are responding by refining tip geometries, flexibility profiles, and material performance to reduce tissue trauma while maintaining suction efficiency across a range of sizes and clinical use cases.
Policy and regulatory conditions are reinforcing a compliance-first product development mindset. International standards such as ISO 8836 specify critical performance parameters for airway suction catheters, including dimensional tolerances, leakage behavior, flow resistance, and information requirements for manufacturers. In the United States, tracheobronchial suction catheter kits are generally classified as Class II devices, with many open suction catheters exempt from premarket notification but still subject to general controls, quality system expectations, and labeling requirements. A recent FDA clearance granted to disposable irrigation and suction catheter models for surgical suction and irrigation procedures illustrates how regulatory pathways are adapting to accommodate products used alongside endoscopic and handpiece applications. At the same time, voluntary recalls tied to sterility risks serve as a reminder that regulatory permissions do not eliminate the need for robust manufacturing process control, especially where gamma irradiation or sterilization validation is involved. For commercial teams, the implication is clear: evidence of compliance, validated manufacturing controls, and transparent labeling increasingly influence formulary acceptance and procurement confidence.
Tracheostomy Tube Market
Demand-side behavior is changing as healthcare delivery models diversify. Hospital and clinic settings remain the primary absorption point for suction catheters, reflecting high patient volumes, procedural intensity, and the continued centrality of airway management in critical care. However, the broader care continuum is expanding. Home care settings and ambulatory surgical centers are generating incremental demand for compact, disposable, and clinician-friendly suction solutions, particularly where patient mobility, outpatient procedures, and decentralized respiratory management are growing. This shift is not simply about volume; it is about context. Products designed for institutional use must be evaluated differently when deployed in environments with limited staffing, different storage constraints, or varied patient education needs. As a result, differentiation is increasingly tied to usability, packaging convenience, and compatibility with the equipment and workflows present in each setting.
Supply chain and cost structure dynamics are also exerting pressure on margins and sourcing strategies. The medical tubing market remains anchored in materials such as medical-grade PVC and silicone, both valued for flexibility, biocompatibility, and processability in disposable device manufacturing. Demand for these materials continues to be supported by broader adoption of single-use devices, but pricing exposure to raw material fluctuations, logistics complexity, and regional manufacturing capacity creates operational sensitivity. Companies are increasingly balancing proximity to end markets against cost efficiency, with some manufacturers building export-oriented production footprints to serve multiple geographies while others focus on localized supply to reduce lead times and improve responsiveness. The net effect is a market where procurement leverage is tied not only to unit price but also to reliability, consistency, and the ability to support bulk ordering without compromising product integrity.
PW Consulting
Competitive Landscape and Leading Strategies
The competitive field is populated by a mix of large diversified medical-supply organizations, specialized respiratory-care manufacturers, and export-focused producers based in Asia. Major U.S.-based players occupy positions where breadth of product availability, established distributor networks, and integration into institutional procurement systems provide a strong advantage. These organizations often compete on reliability, catalog breadth, and the ability to support large-scale purchasing across multiple care settings. At the same time, several specialized manufacturers focus on suction catheters as part of broader surgical or respiratory portfolios, leveraging flexible manufacturing, disposable-product expertise, and regional cost advantages to serve both domestic and international markets.
Leading companies are pursuing differentiation through a combination of product architecture, clinical positioning, and supply reliability. One common strategy is to emphasize closed-system capabilities for critical care and respiratory applications, where sterility, ease of integration with ventilation circuits, and reduced contamination risk are central selling points. Another approach centers on offering a full size range and multiple tip or valve configurations, enabling hospitals to standardize on fewer product families while still matching catheter selection to patient anatomy and procedure type. A third path involves disposable-focused manufacturing models that emphasize sterile packaging, variable order quantities, and rapid replenishment, which is particularly relevant for high-use facilities managing inventory turnover and contamination control.
Several strategic patterns stand out in how these players position themselves. Diversified suppliers tend to reinforce value through breadth and purchasing convenience, making it easier for procurement teams to consolidate orders across multiple consumables. Mid-sized and export-oriented manufacturers often compete on responsive production, competitive pricing, and adaptability to custom specifications, which can be attractive to buyers seeking flexibility or regional sourcing alternatives. In addition, product recall events have intensified attention to manufacturing controls and sterility assurance across the sector. Companies that can clearly demonstrate process discipline, traceability, and corrective action capability are better positioned to maintain trust after industry-wide quality disruptions. Conversely, organizations perceived as reliant on opaque supply processes may face heightened scrutiny from clinical and procurement stakeholders.
The market structure is evolving through a blend of consolidation pressures and segmentation opportunities. On one side, larger buyers increasingly prefer suppliers who can offer integrated consumables portfolios, consistent quality documentation, and the scale to support contract manufacturing or private-label arrangements. On the other side, niche and regionally focused producers continue to find room by addressing size ranges, material preferences, or application-specific needs that may be underserved in standardized catalogs. New entrants face a meaningful hurdle in building clinical references and distribution relationships, but product-level innovation, regulatory clearances for expanded indications, and strong regional manufacturing leverage can still create viable entry points. Over time, the competitive edge is likely to belong to organizations that combine dependable quality systems with clear differentiation in suction performance, usability, and compatibility with evolving care settings.
Forward-Looking Trends and Commercial Implications
Over the next three to five years, one defining trend will be the continued clinical prioritization of closed suction systems in ventilated and critical care environments, supported by infection-control expectations and workflow preferences. This will likely sustain demand for closed-system designs with reliable suction control, protective sleeve integrity, and strong leakage and flow-resistance performance. Companies that can deliver consistent quality while maintaining competitive cost structures will be well placed to capture share in institutions standardizing on closed-circuit airway management.
A second trend is the gradual broadening of suction catheter demand beyond traditional inpatient settings. As home care and ambulatory surgical activity expand, product requirements will increasingly emphasize ease of use, compact packaging, role-specific configurations, and compatibility with portable or lower-resource equipment. This creates opportunities for streamlined, disposable-focused product lines and kits that reduce setup complexity and support decentralized care models. At the same time, this shift brings reimbursement complexity, since coverage rules differ across catheter categories and depend on associated equipment justifications, meaning commercial success will depend on alignment with coding and coverage realities in each market.
A third trend is the growing importance of manufacturing process discipline and traceability. Sterility-related recalls in the sector have highlighted how quality failures can quickly translate into supply interruptions, clinical concern, and reputational damage. In response, procurement teams are likely to place greater weight on documented quality systems, sterilization validation, and responsiveness to corrective actions. This trend favors suppliers that can provide transparent evidence of process control and that have built resilience into their production and distribution networks. The associated risk is that any new quality incident can affect not only the involved company but also broader market confidence in specific product types or sterilization methods. Market participants should therefore treat quality assurance as a commercial differentiator rather than a back-office function.
Actionable Guidance for Decision Makers
For manufacturers, the priority is to align product roadmaps with clinical demand trends while strengthening the operational foundations that support trust in the field. This means investing in design refinements that improve suction efficiency, usability, and compatibility across care settings, while simultaneously reinforcing sterilization validation, dimensional consistency, and labeling clarity. Companies should also evaluate whether their portfolios are sufficiently flexible to serve both institutional and decentralized-care buyers, since those segments increasingly influence total demand.
For investors, the most compelling signal is the combination of steady volume growth and differentiation opportunities around quality, infection-control value, and setting-specific product design. Capital allocation should favor businesses with demonstrable manufacturing discipline, diversified end-market exposure, and the ability to navigate reimbursement nuances without overreliance on any single buyer segment. Competitive positions built on scale alone are less durable where clinical stakeholders are increasingly attentive to sterility assurance and compliance documentation.
For procurement and supply chain leaders, the strategic focus should move beyond unit cost to include supplier reliability, traceability, and the capacity to support bulk ordering without compromising sterility or delivery consistency. Evaluating suppliers on their documentation practices, recall readiness, and ability to meet recognized technical specifications can reduce downstream disruption risk. In markets where regulatory frameworks and reimbursement conditions shape purchasing, aligning product selection with those parameters can also improve cost predictability and access.
The strategic picture is clear enough to guide immediate decisions, but the granular opportunities, segment-specific pricing dynamics, and regional procurement realities require deeper evaluation. For decision makers seeking detailed segmentation data, company-level positioning, and tailored scenario analysis, the full PW Consulting report provides the depth needed to translate these market trends into targeted commercial action.
For detailed analysis of this topic, please visit the official page: Worldwide Phlegm Suction Tube Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Halogen-Free Data Cables Market: Why 8.55% CAGR and Asia Pacific Lead 2032 Growth
By pmarketresearch, 2026-09-18
The Strategic Outlook: Navigating Opportunities in the Worldwide Halogen-free Data Cable Market
Market Overview and Critical Challenges
The global halogen-free data cable market has entered a phase of sustained expansion, driven by a convergence of safety regulations, technological infrastructure upgrades, and shifting enterprise procurement standards. Between 2020 and 2025, the market evolved from a niche compliance-driven segment into a mainstream component of modern data and communications infrastructure. Revenue growth has consistently outpaced broader cable sector averages, with the compound annual growth rate projected at 8.55 percent through 2032. This trajectory reflects more than regulatory tailwinds; it signals a structural realignment in how organizations design, deploy, and manage data transmission networks in environments where fire safety, air quality, and environmental impact carry direct operational and financial consequences.
The market size progression underscores this momentum. Revenue expanded from approximately 1,350 million in 2020 to over 2,003 million in 2025, and forward estimates place the market above 3,557 million by 2032. Such figures represent a market that has moved beyond early adoption cycles into a growth phase supported by recurring infrastructure investment cycles, data center build-outs, industrial network modernization, and commercial building retrofits. Yet the headline growth masks underlying friction points that decision-makers must navigate carefully. The expansion is not uniform across product categories or end-use environments, and the competitive playing field continues to reshape around material innovation, certification agility, and supply chain resilience.
One of the most pressing challenges confronting the sector is the tension between performance requirements and material constraints. Halogen-free compounds must simultaneously satisfy flame-retardant standards, low-smoke emissions criteria, mechanical durability, and signal integrity demands across diverse operating environments. Balancing these attributes often requires complex formulation chemistry, and manufacturers face trade-offs between cost, flexibility, and thermal performance. As applications push into higher-temperature environments and denser cable routing configurations, the margin for formulation errors narrows. Suppliers that cannot iterate quickly on compound engineering risk losing specification wins to competitors with more advanced material portfolios or faster testing and certification pathways.
A second structural challenge revolves around raw material volatility and geographic concentration. Key inputs for low-smoke halogen-free formulations, including specialized flame retardants and base polymers, remain exposed to petrochemical price cycles and regional supply disruptions. Certain critical flame retardant raw materials have historically experienced price spikes exceeding 40 percent during supply interruptions, disproportionately affecting smaller manufacturers and pricing-sensitive regional markets. This exposure complicates long-term contract negotiations, squeezes margins during peak construction or retrofit cycles, and creates opportunities for suppliers that can secure diversified sourcing or develop alternative compound architectures with lower exposure to concentrated supply nodes.
The third challenge lies in regulatory fragmentation and compliance complexity. While directives restricting hazardous substances and broader sustainability expectations have accelerated adoption of halogen-free solutions, the certification landscape remains multi-layered. Different regions and application verticals increasingly reference distinct testing protocols, smoke density thresholds, and material declaration requirements. For multinational operators, maintaining consistent product compliance across jurisdictions adds administrative overhead and can delay project timelines. At the same time, optional certification marks from recognized testing bodies are becoming more visible in procurement evaluations, giving buyers additional assurance while raising the bar for manufacturers that rely on older compliance arrangements.
Taken together, these dynamics define a market that is growing but not frictionless. The winners in the next cycle will be those that treat material science, regulatory alignment, and supply chain design as strategic capabilities rather than operational afterthoughts.
Key Drivers Shaping Market Trajectory
Technology innovation in insulation and jacket formulations represents one of the most consequential drivers of market expansion. Advances in halogen-free compound engineering have progressively closed the performance gap that once limited adoption in demanding environments. Modern formulations increasingly deliver improved flame-retardant behavior without sacrificing flexibility, tensile strength, or high-frequency signal transmission characteristics. This matters because data cable applications are no longer confined to conventional office or campus wiring; they now extend into high-density server halls, automated production lines, transportation hubs, and outdoor infrastructure where environmental stress and fire-risk considerations are more acute. As formulations mature, specifiers gain confidence that safety compliance does not require compromising on installation practicality or network performance.
Recent product introductions illustrate how this innovation axis is translating into market relevance. In early 2026, one manufacturer showcased a halogen-free power and data-related cable series engineered for continuous operation at elevated temperatures, explicitly targeting high-density AI data center power distribution systems and compliant with multiple UL standards. At a major data center industry event shortly afterward, the same company emphasized the thermal demands of AI-focused facilities as a core rationale for halogen-free designs with higher temperature tolerance. Such moves indicate that thermal management and compactness are becoming central design parameters, and that halogen-free cable portfolios are evolving to meet these requirements rather than serving solely as low-smoke alternatives.
Regulatory and standards activity continues to reinforce this direction. Environmental and hazardous-substance directives that restrict certain flame retardants and heavy metals in electrical and electronic equipment have long encouraged a shift toward halogen-free alternatives, but the effect is now deepening as enforcement expectations and buyer due-diligence practices become more rigorous. In parallel, recognized testing and certification organizations have expanded optional halogen-free and low-smoke certification marks aligned with international cable standards, giving procurement teams clearer visual and documentation cues during specification. For manufacturers, this regulatory environment is both a defensive requirement and a competitive lever: consistent compliance reduces market-access risk, while fast, credible certification can become a differentiator in tenders where safety documentation influences shortlisting.
Demand-side behavior is shifting as well, particularly in commercial enterprise and data-intensive facilities. Organizations are increasingly treating low-smoke, halogen-free cabling not as a premium add-on but as a baseline expectation for new builds, major renovations, and risk-sensitive retrofits. This change reflects a broader operational mindset in which indoor air quality, evacuation conditions, asset protection, and sustainability reporting are integrated into infrastructure planning rather than handled as separate compliance tasks. In data center environments, where uptime, density, and thermal constraints dominate decision-making, the request for halogen-free options has gained additional weight because facility designers seek solutions that address fire safety without introducing unnecessary chemical risk or downstream disposal complications. Industrial automation and public infrastructure projects show similar patterns, with engineering teams favoring cables that can withstand demanding installation conditions while meeting fire-safety expectations for occupied or publicly accessible spaces.
Supply chain and cost-structure dynamics are shaping how quickly these demand signals convert into orders. Petrochemical-based polymers, plasticizers, and flame retardants used in halogen-free compounds remain subject to price volatility, and certain key raw materials are sourced from concentrated geographic bases, creating susceptibility to disruptions and price spikes. This environment rewards manufacturers that have built dual-sourcing strategies, secured long-term supply agreements, or invested in compound formulations that reduce dependence on the most volatile inputs. It also creates a strategic opening for regional production and local inventory positioning, especially in markets where project timelines are tight and logistics delays can jeopardize build-out schedules. Companies that can demonstrate cost predictability alongside certified performance are gaining an edge in specification discussions, particularly when buyers are comparing total project cost rather than unit price alone.
Flame Retardant Cable Market
A further driver is the growing alignment between sustainability narratives and procurement realities. While earlier adoption was often framed primarily around regulatory avoidance, many organizations now link halogen-free choices to broader environmental, social, and governance commitments, including restricted-substance management, lower-toxicological-risk materials, and end-of-life considerations. This does not mean sustainability claims automatically win bids, but it does raise the cost of ignoring them. Suppliers that can provide transparent material declarations, credible certification evidence, and consistent quality control are better positioned to serve customers whose internal approval processes increasingly scrutinize material composition alongside technical specs. In this sense, the market is being pulled forward by a combination of safety, performance, and disclosure expectations that reinforce one another.
Competitive Landscape and Leading Strategies
The competitive field in the halogen-free data cable market is characterized by a mix of large multinational cable groups, specialized industrial cable manufacturers, and regional players with strong local specification relationships. Concentration levels indicate a moderately consolidated environment, with the top three players holding a combined share in the low-thirty-percent range and the top five approaching the mid-forty-percent range. This structure suggests that scale, brand recognition, and broad portfolio coverage matter, but that meaningful opportunities remain for focused manufacturers with differentiated compound capabilities, application-specific product lines, or strong regional service networks. Market leadership is therefore less about sheer footprint than about the ability to win specifications in targeted verticals and to sustain compliance and supply reliability over repeated project cycles.
Leading international groups have invested in broad halogen-free and low-smoke portfolios that span data, communication, control, and industrial cables. Their strategic advantage often rests on multi-market coverage, established certification histories, and the ability to serve large infrastructure and utility programs with consistent documentation and global supply continuity. For customers running multi-site deployments or cross-border projects, this breadth reduces integration risk and simplifies vendor management. At the same time, these larger players must manage complexity across many product families and geographies, which can create slower response times in niche segments unless they maintain dedicated application teams and localized technical support. Their differentiation usually comes from portfolio completeness, standardized quality systems, and the credibility that comes from long-term presence in fire-safety-critical cable markets.
Specialist and regionally anchored manufacturers are pursuing a different game plan. Several Japanese and Korean producers have emphasized advanced insulation technologies and high-performance flame-retardant properties tailored to communication and specialty cables, often positioning on technical precision and application fit rather than sheer portfolio width. European manufacturers focused on industrial data transmission have built strong reputations around halogen-free control and signal cables designed for high-risk environments, where dynamic movement, chemical exposure, and stringent fire-safety requirements intersect. North American suppliers have concentrated on low-smoke halogen-free products for building, industrial, and enterprise use, frequently aligning product lines with regional certification expectations and construction practices. A notable recent example involves a company that introduced a halogen-free series designed for higher-temperature operation in AI data center contexts, signaling how targeted application focus can create a distinctive position even within a crowded market.
PW Consulting
Some companies are also using application-specific storytelling to translate material properties into project value. Trade-show presence and targeted showcases have highlighted halogen-free solutions for thermal-intensive environments and high-density power and data distribution, connecting product capabilities directly to the operational pain points of modern facilities. This approach reflects a broader shift from selling cable by technical spec alone toward selling a packaged assurance of safety, compliance, and operating suitability. Where this strategy succeeds, it creates stickier relationships because procurement and engineering teams see clear alignment between the cable choice and their facility's risk profile, maintenance expectations, and certification documentation needs.
Halogen-Free Flame Retardant TPE Market
Industry context is also shaping how these strategies evolve. Continuous raw material price volatility for petrochemical-based polymers, plasticizers, and flame retardants keeps cost management at the center of competitive positioning, favoring suppliers with stronger procurement leverage or more flexible formulations. At the same time, the availability of optional certification marks for halogen-free and low-smoke cable categories gives manufacturers a visible way to signal compliance, and this has begun to influence shortlisting in specification-driven projects. Regulatory pressure on hazardous substances continues to support the transition away from halogenated materials, while disclosure requirements around certain chemical substances add an extra layer of scrutiny to jacket and compound selection. In this environment, the competitive edge increasingly belongs to firms that can combine reliable certification, stable sourcing, and clear communication of product suitability for the intended environment.
Market evolution is likely to continue along two parallel tracks. On one hand, consolidation and portfolio expansion by larger players will keep raising the baseline for global coverage, documentation consistency, and supply continuity. On the other, differentiation will increasingly come from application depth: manufacturers that can prove superior suitability for data centers, industrial automation, or specific industrial Ethernet and signal-transmission use cases will capture pockets of stronger pricing and repeat specification wins. New entrants and niche specialists may not outscale the incumbents, but they can win by solving a specific problem better than the generalist alternative, particularly in segments where thermal tolerance, flexibility, or localized service matters more than broad catalog breadth.
Future Trends and Commercial Implications
Over the next three to five years, one defining trend will be the continued migration of halogen-free data cables from general compliance use toward performance-critical applications. As data center density rises and industrial networks adopt more demanding transmission requirements, cable specifications will increasingly weigh thermal behavior, mechanical robustness, and smoke characteristics together rather than treating fire safety as a separate checkbox. Suppliers that can demonstrate halogen-free designs capable of operating reliably in higher-temperature and higher-density environments will be better positioned to capture specification share in the fastest-growing application areas. The commercial implication is clear: product development and testing roadmaps should anticipate more stringent operating envelopes, not just broader adoption of existing formulations.
A second trend is the growing importance of certification visibility and material transparency in purchasing decisions. Optional certification marks and structured substance disclosure are likely to become more influential in competitive tenders, especially where facility operators, building owners, and public-sector buyers face internal sustainability and safety review processes. This trend creates an opportunity for manufacturers to reduce specification friction by making compliance documentation easy to access and verify. The associated risk is that any lapse in documentation consistency or certification currency can become a disproportionately large obstacle, because buyers increasingly treat these signals as proxies for overall quality discipline.
A third trend concerns supply chain recalibration. Continued raw material volatility and concentration risk in key input sources will push more manufacturers toward diversified sourcing, regional inventory strategies, and compound designs that reduce exposure to the most unstable materials. Commercial winners will likely be those that can offer a combination of stable pricing terms, dependable lead times, and credible alternative formulations when supply conditions tighten. At the same time, price sensitivity will remain real, particularly in price-competitive regional markets and cost-constrained public infrastructure projects, so the ability to balance resilience with competitiveness will separate durable players from those that simply ride the growth cycle.
The commercial opportunity embedded in these trends is not limited to product sales. There is growing value in application-focused consulting, specification support, and documentation services that help engineering and procurement teams match the right halogen-free solution to the right environment. Manufacturers and distributors that invest in technical enablement for specifiers can strengthen relationships and improve win rates, especially where multiple cable categories and compliance pathways create choice complexity. The risk is that companies treating halogen-free as a generic commodity may face margin pressure and specification churn, while those building application expertise and supply reliability capture more defensible positions.
Actionable Guidance for Decision-Makers
Manufacturers and product developers should prioritize compound flexibility and certification readiness as core competitive assets. Roadmaps that tie innovation to real application stressors, such as elevated temperature tolerance, dynamic movement in automation, or compact routing in high-density facilities, will resonate more strongly than incremental breadth alone. Securing diversified sourcing for critical flame retardants and polymers, while maintaining clear documentation pathways for regional compliance, will reduce vulnerability to supply shocks and shorten response time in specification cycles.
Investors evaluating exposure to this market should look beyond top-line growth and assess which companies have durable differentiation in application-specific solutions, reliable compliance records, and resilient input strategies. Businesses that can connect halogen-free cable offerings to higher-value environments, including AI-influenced data centers, industrial automation, and safety-sensitive public infrastructure, are more likely to sustain better pricing and repeat demand. Supply chain robustness and certification agility are also important indicators of which players can convert market growth into reliable margin performance.
Procurement and specification teams should treat halogen-free selection as a multi-factor decision rather than a simple compliance check. Evaluating thermal suitability, smoke-performance documentation, certification currency, and supplier sourcing stability alongside unit cost will lower the risk of project delays and post-installation issues. Where possible, requesting transparent material declarations and verifying the relevance of certification marks to the intended installation environment can strengthen long-term operating confidence and simplify future audit or retrofit decisions.
For organizations seeking to move from directional market understanding to detailed segment planning, granular data on product-type splits, application demand patterns, regional revenue distribution, and company-level positioning can materially improve go-to-market and sourcing decisions. The full research report provides deeper segmentation detail, company profiles, and scenario-ready data that support more precise strategy development across manufacturing, investment, and procurement use cases.
For detailed analysis of this topic, please visit the official page: Worldwide Halogen-free Data Cable Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com