

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Halogen-Free Data Cables Market: Why 8.55% CAGR and Asia Pacific Lead 2032 Growth

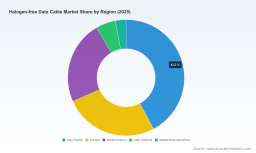
The Strategic Outlook: Navigating Opportunities in the Worldwide Halogen-free Data Cable Market
Market Overview and Critical Challenges
The global halogen-free data cable market has entered a phase of sustained expansion, driven by a convergence of safety regulations, technological infrastructure upgrades, and shifting enterprise procurement standards. Between 2020 and 2025, the market evolved from a niche compliance-driven segment into a mainstream component of modern data and communications infrastructure. Revenue growth has consistently outpaced broader cable sector averages, with the compound annual growth rate projected at 8.55 percent through 2032. This trajectory reflects more than regulatory tailwinds; it signals a structural realignment in how organizations design, deploy, and manage data transmission networks in environments where fire safety, air quality, and environmental impact carry direct operational and financial consequences.
The market size progression underscores this momentum. Revenue expanded from approximately 1,350 million in 2020 to over 2,003 million in 2025, and forward estimates place the market above 3,557 million by 2032. Such figures represent a market that has moved beyond early adoption cycles into a growth phase supported by recurring infrastructure investment cycles, data center build-outs, industrial network modernization, and commercial building retrofits. Yet the headline growth masks underlying friction points that decision-makers must navigate carefully. The expansion is not uniform across product categories or end-use environments, and the competitive playing field continues to reshape around material innovation, certification agility, and supply chain resilience.
One of the most pressing challenges confronting the sector is the tension between performance requirements and material constraints. Halogen-free compounds must simultaneously satisfy flame-retardant standards, low-smoke emissions criteria, mechanical durability, and signal integrity demands across diverse operating environments. Balancing these attributes often requires complex formulation chemistry, and manufacturers face trade-offs between cost, flexibility, and thermal performance. As applications push into higher-temperature environments and denser cable routing configurations, the margin for formulation errors narrows. Suppliers that cannot iterate quickly on compound engineering risk losing specification wins to competitors with more advanced material portfolios or faster testing and certification pathways.
A second structural challenge revolves around raw material volatility and geographic concentration. Key inputs for low-smoke halogen-free formulations, including specialized flame retardants and base polymers, remain exposed to petrochemical price cycles and regional supply disruptions. Certain critical flame retardant raw materials have historically experienced price spikes exceeding 40 percent during supply interruptions, disproportionately affecting smaller manufacturers and pricing-sensitive regional markets. This exposure complicates long-term contract negotiations, squeezes margins during peak construction or retrofit cycles, and creates opportunities for suppliers that can secure diversified sourcing or develop alternative compound architectures with lower exposure to concentrated supply nodes.
The third challenge lies in regulatory fragmentation and compliance complexity. While directives restricting hazardous substances and broader sustainability expectations have accelerated adoption of halogen-free solutions, the certification landscape remains multi-layered. Different regions and application verticals increasingly reference distinct testing protocols, smoke density thresholds, and material declaration requirements. For multinational operators, maintaining consistent product compliance across jurisdictions adds administrative overhead and can delay project timelines. At the same time, optional certification marks from recognized testing bodies are becoming more visible in procurement evaluations, giving buyers additional assurance while raising the bar for manufacturers that rely on older compliance arrangements.
Taken together, these dynamics define a market that is growing but not frictionless. The winners in the next cycle will be those that treat material science, regulatory alignment, and supply chain design as strategic capabilities rather than operational afterthoughts.
Key Drivers Shaping Market Trajectory
Technology innovation in insulation and jacket formulations represents one of the most consequential drivers of market expansion. Advances in halogen-free compound engineering have progressively closed the performance gap that once limited adoption in demanding environments. Modern formulations increasingly deliver improved flame-retardant behavior without sacrificing flexibility, tensile strength, or high-frequency signal transmission characteristics. This matters because data cable applications are no longer confined to conventional office or campus wiring; they now extend into high-density server halls, automated production lines, transportation hubs, and outdoor infrastructure where environmental stress and fire-risk considerations are more acute. As formulations mature, specifiers gain confidence that safety compliance does not require compromising on installation practicality or network performance.
Recent product introductions illustrate how this innovation axis is translating into market relevance. In early 2026, one manufacturer showcased a halogen-free power and data-related cable series engineered for continuous operation at elevated temperatures, explicitly targeting high-density AI data center power distribution systems and compliant with multiple UL standards. At a major data center industry event shortly afterward, the same company emphasized the thermal demands of AI-focused facilities as a core rationale for halogen-free designs with higher temperature tolerance. Such moves indicate that thermal management and compactness are becoming central design parameters, and that halogen-free cable portfolios are evolving to meet these requirements rather than serving solely as low-smoke alternatives.
Regulatory and standards activity continues to reinforce this direction. Environmental and hazardous-substance directives that restrict certain flame retardants and heavy metals in electrical and electronic equipment have long encouraged a shift toward halogen-free alternatives, but the effect is now deepening as enforcement expectations and buyer due-diligence practices become more rigorous. In parallel, recognized testing and certification organizations have expanded optional halogen-free and low-smoke certification marks aligned with international cable standards, giving procurement teams clearer visual and documentation cues during specification. For manufacturers, this regulatory environment is both a defensive requirement and a competitive lever: consistent compliance reduces market-access risk, while fast, credible certification can become a differentiator in tenders where safety documentation influences shortlisting.
Demand-side behavior is shifting as well, particularly in commercial enterprise and data-intensive facilities. Organizations are increasingly treating low-smoke, halogen-free cabling not as a premium add-on but as a baseline expectation for new builds, major renovations, and risk-sensitive retrofits. This change reflects a broader operational mindset in which indoor air quality, evacuation conditions, asset protection, and sustainability reporting are integrated into infrastructure planning rather than handled as separate compliance tasks. In data center environments, where uptime, density, and thermal constraints dominate decision-making, the request for halogen-free options has gained additional weight because facility designers seek solutions that address fire safety without introducing unnecessary chemical risk or downstream disposal complications. Industrial automation and public infrastructure projects show similar patterns, with engineering teams favoring cables that can withstand demanding installation conditions while meeting fire-safety expectations for occupied or publicly accessible spaces.
Supply chain and cost-structure dynamics are shaping how quickly these demand signals convert into orders. Petrochemical-based polymers, plasticizers, and flame retardants used in halogen-free compounds remain subject to price volatility, and certain key raw materials are sourced from concentrated geographic bases, creating susceptibility to disruptions and price spikes. This environment rewards manufacturers that have built dual-sourcing strategies, secured long-term supply agreements, or invested in compound formulations that reduce dependence on the most volatile inputs. It also creates a strategic opening for regional production and local inventory positioning, especially in markets where project timelines are tight and logistics delays can jeopardize build-out schedules. Companies that can demonstrate cost predictability alongside certified performance are gaining an edge in specification discussions, particularly when buyers are comparing total project cost rather than unit price alone.
Flame Retardant Cable Market
A further driver is the growing alignment between sustainability narratives and procurement realities. While earlier adoption was often framed primarily around regulatory avoidance, many organizations now link halogen-free choices to broader environmental, social, and governance commitments, including restricted-substance management, lower-toxicological-risk materials, and end-of-life considerations. This does not mean sustainability claims automatically win bids, but it does raise the cost of ignoring them. Suppliers that can provide transparent material declarations, credible certification evidence, and consistent quality control are better positioned to serve customers whose internal approval processes increasingly scrutinize material composition alongside technical specs. In this sense, the market is being pulled forward by a combination of safety, performance, and disclosure expectations that reinforce one another.
Competitive Landscape and Leading Strategies
The competitive field in the halogen-free data cable market is characterized by a mix of large multinational cable groups, specialized industrial cable manufacturers, and regional players with strong local specification relationships. Concentration levels indicate a moderately consolidated environment, with the top three players holding a combined share in the low-thirty-percent range and the top five approaching the mid-forty-percent range. This structure suggests that scale, brand recognition, and broad portfolio coverage matter, but that meaningful opportunities remain for focused manufacturers with differentiated compound capabilities, application-specific product lines, or strong regional service networks. Market leadership is therefore less about sheer footprint than about the ability to win specifications in targeted verticals and to sustain compliance and supply reliability over repeated project cycles.
Leading international groups have invested in broad halogen-free and low-smoke portfolios that span data, communication, control, and industrial cables. Their strategic advantage often rests on multi-market coverage, established certification histories, and the ability to serve large infrastructure and utility programs with consistent documentation and global supply continuity. For customers running multi-site deployments or cross-border projects, this breadth reduces integration risk and simplifies vendor management. At the same time, these larger players must manage complexity across many product families and geographies, which can create slower response times in niche segments unless they maintain dedicated application teams and localized technical support. Their differentiation usually comes from portfolio completeness, standardized quality systems, and the credibility that comes from long-term presence in fire-safety-critical cable markets.
Specialist and regionally anchored manufacturers are pursuing a different game plan. Several Japanese and Korean producers have emphasized advanced insulation technologies and high-performance flame-retardant properties tailored to communication and specialty cables, often positioning on technical precision and application fit rather than sheer portfolio width. European manufacturers focused on industrial data transmission have built strong reputations around halogen-free control and signal cables designed for high-risk environments, where dynamic movement, chemical exposure, and stringent fire-safety requirements intersect. North American suppliers have concentrated on low-smoke halogen-free products for building, industrial, and enterprise use, frequently aligning product lines with regional certification expectations and construction practices. A notable recent example involves a company that introduced a halogen-free series designed for higher-temperature operation in AI data center contexts, signaling how targeted application focus can create a distinctive position even within a crowded market.
PW Consulting
Some companies are also using application-specific storytelling to translate material properties into project value. Trade-show presence and targeted showcases have highlighted halogen-free solutions for thermal-intensive environments and high-density power and data distribution, connecting product capabilities directly to the operational pain points of modern facilities. This approach reflects a broader shift from selling cable by technical spec alone toward selling a packaged assurance of safety, compliance, and operating suitability. Where this strategy succeeds, it creates stickier relationships because procurement and engineering teams see clear alignment between the cable choice and their facility's risk profile, maintenance expectations, and certification documentation needs.
Halogen-Free Flame Retardant TPE Market
Industry context is also shaping how these strategies evolve. Continuous raw material price volatility for petrochemical-based polymers, plasticizers, and flame retardants keeps cost management at the center of competitive positioning, favoring suppliers with stronger procurement leverage or more flexible formulations. At the same time, the availability of optional certification marks for halogen-free and low-smoke cable categories gives manufacturers a visible way to signal compliance, and this has begun to influence shortlisting in specification-driven projects. Regulatory pressure on hazardous substances continues to support the transition away from halogenated materials, while disclosure requirements around certain chemical substances add an extra layer of scrutiny to jacket and compound selection. In this environment, the competitive edge increasingly belongs to firms that can combine reliable certification, stable sourcing, and clear communication of product suitability for the intended environment.
Market evolution is likely to continue along two parallel tracks. On one hand, consolidation and portfolio expansion by larger players will keep raising the baseline for global coverage, documentation consistency, and supply continuity. On the other, differentiation will increasingly come from application depth: manufacturers that can prove superior suitability for data centers, industrial automation, or specific industrial Ethernet and signal-transmission use cases will capture pockets of stronger pricing and repeat specification wins. New entrants and niche specialists may not outscale the incumbents, but they can win by solving a specific problem better than the generalist alternative, particularly in segments where thermal tolerance, flexibility, or localized service matters more than broad catalog breadth.
Future Trends and Commercial Implications
Over the next three to five years, one defining trend will be the continued migration of halogen-free data cables from general compliance use toward performance-critical applications. As data center density rises and industrial networks adopt more demanding transmission requirements, cable specifications will increasingly weigh thermal behavior, mechanical robustness, and smoke characteristics together rather than treating fire safety as a separate checkbox. Suppliers that can demonstrate halogen-free designs capable of operating reliably in higher-temperature and higher-density environments will be better positioned to capture specification share in the fastest-growing application areas. The commercial implication is clear: product development and testing roadmaps should anticipate more stringent operating envelopes, not just broader adoption of existing formulations.
A second trend is the growing importance of certification visibility and material transparency in purchasing decisions. Optional certification marks and structured substance disclosure are likely to become more influential in competitive tenders, especially where facility operators, building owners, and public-sector buyers face internal sustainability and safety review processes. This trend creates an opportunity for manufacturers to reduce specification friction by making compliance documentation easy to access and verify. The associated risk is that any lapse in documentation consistency or certification currency can become a disproportionately large obstacle, because buyers increasingly treat these signals as proxies for overall quality discipline.
A third trend concerns supply chain recalibration. Continued raw material volatility and concentration risk in key input sources will push more manufacturers toward diversified sourcing, regional inventory strategies, and compound designs that reduce exposure to the most unstable materials. Commercial winners will likely be those that can offer a combination of stable pricing terms, dependable lead times, and credible alternative formulations when supply conditions tighten. At the same time, price sensitivity will remain real, particularly in price-competitive regional markets and cost-constrained public infrastructure projects, so the ability to balance resilience with competitiveness will separate durable players from those that simply ride the growth cycle.
The commercial opportunity embedded in these trends is not limited to product sales. There is growing value in application-focused consulting, specification support, and documentation services that help engineering and procurement teams match the right halogen-free solution to the right environment. Manufacturers and distributors that invest in technical enablement for specifiers can strengthen relationships and improve win rates, especially where multiple cable categories and compliance pathways create choice complexity. The risk is that companies treating halogen-free as a generic commodity may face margin pressure and specification churn, while those building application expertise and supply reliability capture more defensible positions.
Actionable Guidance for Decision-Makers
Manufacturers and product developers should prioritize compound flexibility and certification readiness as core competitive assets. Roadmaps that tie innovation to real application stressors, such as elevated temperature tolerance, dynamic movement in automation, or compact routing in high-density facilities, will resonate more strongly than incremental breadth alone. Securing diversified sourcing for critical flame retardants and polymers, while maintaining clear documentation pathways for regional compliance, will reduce vulnerability to supply shocks and shorten response time in specification cycles.
Investors evaluating exposure to this market should look beyond top-line growth and assess which companies have durable differentiation in application-specific solutions, reliable compliance records, and resilient input strategies. Businesses that can connect halogen-free cable offerings to higher-value environments, including AI-influenced data centers, industrial automation, and safety-sensitive public infrastructure, are more likely to sustain better pricing and repeat demand. Supply chain robustness and certification agility are also important indicators of which players can convert market growth into reliable margin performance.
Procurement and specification teams should treat halogen-free selection as a multi-factor decision rather than a simple compliance check. Evaluating thermal suitability, smoke-performance documentation, certification currency, and supplier sourcing stability alongside unit cost will lower the risk of project delays and post-installation issues. Where possible, requesting transparent material declarations and verifying the relevance of certification marks to the intended installation environment can strengthen long-term operating confidence and simplify future audit or retrofit decisions.
For organizations seeking to move from directional market understanding to detailed segment planning, granular data on product-type splits, application demand patterns, regional revenue distribution, and company-level positioning can materially improve go-to-market and sourcing decisions. The full research report provides deeper segmentation detail, company profiles, and scenario-ready data that support more precise strategy development across manufacturing, investment, and procurement use cases.
For detailed analysis of this topic, please visit the official page: Worldwide Halogen-free Data Cable Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com