

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Flexible Intermediate Bulk Containers Market: Why 6.15% CAGR Reshapes Demand by 2032

Navigating the Global Flexible Intermediate Bulk Containers Market: Strategic Shifts and Commercial Opportunities Through 2032
Market Landscape and Critical Inflection Points
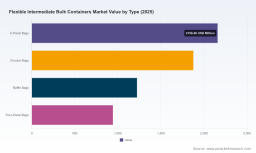
The worldwide flexible intermediate bulk containers (FIBC) market has demonstrated resilient growth, expanding from approximately $4.6 billion in 2020 to an estimated $6.2 billion in 2025. This trajectory reflects a compound annual growth rate of 6.15%, projecting the market to surpass $9.4 billion by 2032. The steady expansion underscores FIBCs' entrenched role in bulk material logistics, bridging the gap between rigid containers and loose bulk handling while offering cost efficiency, transport optimization, and adaptable load capacities.
Despite the upward baseline, the industry stands at a structural crossroads. The first challenge lies in raw material price volatility and supply chain fragility. Woven polypropylene remains the dominant fabrication material, capturing roughly 78 percent of volume share. However, regional pricing divergences have intensified. North American polypropylene prices climbed to $1.43 per kilogram in early 2026, marking a 20.2 percent increase, while European markets faced steeper pressure at $2.1 per kilogram. Such cost asymmetry compresses margins for manufacturers heavily reliant on virgin resin and complicates procurement planning for end-users operating across multiple geographies.
The second inflection point is regulatory tightening around circularity and extended producer responsibility. The European Union's Packaging and Packaging Waste Regulation, effective from February 2025 and applicable from August 2026, mandates EPR schemes with fees directly modulated by recyclability performance. This legislation extends to plastic-based packaging, including FIBCs, compelling manufacturers and brand owners to rethink design-for-recycling, material traceability, and end-of-life management. Companies that treat compliance as a checkbox risk higher fee exposure, while those embedding circularity into product architecture can translate regulatory pressure into cost advantages and procurement preference.
A third challenge emerges from trade policy friction. US imports of bulk bags under HTS Code 6305.32.0010 currently encounter approximately 8.4 percent tariffs alongside ancillary fees. This framework reshapes regional cost competitiveness, incentivizing localized production, supply chain dual-sourcing, or design modifications that reduce import dependency. For multinational buyers and manufacturers, tariff exposure is no longer a peripheral concern but a core variable influencing capacity siting, inventory strategy, and product mix decisions.
Core Drivers Reshaping the FIBC Value Chain
Technological Innovation in Material Performance and Circular Design
Material engineering continues to redefine what FIBCs can deliver beyond conventional load containment. The adoption of advanced woven polypropylene structures, reinforced lifting loops, and multi-layer barrier liners is addressing longstanding performance gaps in food safety, pharmaceutical compliance, and chemical containment. Recent product introductions illustrate how performance and circularity are converging rather than competing. In January 2025, Greif introduced the GCUBE Flex intermediate bulk container, featuring an enhanced aseptic liner and a two-layer polypropylene construction tailored for food and pharmaceutical handling. This launch signals a broader industry direction: FIBCs are evolving from commoditized bulk sacks into engineered packaging systems that meet stringent hygiene, traceability, and contamination-control requirements.
Simultaneously, recycled-content engineering is moving from pilot initiatives to commercial scale. Packem Umasree commissioned India's first fully integrated bottle-to-bag rPET FIBC manufacturing plant in Ahmedabad in 2025, achieving a capacity of 3.5 million bags. This facility demonstrates that post-consumer recycled inputs can be integrated into FIBC production at meaningful volumes without sacrificing structural integrity. Such capability expansion is critical because it creates upstream supply of recycled resin tailored to bulk bag specifications, reducing reliance on virgin resin price swings and enabling manufacturers to offer lower-carbon alternatives to procurement teams under internal or regulatory sustainability mandates.
Regulatory Momentum Accelerating Circular Economy Adoption
Policy is no longer a distant backdrop; it is actively reallocating competitive advantage. The EU PPWR's fee modulation based on recyclability performance creates a financial gradient that rewards designs with higher recycled content, simpler material assemblies, and documented end-of-life pathways. This regulatory logic is reinforced by growing market expectations that packaging should incorporate post-consumer recycled material wherever technically feasible. The result is a dual pressure: manufacturers must redesign products for recyclability while simultaneously securing reliable recycled feedstock streams.
Market reactions confirm this shift. Gravis launched the Sustainabulk 100 percent recycled PET FIBC in May 2025, claiming up to a 70 percent carbon footprint reduction compared with virgin polypropylene bags. This product positioning reflects an emerging commercial logic in which environmental performance becomes a procurement differentiator, particularly for chemical, food, and pharmaceutical users who must report on lifecycle emissions or comply with customer sustainability clauses. For producers, the opportunity lies in certifying recyclability claims, standardizing recycled-content grades, and aligning product documentation with audit requirements from downstream buyers.
Demand-Side Transformation in Application Sectors
End-user behavior is shifting from viewing FIBCs as interchangeable transport units to selecting them based on sector-specific performance, compliance, and sustainability criteria. Chemicals remain a major application area, driven by the need for reliable bulk handling of dry flowable materials, powders, and granular substances. Food and pharmaceutical demand is intensifying around contamination control, liner integrity, and inspection-friendly designs. Agriculture and construction continue to generate steady volume, yet even these traditional segments increasingly evaluate bulk bag suppliers on total cost of ownership, delivery reliability, and environmental footprint.
Worldwide Industrial Flexible Hose Market
This segmentation is reshaping procurement behavior. Buyers are more willing to pay for engineered features such as Type C and Type D conductive configurations, custom spout and top designs, or aseptic liners when those features reduce operational risk, improve handling efficiency, or satisfy regulatory expectations. For manufacturers, the implication is clear: competitive differentiation is migrating from unit price toward specification reliability, compliance documentation, and lifecycle performance. Suppliers that can articulate application-specific value and evidence-based sustainability attributes are gaining preference in tenders and long-term supply agreements.
Cost Structure Reconfiguration and Regional Production Dynamics
Cost structures are being recalibrated by the intersection of raw material inflation, energy differentials, and trade policy. Polypropylene price divergence between North America and Europe creates uneven cost bases across manufacturers, prompting some to optimize production footprints, adjust pricing mechanisms, or shift toward blended or recycled resin mixes where feasible. At the same time, tariff exposure on bulk bag imports into the United States encourages regional capacity expansion or nearshore sourcing strategies. Several US-based manufacturers have emphasized standard and custom FIBC production with domestic or regional supply chains, aligning cost predictability with faster fulfillment and lower logistics risk.
For the broader market, this dynamic favors players that can balance scale with flexibility. Large producers with integrated recycling loops, diversified resin sourcing, and multi-region manufacturing can better absorb input volatility and tariff effects. Smaller or highly specialized manufacturers can compete by offering rapid customization, food-grade certifications, and application-engineered solutions that larger generalist players may standardize away. The net effect is a market in which cost leadership and differentiation are increasingly interdependent rather than mutually exclusive.
Competitive Landscape and Strategic Positioning
The FIBC industry remains moderately fragmented, with a five-firm concentration ratio of about 24 percent and a three-firm ratio near 18 percent. This fragmentation provides room for regional specialists, application-focused manufacturers, and export-oriented producers, but it also intensifies the need for clear strategic positioning. Leading companies are not competing solely on bag specifications; they are building value through service architecture, recycling infrastructure, and sector-specific credibility.
Greif exemplifies a strategy centered on circular reconditioning and engineered product platforms. By reporting the reconditioning or recycling of over 4.5 million containers across its global industrial packaging network in September 2025, Greif has reinforced a circular economy narrative that links reuse capability with cost recovery and sustainability metrics. Combined with the GCUBE Flex launch targeting food and pharmaceutical performance, this dual emphasis on circularity and specialized containment illustrates how incumbents can defend scale while moving up the value curve. Berry Global maintains a broad flexible packaging portfolio, leveraging durable woven polypropylene designs across industrial, chemical, food, and construction segments. Its breadth supports cross-segment supply resilience, though it also requires disciplined specification management to avoid commoditization.
FIBC (Flexible Intermediate Bulk Container) Market
Several producers are building differentiation through application focus and manufacturing localization. Conitex Sonoco emphasizes US-based BulkSak and FIBC production, offering standard, custom, food-grade, and on-demand inventory programs that appeal to industrial buyers prioritizing responsiveness and compliance. LC Packaging International BV anchors its positioning in European and global distribution with standard and customized bulk bags, benefiting from proximity to markets facing stringent recyclability expectations. Global-Pak Inc. and Palmetto Industries International Inc. concentrate on high-performance woven polypropylene containers and tailored top and spout configurations for industrial use, respectively, reflecting demand for load stability and handling efficiency. JohnPac, LLC extends its differentiation across the full FIBC specification range, including 4-panel, baffle, circular, food-grade, Type C, and Type D bags, enabling customers to source multiple technical variants from a single supplier relationship.
Export-oriented manufacturers from India and Turkey are expanding their relevance by combining cost efficiency with growing specification capabilities. Rishi FIBC Solutions Pvt. Ltd. serves chemical, food, pharmaceutical, and agricultural applications with an export focus, while Isbir Sentetik Dokuma Sanayi A.S. produces woven polypropylene fabrics and FIBCs with significant export-oriented production. These players benefit from relative input cost advantages and scale flexibility, though sustained competitiveness depends on consistent quality, certification reliability, and the ability to meet increasingly demanding recycled-content and traceability expectations. Codefine's emphasis on sustainable options, including recycled PET bulk bags, reflects another competitive vector: offering lower-carbon alternatives within a standard product portfolio. In the United States, manufacturers such as Bulk Lift International LLC, Langston Companies Inc., Halsted Corporation, and Dewitt Company maintain specialized bulk bag production for industrial, chemical, food, and construction markets, often competing on customization, capacity reliability, and regional fulfillment speed.
The competitive outlook points toward selective consolidation in mature regions alongside continued emergence of niche specialists. Larger players may pursue acquisitions to secure recycling infrastructure, geographic coverage, or application expertise. Mid-tier manufacturers may differentiate by depth in food-grade, conductive, or aseptic solutions. New entrants are most likely to succeed where they solve a specific procurement pain point: verified recycled content, improved liner performance, faster custom turnaround, or documented compliance with evolving EPR requirements. The market is moving toward a landscape in which scale, circular capability, and application credibility must be managed together rather than in isolation.
Forward Outlook: Trends, Opportunities, and Risks
Over the next three to five years, the FIBC market is likely to be shaped by three interconnected trends. First, circular design and recycled-content integration will shift from optional features to baseline expectations in many procurement categories. As EPR fee modulation takes effect and customer sustainability requirements deepen, manufacturers that can reliably supply certified recycled-content FIBCs and document recyclability performance will gain preference in competitive bidding. This creates opportunities for producers with access to rPET or post-consumer recycled polypropylene streams, as well as for service models that combine bulk bag supply with reconditioning or return logistics.
Second, regulatory and tariff divergence will accelerate regionalized supply chains and segmented product strategies. The EU PPWR implementation timeline and ongoing US import duties make it increasingly important to align production footprints, resin sourcing, and product specifications with destination-market requirements. Manufacturers that can offer region-appropriate grades, adjusted recycled-content mixes, and transparent compliance documentation will reduce friction for multinational buyers and protect margin stability in volatile input environments. This trend favors suppliers with multi-region capacity or strong partner networks that can localize fulfillment without sacrificing specification consistency.
Third, application-engineered FIBCs will capture a growing share of value as buyers prioritize performance reliability and compliance over lowest unit cost. Food and pharmaceutical segments will continue to drive demand for aseptic liners, contamination-control features, and inspection-friendly designs. Chemical and construction sectors will reward durable woven structures, tailored lifting configurations, and consistent load integrity. The commercial opportunity lies in defining clear grade families, linking them to documented performance attributes, and supporting procurement teams with specification guidance that reduces risk and simplifies vendor consolidation. At the same time, uncertainty persists around resin price trajectories, the pace of recycled feedstock availability, and the practical interpretation of EPR fee modulation across jurisdictions. Companies that monitor these variables closely and build flexible sourcing and product architectures will be better positioned to manage downside risk while capturing upside from sustainability-driven demand.
Strategic Actions for Decision Makers
For FIBC manufacturers, the priority is to translate circularity and application performance into repeatable product architectures rather than isolated launches. Establish clear recycled-content grades, secure traceable feedstock arrangements, and align product documentation with EPR and customer audit expectations. Where feasible, integrate reconditioning or return pathways that convert sustainability claims into operational value and improve total cost positioning. At the same time, protect margin resilience by diversifying resin sourcing and aligning production footprints with the regulatory and tariff realities of key destination markets.
PW Consulting
For investors, the most attractive opportunities are likely in companies that combine scale with circular capability or that occupy strong positions in high-specification segments such as food-grade, pharmaceutical, and conductive FIBCs. Due diligence should focus on recycled-content supply security, certification integrity, regional cost structures, and exposure to tariff or EPR-related cost shifts. Capital allocation should favor businesses that can demonstrate sustainable differentiation beyond commodity bag pricing, particularly where sustainability attributes are already influencing procurement decisions.
For procurement and supply chain leaders, the strategic task is to move beyond unit-price comparison toward total-cost and risk-based evaluation. Assess suppliers on specification reliability, compliance documentation, recycled-content options, and fulfillment consistency across regions. Where possible, consolidate categories around suppliers that can provide multiple FIBC types with clear performance grades and verified sustainability attributes, reducing vendor complexity while improving traceability. Procurement teams should also pressure-test supply continuity plans against raw material volatility and tariff exposure, ensuring that lower headline pricing does not obscure logistics risk or future compliance costs.
For decision makers seeking to translate these dynamics into actionable plans, detailed segmentation data, regional cost modeling, specification benchmarking, and supplier evaluation frameworks can materially accelerate strategy development. Access to granular market intelligence supports more precise capacity planning, product mix decisions, and procurement negotiations, particularly in a market where regulatory timelines, resin pricing, and circular-content expectations are changing simultaneously.
For detailed analysis of this topic, please visit the official page: Worldwide Flexible Intermediate Bulk Containers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com