

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Worldwide Fluorozirconic Acid Market: Asia Pacific's 4.6% CAGR Leads to $71.8M by 2032

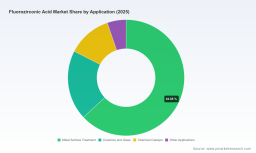
Scaling Production, Navigating Volatility: Strategic Dynamics in the Global Fluorozirconic Acid Market
The worldwide fluorozirconic acid market has entered a phase of measured expansion, characterized by steady revenue growth, shifting regional purchasing patterns, and evolving supply chain economics. From 2020 through 2025, the sector demonstrated consistent demand absorption across industrial and specialty applications, with total market revenue reaching approximately 52.4 million in the most recent base year. Looking ahead to the forecast horizon ending in 2032, the market is projected to maintain a compound annual growth rate of 4.6 percent, gradually scaling toward the mid-70 million range. This trajectory reflects a market that is neither in hyper-growth nor in structural decline, but rather in a maturation stage that rewards disciplined capacity planning, application diversification, and supply chain resilience.
Current industry conditions present a set of interlocking challenges that will define competitive outcomes over the next several years. First, raw material input volatility remains a persistent pressure point. The primary feedstocks required for fluorozirconic acid synthesis have experienced notable price fluctuations, particularly in key producing regions, forcing manufacturers to navigate margin compression while attempting to preserve pricing stability for downstream buyers. Second, regulatory and environmental compliance requirements are tightening across multiple jurisdictions, altering procurement standards and raising the operational baseline for production facilities. Third, the market is experiencing a gradual realignment in how purchasing organizations evaluate supply partners, shifting from pure price optimization toward reliability, technical support, and consistent specification compliance. These forces are compelling companies to recalibrate their operating models rather than rely on historical growth assumptions.
The broader market structure also reflects meaningful concentration dynamics. A relatively small group of established participants accounts for a substantial share of total industry revenue, indicating that scale, technical reputation, and long-standing distribution networks continue to exert strong influence on commercial positioning. At the same time, the presence of mid-tier manufacturers and regional suppliers signals an ecosystem that retains room for specialized entrants, particularly those capable of serving specific application verticals or concentration requirements. This combination of concentration and fragmentation creates a competitive environment where differentiation is increasingly tied to execution quality rather than product novelty alone.
For executives and strategic planners, the immediate implication is clear: the market rewards operators who can balance cost discipline with service reliability. Companies that treat fluorozirconic acid as a commodity input risk exposure to margin swings and supply disruptions, while those that integrate the chemical into broader application ecosystems—such as surface treatment workflows, specialty glass processing, or catalyst formulations—can capture more defensive margin profiles. Similarly, procurement teams face a market in which supplier selection has become a strategic decision, not a routine purchasing task. Understanding where capacity is expanding, where feedstock economics are shifting, and how regional demand is evolving will separate organizations that simply absorb cost pressure from those that convert market dynamics into commercial advantage.
Key Drivers Reshaping Market Trajectory
Market movement in fluorozirconic acid is being shaped by a combination of technical, regulatory, demand-side, and cost-structure factors. These drivers do not operate in isolation; they interact in ways that determine which applications grow, which production regions gain leverage, and how suppliers position themselves for the forecast period.
PW Consulting
Technical Innovation and Application Expansion
Advancements in process efficiency and application engineering are gradually reshaping how fluorozirconic acid is produced and utilized. On the production side, manufacturers are increasingly focused on optimizing concentration consistency, reducing impurity profiles, and improving batch-to-batch reliability. These improvements matter particularly for industries where chemical performance directly affects downstream outcomes, such as metal surface treatment and optical glass manufacturing. In parallel, application-side innovation is expanding the relevance of fluorozirconic acid beyond legacy use cases. Surface treatment formulations continue to evolve as manufacturers seek stronger corrosion resistance, better adhesion characteristics, and more controlled conversion coating performance. In ceramics and glass segments, the chemical's functional role in specialized processing has supported steady demand from producers looking to maintain material quality while managing cost structures.
For businesses, this means the value of fluorozirconic acid is increasingly tied to performance reliability rather than volume alone. Suppliers that can demonstrate consistent specifications, provide technical guidance, and adapt to formulation changes are better positioned to retain and expand account relationships. Conversely, buyers that standardize on poorly characterized supply risk quality variability that can cascade into production inefficiencies.
Policy and Regulatory Environment
Regulatory expectations are becoming a more prominent factor in procurement and manufacturing decisions. Environmental compliance, chemical handling standards, and industrial safety requirements are influencing how producers operate and how end-users qualify suppliers. In several regions, tighter oversight of fluoride-related chemicals and related industrial processes has raised the bar for documentation, traceability, and operational controls. These requirements are not uniform across markets, which creates a differentiated landscape where companies with stronger compliance systems can use them as a commercial asset rather than viewing them purely as cost centers.
The policy environment also interacts with trade dynamics. Cross-border supply arrangements are increasingly evaluated through the lens of regulatory alignment, customs considerations, and long-term supply assurance. As a result, organizations that depend on imported fluorozirconic acid are placing greater emphasis on supplier consistency, certification coverage, and regional availability. This dynamic favors established distributors and manufacturers with clear compliance records, while raising the entry threshold for less-documented supply sources.
Demand-Side Behavior and Industrial Purchasing Patterns
End-user demand is evolving in ways that influence both volume and purchasing behavior. In metal surface treatment, continued industrial activity and maintenance-driven coating requirements sustain baseline consumption, while performance expectations push buyers toward products that deliver predictable results across varied substrates and process conditions. In specialty applications such as ceramics, glass, and chemical catalysis, demand tends to be more sensitive to production cycles, capital investment patterns, and formulation changes. This creates a market where some segments behave as steady industrial consumables, while others are more cyclical or innovation-driven.
A notable shift in purchasing behavior is the growing preference for suppliers who can support application-specific needs rather than simply offer the lowest unit price. Procurement teams are increasingly weighing specification consistency, availability, technical communication, and delivery reliability. This trend rewards suppliers with stronger customer-facing capabilities and creates an opportunity for manufacturers to differentiate through service, not just chemical grade.
Supply Chain and Cost Structure Dynamics
Cost structure remains one of the most important market levers, and feedstock economics are central to that picture. Hydrofluoric acid, a primary input for fluorozirconic acid production, has experienced meaningful price movements in recent periods. In the Chinese domestic market, prices moved upward over the course of 2025, reflecting broader input cost pressures and regional supply conditions. By early 2026, fluorozirconic acid-linked feedstock pricing in China was observed in a higher range than historical norms, tightening cost calculations for producers and affecting the economics of export-oriented supply. In Europe, intra-EU hydrofluoric acid transaction prices remained elevated at the start of 2026, sitting substantially above pre-2019 levels and reinforcing cost challenges for regional manufacturers.
At the same time, upstream zirconium mineral availability has provided a degree of feedstock foundation for zirconium-based chemicals. Global mine production of zirconium mineral concentrates rose to an estimated 1.5 million tonnes in 2024, supporting broader feedstock availability for downstream chemical processing. This does not eliminate cost volatility, but it does indicate that the raw material base underpinning zirconium chemistry remains functional and, in aggregate, expanding. The market implication is nuanced: availability is not the primary constraint, but price transmission from feedstock markets to finished fluorozirconic acid is a persistent factor that operators must manage through pricing strategy, contract structuring, and production efficiency.
Competitive Landscape and Strategic Positioning
The competitive environment in fluorozirconic acid is defined by a mix of established manufacturers, regional producers, and distribution-focused suppliers. Market concentration is significant, with a relatively small set of participants capturing a majority share of industry revenue. This structure reflects the importance of production experience, specification reliability, and established commercial relationships in a market where downstream users place high value on consistency.
European-based manufacturers continue to hold a recognized position in the market, particularly where high-quality production standards and long-standing supply track records matter. Companies operating from Spain and the broader European region have built reputations around industrial-grade reliability and global distribution capability, often aligning their commercial positioning with compliance, product consistency, and established customer relationships. Their strategic advantage typically lies in perceived quality assurance and the ability to serve industrial customers that prioritize specification stability over aggressive price competition.
Hydro Fluoric Acid Market
Chinese manufacturers represent a substantial portion of the supply landscape, reflecting both domestic demand and export-oriented production. Several firms based in Foshan, Nantong, Hunan, Yixing, and other industrial centers supply fluorozirconic acid for metal surface treatment, optical glass, fluorozirconate production, and related industrial applications. These producers often compete on a combination of pricing, production scale, and the ability to serve multiple downstream verticals. Their market role is shaped by access to feedstock inputs, production flexibility, and the capacity to support both wholesale and industrial-grade requirements. In many cases, Chinese suppliers have become integral to global supply chains by offering a broad range of concentration options and application-aligned product formats.
Outside of Europe and China, other regional players contribute to the market's diversity. Indian manufacturers supplying multiple concentration grades for technical applications have built export-oriented businesses that serve a range of international buyers. In the United States, certified distributors and global raw material suppliers provide fluorozirconic acid through established logistics and quality management frameworks, often positioning themselves as reliable intermediaries for industrial customers that need documented compliance and consistent availability. In the United Kingdom, distributors focused on bulk industrial packaging and customer-specific delivery configurations add further supply chain flexibility, particularly for buyers that prioritize handling convenience and large-volume order execution.
The strategic differences among these participants are instructive. Some compete primarily through production efficiency and price competitiveness; others differentiate through certification, documentation, technical support, or specialized packaging and logistics. The most resilient players tend to combine several of these strengths rather than rely on a single attribute. A manufacturer that can offer consistent specifications, maintain dependable lead times, and respond to application-specific requirements is better positioned than one competing on price alone, especially in a market where feedstock cost volatility can quickly erode thin margins.
Market evolution is likely to continue along two parallel paths. On one hand, consolidation pressure may intensify among smaller operators facing rising compliance costs, feedstock volatility, and the need for stronger quality systems. On the other hand, the market retains space for specialized or regional entrants that can serve distinct application needs, offer differentiated concentration grades, or provide strong local service and logistics. New entry is not impossible, but success will increasingly depend on credible production capability, clear quality assurance, and the ability to integrate into downstream procurement systems. The overall pattern suggests a landscape that is concentrated at the top, active in the middle, and selective at the edges.
Forward-Looking Trends and Commercial Implications
Over the next three to five years, several trends are likely to shape how the fluorozirconic acid market develops and where commercial opportunities emerge.
One important trend is the continued elevation of supply chain reliability as a competitive differentiator. As feedstock costs remain sensitive and regulatory expectations persist, buyers will place greater weight on suppliers that can deliver predictable availability and consistent specifications. This will favor organizations that invest in production discipline, inventory planning, and transparent communication with customers. For suppliers, the opportunity lies in building long-term account trust rather than competing transaction-by-transaction.
A second trend is gradual application-driven demand evolution. Metal surface treatment is expected to remain a core demand anchor, but growth will be influenced by industrial maintenance cycles, coating performance expectations, and the willingness of manufacturers to standardize on reliable chemical inputs. In ceramics, glass, and catalyst-related uses, demand will likely track more closely with specialty production activity and formulation innovation. This creates an environment where companies with stronger application knowledge and closer customer collaboration can capture more resilient demand than those relying solely on commodity-style selling.
Zirconium Oxychloride Market
A third trend is the ongoing pressure on cost management and pricing strategy. Feedstock volatility, regional price divergence, and compliance-related operating costs will continue to shape margin dynamics. Businesses that succeed will need to combine efficient production, disciplined commercial pricing, and flexible contract structures. There is also an opportunity for suppliers to create value through concentration specialization, packaging optimization, and technical service, all of which can support healthier margin profiles in a market where pure price competition is increasingly risky.
Potential risks should not be overlooked. Feedstock price shocks, changes in regulatory interpretations, trade friction, or abrupt shifts in downstream demand could disrupt otherwise steady market conditions. In addition, overconcentration of supply dependence on a limited number of sources can heighten vulnerability for buyers and create pricing leverage for suppliers during tight periods. Organizations that monitor these risks early and build contingency options will be better prepared to navigate periods of uncertainty.
Strategic Guidance for Decision-Makers
Market participants should approach fluorozirconic acid with a clear understanding of where value is created and where exposure accumulates. For manufacturers and suppliers, the priority is to strengthen production consistency, compliance readiness, and customer-facing technical capability. Differentiation through specification reliability and service responsiveness is likely to be more durable than competing on price alone, especially given ongoing feedstock cost volatility and the importance of long-term buyer trust.
For investors and corporate development teams, the market warrants attention to companies with credible production bases, diversified application exposure, and the ability to manage input cost transmission. The most attractive positions are often those that combine scale with application relevance and supply chain discipline, rather than those that depend on a single thin-margin commodity pathway. Monitoring feedstock trends, regional pricing divergence, and capacity changes will be essential for assessing where competitive advantage is likely to intensify or erode.
For procurement and operations leaders, supplier selection should be treated as a strategic function. Evaluating suppliers on specification consistency, availability, documentation, and technical support can reduce downstream risk and improve overall process stability. Diversifying supply options where feasible, understanding regional feedstock dynamics, and aligning purchasing terms with realistic cost conditions can help organizations avoid overreliance on fragile supply arrangements.
Detailed segment-level data, regional demand patterns, concentration-grade breakdowns, and application-specific volume dynamics can materially improve planning quality, but they require a more granular view than market-level indicators alone can provide. Decision-makers seeking to translate these trends into precise sourcing, investment, or product strategy will benefit from fuller market detail, including the kind of segmented analysis that supports scenario planning and competitive benchmarking. For teams that need deeper visibility into submarket size, application demand splits, regional pricing context, and company-level positioning, the complete PW Consulting research report provides the structured detail necessary to move from directional insight to operational decision-making.
For detailed analysis of this topic, please visit the official page: Worldwide Fluorozirconic Acid Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com