

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Multivalent Pneumococcal Conjugate Vaccine Market: Why 8.82% CAGR and 19.97B Growth Reshape Strategy

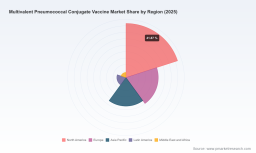
Worldwide Multivalent Pneumococcal Conjugate Vaccine Market: Strategic Trends and Commercial Opportunities Through 2032
Market Overview and Core Challenges
The global multivalent pneumococcal conjugate vaccine market has demonstrated consistent expansion, growing from approximately $7.4 billion in 2020 to an estimated $11.1 billion in 2025. Projections indicate the market will reach nearly $20 billion by 2032, reflecting a compound annual growth rate of 8.82 percent. This trajectory underscores the essential role these vaccines play in global public health, as well as the increasing prioritization of pneumococcal disease prevention across diverse population segments. The market structure remains highly concentrated, with a small number of established players controlling the majority of revenue, creating both barriers to entry and opportunities for strategic differentiation.
Despite this favorable growth outlook, the industry faces several structural challenges that will shape competitive dynamics in the coming years. First, cold chain logistics represent a significant cost and operational burden. Pneumococcal conjugate vaccines require strict storage at 2-8°C, with cold chain expenses accounting for approximately 50 to 55 percent of total distribution costs. In developing regions, temperature excursions can compromise 15 to 20 percent of delivered doses, creating reliability gaps that undermine immunization program effectiveness and increase total cost of ownership for procurement agencies.
PW Consulting
Second, regulatory and reimbursement landscapes are evolving rapidly, creating both opportunities and compliance complexity. As of May 2025, 170 of 194 WHO member states have incorporated pneumococcal conjugate vaccines into infant national immunization programs, with 15 additional countries planning introduction. While this expansion drives volume, it also intensifies price pressure in publicly funded markets and requires manufacturers to navigate diverse regulatory pathways, health technology assessment requirements, and tender processes. Reimbursement policies continue to shift, particularly for adult indications, where recommendations such as the CDC ACIP update endorsing 21-valent pneumococcal conjugate vaccine use for adults 50 years and older illustrate how guideline changes can reshape demand patterns overnight.
Third, the expiration of key intellectual property protections introduces competitive disruption. Pfizer's patent for Prevnar 13 is set to expire in 2026, potentially enabling biosimilar or generic 13-valent products to enter the market. This event will test the resilience of incumbent franchise revenues and may accelerate pricing renegotiation in both pediatric and adult segments. Companies that rely heavily on legacy valency products will need to manage portfolio transitions carefully, while new entrants may find targeted opportunities in markets where price sensitivity is high and regulatory pathways for follow-on products are well defined.
Key Growth Drivers
Technological Innovation and Next-Generation Valency Profiles
The most transformative driver in the market is the advancement of higher-valent formulations and novel manufacturing platforms. The shift from 13-valent and 15-valent products toward 20-valent and 21-valent candidates reflects a clear commercial and clinical imperative: broader serotype coverage addresses residual disease burden and strengthens value propositions for both pediatric and adult immunization programs. Recent clinical data support this direction. In September 2025, Merck reported positive Phase 3 STRIDE-13 results evaluating CAPVAXIVE, a 21-valent pneumococcal conjugate vaccine, in children and adolescents at increased risk of pneumococcal disease. This milestone expands the potential indication space for higher-valent products beyond adult populations and signals that broader coverage can be achieved without compromising safety or immunogenicity profiles.
Parallel innovation is occurring in manufacturing technology. Companies such as Inventprise are advancing 25-valent pneumococcal conjugate vaccine candidates using automated manufacturing processes designed to reduce cost and improve scalability for low- and middle-income countries. Meanwhile, Vaxcyte has reported positive topline results from a Phase 2 dose-finding study of VAX-24, a 24-valent candidate, in healthy infants compared to Prevnar 20. These developments suggest that next-generation platforms may eventually offer both broader coverage and more favorable production economics, potentially reshaping cost structures and enabling access in markets that have historically been underserved.
Policy Momentum and National Immunization Program Expansion
Public health policy remains a primary demand catalyst. The widespread adoption of pneumococcal conjugate vaccines into infant national immunization programs across 170 WHO member states creates a stable, volume-driven baseline for market growth. Countries planning introduction represent additional addressable demand, particularly where Gavi support or bilateral funding mechanisms reduce budget constraints. Beyond pediatric programs, adult immunization guidelines are expanding, driven by growing recognition of pneumococcal disease burden in older populations and individuals with underlying risk factors. The CDC ACIP recommendation supporting 21-valent pneumococcal conjugate vaccine use for adults 50 years and older exemplifies how guideline evolution can unlock new commercial pathways and stimulate adult market growth, which currently represents a substantial portion of total revenue.
Demand-Side Shifts and Demographic Trends
Demand patterns are being reshaped by demographic change and heightened awareness of pneumococcal disease across the lifespan. Aging populations in developed markets increase the absolute number of adults eligible for vaccination, while improved disease surveillance and physician education drive higher recommendation rates. In pediatric populations, the focus has shifted from basic serotype coverage to comprehensive protection that minimizes residual invasive disease and non-invasive pneumonia. Healthcare providers and procurement agencies increasingly evaluate vaccines based on total value, including serotype match to local epidemiology, dosing schedules, and real-world effectiveness data. This shift compels manufacturers to generate robust post-marketing evidence and to align product positioning with the specific needs of national immunization technical advisory groups and procurement decision-makers.
Supply Chain Evolution and Cost Structure Dynamics
Supply chain resilience has emerged as a strategic priority following global disruptions that exposed vulnerabilities in centralized manufacturing and distribution models. Complex conjugation technology and capsular polysaccharide production have historically limited the supplier base to organizations with moderate-to-high technical capability. However, new entrants have increased supply diversity since 2019, reducing single-source dependency and introducing competitive pressure on pricing and capacity allocation. At the same time, cold chain requirements continue to inflate distribution costs, particularly in regions with fragmented logistics infrastructure. Companies that invest in temperature-stable formulations, localized fill-finish capabilities, or partnerships with logistics providers specializing in vaccine distribution can differentiate on reliability and total cost, turning a structural cost burden into a competitive advantage.
Competitive Landscape and Leading Strategies
The competitive environment is defined by a small group of multinational innovators holding dominant market positions, complemented by a growing set of regional manufacturers and technology-driven newcomers. Incumbents have built strong franchises around established valency profiles and extensive clinical databases, while newer participants are pursuing differentiation through higher valency, novel platforms, or cost-optimized manufacturing. Understanding the strategic positioning of key players clarifies where value is being created and where competitive pressure is likely to intensify.
Incumbent Strategies and Franchise Management
Pfizer maintains a leading position through its Prevnar 13 and Prevnar 20 portfolios, with the 20-valent product approved for prevention of invasive pneumococcal disease and pneumonia across pediatric and adult populations. The company's strategy centers on leveraging deep clinical evidence, established relationships with immunization programs, and global commercial infrastructure. However, the 2026 patent expiration for Prevnar 13 introduces portfolio management complexity, requiring proactive lifecycle planning, potential label expansions, and strategic pricing approaches to defend market share as follow-on products emerge.
Merck has pursued a differentiated path with VAXNEUVANCE, a 15-valent product for infants, children, and adults, and CAPVAXIVE, a 21-valent vaccine approved for adults 18 and older. The positive Phase 3 STRIDE-13 data in pediatric and adolescent populations at increased risk could broaden the commercial footprint of CAPVAXIVE and strengthen Merck's position in higher-valent segments. By extending indication potential beyond adults, Merck is positioning its portfolio to capture demand from both demographic groups while leveraging the clinical credibility of its broader vaccine franchise.
Collaborative Development and Next-Generation Pipelines
Collaboration has become a defining feature of competitive strategy, particularly for companies seeking to accelerate development and share commercialization risk. Sanofi and SK bioscience expanded their agreement in January 2025 to develop, license, and commercialize next-generation pneumococcal conjugate vaccines, including a 21-valent candidate for pediatric and adult populations. Sanofi initiated its Phase 3 program for this 21-valent candidate in December 2024, marking the first pneumococcal conjugate vaccine candidate with more than 20 serotypes to enter Phase 3 in infants and toddlers. SK bioscience supported this effort by expanding its L HOUSE production facility in Andong in June 2025, strengthening manufacturing capacity to support global supply. This partnership illustrates how combining development expertise, manufacturing scale, and regional capabilities can accelerate time-to-market and expand geographic reach.
Travelers Vaccines Market
Regional Manufacturers and Value-Based Positioning
Regional players are carving out positions by focusing on affordability, supply reliability, and alignment with domestic immunization priorities. GlaxoSmithKline markets Synflorix, a 10-valent product primarily used in pediatric national immunization programs, maintaining a presence in markets where established coverage and cost considerations favor this valency profile. Serum Institute of India produces Pneumosil, an affordable 10-valent conjugate vaccine for pediatric immunization, with additional candidates in development, reinforcing its role as a high-volume supplier for price-sensitive markets. Chinese manufacturers including Walvax Biotechnology, Beijing Minhai Biological Technology, Shenzhen Kangtai Biological Products, and Chengdu Institute of Biological Products are active in producing and developing 13-valent and other pneumococcal conjugate vaccines, primarily for domestic demand. Their continued investment signals a broader trend of regional supply localization and the potential for expanded export capacity as manufacturing scale and regulatory experience grow.
Emerging Entrants and Platform-Based Disruption
New entrants are pursuing higher-valent candidates and innovative manufacturing approaches that could alter long-term market dynamics. Inventprise is advancing a 25-valent pneumococcal conjugate vaccine with automated manufacturing designed to improve affordability in low- and middle-income countries, targeting a segment where cost and supply reliability are decisive factors. Vaxcyte is developing next-generation candidates including VAX-24 and VAX-31 for adult and infant indications, with Phase 3 trials ongoing. The positive Phase 2 data for VAX-24 in healthy infants compared to Prevnar 20 suggests that newer platforms may compete on both coverage and performance, potentially challenging incumbent products if regulatory approval and commercial execution align. These companies represent a longer-term competitive threat to incumbents, particularly in segments where valency leadership and cost efficiency become the primary differentiators.
Future Trends and Commercial Implications
Several converging trends will shape the market over the next three to five years. First, higher-valent products will increasingly become the standard for both pediatric and adult immunization, as clinical data and guideline updates support broader serotype coverage. The commercial implication is clear: portfolios anchored to lower-valent products will face growing pressure to justify their value proposition against newer alternatives, particularly in markets where national advisory bodies prioritize comprehensive protection and where reimbursement decisions are tied to relative effectiveness. Manufacturers with advanced pipeline candidates will have the opportunity to lead category evolution, while those without near-term pipeline momentum may need to rely on pricing, supply reliability, or niche indications to maintain position.
Second, market access and pricing dynamics will become more complex as immunization programs expand and adult demand grows. Public procurement in emerging markets will continue to emphasize affordability, while developed markets may see segmented pricing based on valency, indication, and real-world evidence packages. The CDC ACIP recommendation for 21-valent vaccine use in adults 50 and older illustrates how adult market segments can expand quickly when guidelines evolve, but also how dependent commercial success is on alignment with reimbursement policies and provider behavior. Companies that invest early in health economics data, payer engagement, and guideline-supporting evidence will be better positioned to capture value as these segments mature.
Third, supply chain localization and manufacturing innovation will gain strategic importance. Cold chain costs remain a significant burden, and temperature excursions continue to threaten dose integrity in developing regions. Over time, formulations or delivery approaches that reduce cold chain dependency, combined with distributed manufacturing and regional fill-finish capacity, could lower total program costs and improve reliability. Organizations that anticipate these needs and invest in practical solutions may gain preference in procurement processes, particularly where ministries of health and multilateral agencies prioritize supply security alongside product attributes. A key uncertainty is the pace at which patent expirations and new entrants translate into meaningful price competition, which will depend on regulatory timelines, manufacturing scale-up success, and the willingness of incumbents to defend share through contracting strategies.
Strategic Recommendations for Decision-Makers
Manufacturers should evaluate portfolio strategy against the direction of valency expansion and the timing of patent-related competitive shifts. For incumbents, the priority is to protect franchise value through evidence generation, indication expansion where feasible, and proactive engagement with immunization programs and payers. For companies with pipeline assets, the window to differentiate is narrowing as higher-valent candidates advance through late-stage development, making execution on clinical trials, regulatory strategy, and manufacturing scale-up decisive factors. Investments in cost-optimized production and cold chain resilience can also create durable advantages, especially in markets where procurement decisions weigh total program cost and supply reliability alongside product performance.
Investors should focus on companies with credible higher-valent pipelines, clear regulatory pathways, and manufacturing strategies that address cost and supply constraints. The market's growth trajectory is favorable, but value capture will depend on execution risk, competitive response to patent expirations, and the ability to translate clinical differentiation into reimbursement and procurement outcomes. Monitoring Phase 3 progress, guideline updates, and capacity expansion announcements will provide early signals about which players are likely to gain share and which may face margin pressure.
Procurement organizations and health system leaders should assess vaccine selection based on total value, including serotype coverage aligned with local epidemiology, dosing schedule practicality, supply reliability, and cold chain implications. As more higher-valent options become available, structured evaluation frameworks that incorporate real-world evidence, total cost of ownership, and supply security will support more resilient immunization programs. Engaging early with manufacturers on capacity planning and supply commitments can reduce vulnerability to shortages and price volatility, particularly in markets where demand is growing and supply diversity is still increasing.
For stakeholders seeking a more detailed view of segment-level dynamics, regional demand patterns, pipeline timelines, and company-level competitive assessments, the full PW Consulting report provides deeper data and customized strategic guidance to support planning and investment decisions.
Pneumococcal Vaccination Market
For detailed analysis of this topic, please visit the official page: Worldwide Multivalent Pneumococcal Conjugate Vaccine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com