

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Worldwide Rodder Machine Market: Why 5.01% CAGR Rewires the $608M 2032 Outlook

Strategic Trends and Commercial Opportunities in the Worldwide Rodder Machine Market
Market Overview and Core Challenges
The global rodder machine market has demonstrated steady expansion over the past half-decade, evolving from a mature, cyclical maintenance sector into a strategically significant equipment segment driven by aging infrastructure and operational efficiency mandates. Recent historical trajectories show consistent revenue growth, with the market surpassing initial estimates as municipalities and industrial operators prioritize mechanical cleaning over chemical or high-pressure alternatives. The compound annual growth rate through the mid-2030s is projected at approximately 5 percent, signaling a transition from flat, maintenance-only spending to more structured capital allocation cycles. This growth trajectory reflects not merely inflationary adjustments but a fundamental shift in how utility operators approach pipeline integrity, wastewater transport reliability, and underground utility access.
Despite the positive momentum, the industry navigates several structural friction points that will define competitive positioning over the next cycle. First, the sector faces a pronounced technological inflection point as municipalities and contractors increasingly evaluate battery-electric and autonomous-assisted rodding platforms. Traditional diesel-driven continuous and sectional rodder systems are being stress-tested by noise ordinances, indoor operating constraints, and evolving emissions standards in dense urban environments. Operators must balance the proven torque and runtime reliability of legacy powertrains against the operational advantages of zero-emission alternatives that demand new servicing protocols, battery lifecycle management, and higher upfront capital outlays.
Second, supply chain volatility in critical input materials directly pressures manufacturing economics and end-user pricing stability. Rodder frames, drive components, and transmission cables rely heavily on steel and aluminum, meaning commodity price swings translate rapidly into cost-of-goods uncertainty. Manufacturers with lean inventory practices or exposure to single-source component suppliers face margin compression during procurement disruptions, while end customers encounter elongated delivery timelines and unpredictable total cost of ownership calculations. This dynamic is forcing both OEMs and procurement departments to reevaluate supplier diversification, long-term service agreements, and equipment financing models.
Third, the market is experiencing a geographic and application-level divergence that complicates consolidated go-to-market strategies. Infrastructure renewal programs in developed regions emphasize compliance-driven preventive maintenance and inspection-linked cleaning cycles, whereas rapidly urbanizing regions focus on capacity expansion and new utility network deployment. Simultaneously, end-use demand patterns are shifting: routine municipal sewer cleaning remains the largest consumption driver, but specialized industrial pipe maintenance and telecommunications ducting workflows are adopting lighter, precision-oriented rodding configurations. Navigating this divergence requires equipment providers and service operators to avoid one-size-fits-all positioning and instead align product portfolios, distribution partnerships, and service capabilities with distinct operational realities.
Key Demand Drivers Shaping Market Direction
Technological Innovation and Platform Evolution
The most consequential driver reshaping competitive expectations is the ongoing transformation of rodder machine architecture. Continuous rodders continue to dominate heavy-duty mainline applications because their uninterrupted cable path delivers consistent torque penetration over extended runs, making them indispensable for bulk debris removal, root cutting, and silt disruption in large-diameter lines. At the same time, sectional rodder platforms retain a strong footprint in scenarios requiring maneuverability, tool interchangeability, and targeted cleaning in constrained access points or shorter pipe segments. The real strategic shift lies in how power delivery, control systems, and cable management are being redesigned. Manufacturers are integrating torque feedback logic, improved drum tensioning, and ergonomic operator controls to reduce fatigue and improve cleaning consistency across varying soil and obstruction conditions. These refinements are not cosmetic; they directly affect cycle time, repeat-clearing incidents, and equipment utilization rates, which are critical metrics for municipal departments managing large route schedules and contractors billing by job efficiency.
Regulatory Pressure and Compliance-Driven Maintenance
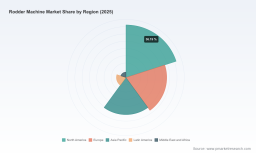
Environmental and public health regulations are functioning as a powerful demand anchor, particularly in North America and Europe. Strict wastewater inspection mandates and sanitary sewer overflow prevention requirements are compelling municipalities to maintain more frequent cleaning and inspection cycles. In practice, this means rodding equipment is no longer treated as a discretionary repair tool but as part of a compliance-linked asset management strategy. On the European side, directives favoring non-invasive cleaning methods are accelerating adoption of precision rodder configurations that minimize pipe stress and reduce the need for excavation. The regulatory environment effectively sustains baseline demand while pushing operators toward equipment that can document performance, withstand inspection schedules, and operate within tighter environmental constraints. This creates a durable purchasing rationale even during budget compression cycles, because deferred cleaning can trigger regulatory penalties and higher remediation costs downstream.
Demand-Side Behavior and Operational Priorities
End-user behavior is evolving as municipalities, industrial facilities, and telecommunications contractors recalibrate how they balance labor, downtime, and equipment flexibility. Municipal water and sewer departments are increasingly seeking equipment that can handle mixed debris profiles—stones, grit, sludge, and root intrusion—without switching between multiple specialized machines. This operational reality favors flexible drive configurations, durable cable systems, and tool kits that support rapid attachment changes. Industrial pipe maintenance teams are prioritizing machines capable of reaching longer runs and larger diameters with controlled feed force to avoid damaging sensitive process piping. Meanwhile, ducting and telecom contractors are leaning toward lightweight rodding and pulling systems that support tracer functions and conduit access without disrupting active service corridors. Across these segments, the common theme is predictable performance under variable operating conditions, which elevates the importance of machine reliability, service availability, and operator training support over pure purchase price.
Supply Chain Realities and Cost Structure Pressures
Manufacturing economics are being reshaped by material intensity and component complexity. Steel and aluminum remain foundational to rodder frames, reel structures, and cable assemblies, so raw material price fluctuations directly influence production costing and pricing stability. Beyond commodities, the broader supply chain context is encouraging manufacturers to reconsider sourcing strategies, inventory buffers, and aftermarket parts availability. Service networks are becoming a competitive differentiator because downtime during a peak cleaning season or an emergency blockage event carries disproportionate operational and reputational costs. This environment rewards manufacturers that can provide responsive parts logistics, clear maintenance intervals, and deployable field support. It also encourages fleet operators to evaluate total cost of ownership more carefully, weighing fuel or battery management costs, expected cable life, and servicing lead times rather than focusing solely on sticker price.
Competitive Landscape and Leading Strategies
The competitive field in the rodder machine market is shaped by a mix of established equipment manufacturers, specialized regional players, and emerging suppliers targeting adjacent cleaning and conduit workflows. Market concentration indicates that a handful of leading firms capture a meaningful share of revenue, yet the presence of multiple capable manufacturers suggests room for differentiation through product architecture, powertrain strategy, and service execution rather than pure scale. Leaders are not competing solely on machine size or maximum run length; they are competing on how well their platforms fit the operational environment of the buyer.
Strategic Positioning and Differentiation
Leading manufacturers are defining their advantage through targeted capability sets and clear end-user alignment. RIDGID, for example, has built recognition around heavy-duty sectional rodder systems designed for straight main line work in larger-diameter sewer and drain lines, emphasizing torque delivery, tool kit breadth, and suitability for municipal, institutional, and industrial applications. General Pipe Cleaners has reinforced its position through sectional drain cleaning machines engineered for tough clogs in long runs and larger pipes, with two-way operation supporting professional and municipal use cases. Electric Eel Manufacturing Company continues to serve professional, rental, and municipal markets with drum and continuous cable cleaning platforms that emphasize long-standing product familiarity and broad market accessibility. Sewer Equipment Co. of America positions its rodder series within a broader sewer cleaning lineup, highlighting mechanical rodding approaches that align with water-conserving operational priorities. Spartan Tool rounds out the field by providing rodding machines aimed at professional contractors and municipal users, competing on practical usability and service reach.
Diverging Product and Powertrain Strategies
TSE International illustrates how product strategy is responding to evolving operational constraints. The company continues to promote its diesel OK Champion S660 alongside the battery-electric S660E, positioning the electric variant as a quiet, emission-free option for sewer and conduit maintenance. This dual-track approach reflects a practical market reality: many fleets still require diesel horsepower for demanding heavy-duty work, while certain municipalities and enclosed-site operators increasingly value emission-free, low-noise alternatives that can also serve as complements or substitutes for vacuum truck deployments in specific workflows. The availability of a self-contained battery power source is not merely a product feature; it represents a strategic bet on the growing demand for operational flexibility in areas where noise, emissions, and site access restrictions influence equipment selection. Similarly, Hebei Sinta FRP Co., Ltd. demonstrates how international suppliers are expanding the competitive boundary by focusing on fiberglass duct rodders, cobra cable pullers, and traceable duct rodding accessories for cable laying and pipeline cleaning applications, broadening the competitive conversation beyond traditional sewer cleaning into utility and telecom ducting workflows.
Worldwide Shaper Machine Market
Market Evolution and Structural Shifts
The competitive landscape appears to be moving along two parallel tracks. On one track, established manufacturers are deepening their positions through product refinements, service coverage, and targeted municipal procurement engagement. On the other, new entrants and adjacent-market suppliers are introducing specialized configurations that blur the line between sewer rodding, conduit cleaning, and cable pulling. This combination of deepening incumbency and specialized encroachment is likely to increase segmentation intensity. Expect more emphasis on bundling equipment with accessory ecosystems, training, and service agreements, as well as greater competition around procurement responsiveness, as evidenced by recent municipal bidding activity for integrated truck-mounted rodder systems. Competitive advantage will increasingly belong to organizations that can align hardware, powertrain choice, parts logistics, and bid-ready specification support with the specific operational requirements of each buyer segment.
Forward Trends and Commercial Implications
Over the next three to five years, the rodder machine market is likely to be defined by a small number of intersecting trends that carry clear commercial implications. First, electrification and low-emission platform adoption will broaden beyond niche applications. Battery-electric rodders will continue to gain traction in urban environments, enclosed facilities, and jurisdictions with restrictive noise or emission policies. The commercial opportunity lies not simply in selling electric machines, but in developing battery management services, charging logistics guidance, and application-specific sizing expertise that help buyers avoid underpowered purchases or unrealistic runtime expectations. Manufacturers that bridge the gap between electric capability and real-world job conditions will capture a premium position in an increasingly segmented market.
Second, infrastructure spending and urbanization-driven utility expansion will sustain demand while shifting the purchase rationale toward lifecycle performance. As municipal wastewater networks, storm drain systems, and underground utility corridors receive renewed attention, rodding equipment will be evaluated through the lens of route efficiency, repeatability, and reduced repeat-clearing incidents. This trend favors suppliers and service providers that can demonstrate how machine design, cable durability, and operator ergonomics contribute to measurable operational outcomes. The upside for dealers and manufacturers is stronger aftermarket relevance: spare parts, cable replacement programs, and preventive maintenance contracts will gain importance as fleets look to stabilize uptime across seasonal demand peaks.
Third, procurement processes will become more specification-driven and integrated. Recent municipal bid activity for truck-mounted jet rodder platforms indicates that buyers increasingly view rodding capability as part of a broader vehicle and service configuration rather than an isolated tool purchase. This shift creates opportunities for equipment providers that can support bid documentation, performance specifications, and configuration flexibility tailored to specific debris profiles and line sizes. However, the same trend introduces uncertainty: budget timing, procurement lead times, and evolving municipal priority lists can delay purchase cycles, and commodity-driven cost pressure may complicate pricing commitments. Stakeholders that build flexibility into their supply planning and maintain clear communication around specification trade-offs will be better positioned to convert demand into closed deals.
Strategic Recommendations for Decision-Makers
For equipment manufacturers, the priority is to align product roadmaps with the dual reality of diesel-dependent heavy-duty demand and accelerating interest in low-emission, low-noise operation. Rather than treating electrification as a separate product line, integrate powertrain options into a coherent platform strategy that clarifies application fit, runtime constraints, and service requirements. Invest in parts availability, field support coverage, and configuration guidance that help procurement teams specify the right machine for each use case, because specification confidence is becoming a decisive factor in municipal and contractor purchasing.
PW Consulting
For investors and strategic buyers, the most valuable signals are not headline growth rates alone but the structural durability of demand drivers and the competitive differentiation potential of service ecosystems. Equipment segments tied to compliance-driven maintenance, utility expansion, and specialized ducting workflows offer defensible revenue logic, especially where aftermarket parts, cable replacement cycles, and service responsiveness create recurring value. Evaluate exposure to raw material volatility and assess whether target companies have pricing strategies, supplier diversification, or value-added service models that can protect margins through procurement cycles.
For municipal operators, contractors, and procurement teams, the immediate focus should be on total cost of ownership alignment rather than unit price comparison. Match machine type, cable configuration, and power source to the actual debris mix, pipe diameter range, and site access constraints of the job portfolio. Where possible, structure purchasing decisions to include service response expectations, parts lead times, and operator training support, since these operational factors often determine whether equipment delivers its intended efficiency over multiple seasons. Anticipate tighter specification requirements and longer procurement cycles by engaging early with equipment providers who can translate operational needs into bid-ready configurations.
Worldwide Die Sorters Market
Detailed segmentation data, procurement mapping, and company-specific capability assessment can sharpen these decisions further, particularly when evaluating regional demand intensity, product fit by application, and competitive positioning across the largest revenue pools. More granular analysis is available in the PW Consulting report on the worldwide rodder machine market for teams that need to translate these strategic trends into procurement timing, product portfolio decisions, or investment prioritization.
For detailed analysis of this topic, please visit the official page: Worldwide Rodder Machine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com