

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Worldwide Aluminium Tert Butoxide Market: 5.48% CAGR and Regional Shifts

Navigating the Aluminium Tert-Butoxide Market: Strategic Trends and Commercial Opportunities Through 2032
The global market for aluminium tert-butoxide has entered a period of structured expansion, driven by its indispensable role as a catalyst and reagent in high-performance chemical synthesis. Valued at approximately 112.55 million USD in the base year, the market has demonstrated steady growth from its 2020 baseline of 86.25 million, reflecting consistent demand pull across industrial and scientific applications. Projections indicate a compound annual growth rate of 5.48 percent, positioning the sector to reach 163.51 million USD by 2032. This trajectory is not merely a function of incremental volume increases; it represents a structural shift toward specialized organometallic intermediates that enable precision manufacturing in emerging technology sectors. The convergence of advanced materials development, regulatory tightening around legacy chemical processes, and the globalization of specialty chemical supply chains has created a favorable environment for sustained commercial activity.
Despite the favorable growth outlook, industry participants are navigating a complex landscape defined by cost volatility, concentration dynamics, and evolving application requirements. One of the most pressing challenges lies in the sensitivity of production economics to raw material pricing. The cost structure for aluminium alkoxides is inherently tied to upstream inputs, and recent market movements have introduced significant uncertainty into margin forecasting. Simultaneously, the market exhibits a moderate-to-high degree of concentration, with the top three participants capturing over half of total industry revenue and the top five controlling nearly seventy percent. Such concentration creates both stability for established players and barriers for new entrants, while also raising questions about supply resilience and pricing power in an increasingly fragmented demand environment. A second critical juncture involves the divergence in purity requirements across end-use sectors. High-purity grades now dominate commercial activity, reflecting the needs of advanced electronics and precision catalysis, while standard grades maintain relevance in broader industrial applications. This bifurcation requires manufacturers to maintain distinct production protocols, quality assurance frameworks, and inventory strategies, complicating operational scaling.
The third challenge centers on geographic demand distribution and the corresponding need for localized supply capabilities. While demand is dispersed across multiple regions, the Asia Pacific corridor continues to account for the largest share of commercial activity, reflecting both manufacturing density and accelerating industrial modernization. Europe and North America maintain substantial footholds, supported by established laboratory networks and specialized chemical synthesis ecosystems. Latin America and the Middle East and Africa represent smaller but growing nodes of activity, often tied to regional industrial initiatives and imported specialty chemical demand. This geographic footprint necessitates a nuanced approach to distribution, regulatory compliance, and customer engagement. Companies must balance centralized production efficiency with regional responsiveness, particularly as procurement teams increasingly prioritize supply reliability over pure cost minimization. The interplay between demand concentration, purity segmentation, and regional cost structures defines the current market reality and will shape competitive positioning in the years ahead.
Key Drivers: What Is Really Moving the Market
Technological innovation continues to serve as the primary engine of commercial expansion, particularly in the realm of catalytic precision and materials science. Aluminium tert-butoxide functions as a critical reagent in esterification, transesterification, and the synthesis of advanced polymers and fine chemicals. Recent advancements in process chemistry have amplified its utility, enabling more efficient reaction pathways and reduced byproduct formation. In the semiconductor and electronics domain, the compound's role in precursor chemistry and surface treatment processes has gained renewed attention as device architectures become increasingly complex. Manufacturers that invest in controlled-atmosphere handling, particle-size consistency, and trace-metal reduction are capturing premium positioning, particularly among customers operating at the intersection of research and pilot-scale production. The shift toward continuous flow chemistry and automated synthesis platforms is also reshaping demand patterns, favoring suppliers capable of delivering consistent batch-to-batch performance and technical documentation that aligns with modern quality management expectations.
Regulatory and policy environments are simultaneously reweighting the competitive landscape, particularly around chemical safety, environmental compliance, and procurement transparency. Stricter handling requirements for organometallic compounds have elevated the importance of supplier documentation, safety data alignment, and packaging integrity. In several major markets, procurement frameworks now prioritize vendors that can demonstrate robust traceability, controlled storage specifications, and compliance with evolving occupational exposure standards. These requirements do not merely add administrative burden; they function as de facto barriers to entry that reward established players with mature quality systems and disciplined distribution networks. At the same time, sustainability mandates are influencing formulation choices across downstream industries, indirectly supporting demand for reagents that enable cleaner reaction pathways and reduced waste streams. The policy environment is therefore not simply a constraint but a catalyst for differentiation, favoring companies that integrate compliance into their core operating model rather than treating it as an afterthought.
PW Consulting
Supply-side economics present a further layer of strategic complexity. The cost structure for aluminium tert-butoxide is highly responsive to fluctuations in aluminium-based precursors and alcohol feedstocks. Recent market data underscores this sensitivity: aluminium metal prices reached 3,484.20 USD per tonne in late April 2026, representing a year-over-year increase of 44.45 percent and directly pressuring the production economics of aluminium alkoxides. In parallel, isobutanol, a key alcohol feedstock for tert-butoxide synthesis, traded in the range of 1,640 to 1,750 USD per tonne in Northwest European FOB terms during the same period. Aluminium oxide prices displayed notable regional dispersion, ranging from 0.42 USD per kilogram in Northeast Asia to 0.57 USD per kilogram in India, reflecting divergent local cost environments for aluminium-based precursors. These dynamics create a volatile input environment that rewards manufacturers with flexible sourcing strategies, regional production footprints, and the ability to pass through cost adjustments without sacrificing market share. Companies that rely on single-source procurement or rigid pricing models face heightened margin compression risk, particularly during periods of rapid commodity repricing.
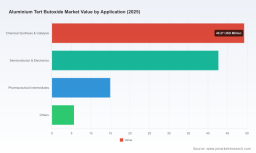
Demand-side behavior is evolving in tandem with these supply and regulatory forces. Procurement teams across chemical synthesis, electronics, and pharmaceutical intermediary sectors are increasingly prioritizing supply reliability, technical support, and format flexibility over lowest-unit-cost acquisition. The compound is consumed across a broad application spectrum, with chemical synthesis and catalysis representing the largest commercial share, followed closely by semiconductor and electronics applications. Pharmaceutical intermediates and specialized industrial uses account for the remainder, each demanding different packaging scales, purity assurances, and delivery cadences. This diversification means that suppliers must operate multi-tiered service models, accommodating both catalog-grade research purchases and bulk industrial deliveries. Customers are also showing greater willingness to engage with suppliers that offer clear documentation, predictable lead times, and responsive technical guidance, particularly when qualifying materials for new production lines or scaling laboratory processes into pilot operations.
Competitive Landscape and the Strategies Defining Leadership
The competitive environment for aluminium tert-butoxide is characterized by a mix of global specialty chemical suppliers, regional distributors, and niche organometallic specialists. American Elements, headquartered in Los Angeles, California, has positioned itself around a broad organometallic portfolio, offering aluminium tert-butoxide in multiple purity grades for non-aqueous applications that span solar energy and water treatment. Its strategic emphasis on application breadth and product availability allows it to serve customers who require consistent supply across varied technical contexts. Ereztech, operating in the United States, focuses on manufacturing and selling aluminium(III) tert-butoxide in both small and bulk volumes, with packaging options that include glass ampules, bottles, and metal bubblers. This flexibility in pack size and delivery format addresses a practical pain point for laboratory and pilot-scale users who need controlled quantities without compromising handling safety.
TCI Chemicals, based in Japan with U.S. operations in Philadelphia, offers aluminium tert-butoxide with purity exceeding 98 percent for laboratory and research use, available in catalog quantities with regional stocking. Its positioning reflects a strong emphasis on research-grade reliability and logistical proximity to scientific customers. Sigma-Aldrich, now part of Merck, supplies technical-grade aluminium-tri-tert-butoxide for chemical synthesis and reagent applications, leveraging a globally recognized brand and extensive distribution infrastructure. Thermo Scientific Chemicals, formerly Alfa Aesar, provides aluminium tert-butoxide at 97 percent purity in various pack sizes, catering to both laboratory and industrial reagent needs with an emphasis on standardized quality and broad catalog availability. ProChem, Inc., operating in the United States, manufactures and supplies aluminium t-butoxide as part of its broader specialty chemical product line, appealing to customers who value integrated sourcing and established industrial relationships.
In the Asia Pacific corridor, Sinochem Nanjing Corporation functions as an industrial supplier and factory manufacturer, offering aluminium tert-butoxide in wholesale quantities and reflecting the region's emphasis on scale and cost-competitive supply. Alfa Chemistry, based in the United States, provides aluminium tert-butoxide for experimental and research use with supporting documentation, targeting customers who prioritize traceability and technical clarity. These companies collectively illustrate a market where differentiation is achieved through a combination of purity assurance, packaging flexibility, regional availability, and application-specific support rather than through price competition alone.
The strategic positioning of leading players reveals several recurring advantages. First, companies that maintain distinct quality tiers and clear documentation protocols are better equipped to serve the divergent needs of research, pilot, and industrial customers. Second, suppliers with flexible packaging and delivery options reduce friction for buyers who require precise quantities or specialized handling formats. Third, organizations that combine manufacturing capability with reliable distribution networks are better positioned to manage supply continuity during periods of raw material volatility. The market concentration pattern, with the top three firms holding over half of revenue and the top five controlling nearly seventy percent, suggests that scale, brand trust, and compliance maturity remain powerful moats. At the same time, the presence of multiple regional and specialty suppliers indicates room for targeted differentiation, particularly for companies that can serve niche purity requirements or offer responsive local logistics.
Looking ahead, the competitive landscape is likely to evolve through selective consolidation, regional supply network expansion, and increased emphasis on technical service. Larger players may pursue acquisitions or partnerships to broaden purity-grade coverage, strengthen geographic reach, or integrate downstream application support. Mid-tier and regional suppliers may differentiate by offering faster turnaround, customized documentation, or specialized handling for sensitive applications. New entrants will face the dual challenge of meeting stringent quality expectations while competing against established distribution channels and customer relationships. The net effect is a market that rewards operational discipline, technical credibility, and customer-centric flexibility over undifferentiated volume competition.
Forward View: Three Trends Shaping the Next Three to Five Years
The first major trend is the continued elevation of purity and consistency as commercial imperatives. As semiconductor, electronics, and advanced catalysis applications mature, downstream customers will increasingly view material variability as a process risk rather than a tolerable compromise. Suppliers that invest in tighter control over trace impurities, moisture sensitivity, and particle uniformity will capture disproportionate value, particularly in applications where reagent performance directly influences yield, device reliability, or regulatory acceptance. This trend will likely accelerate the separation between premium-grade supply chains and standard-grade commodity channels, with margin differentiation widening accordingly.
The second trend is the growing importance of supply chain resilience and regional responsiveness. Given the sensitivity of input costs and the geographic dispersion of demand, procurement teams will continue to favor suppliers that can demonstrate multi-source procurement, regional inventory positioning, and transparent lead-time management. Companies that build flexible sourcing arrangements and maintain buffer strategies for critical feedstocks will be better positioned to navigate commodity repricing events without disrupting customer commitments. This resilience will become a competitive differentiator in its own right, particularly as customers seek to reduce exposure to single-point supply failures.
The third trend involves the expanding intersection of technical service and commercial growth. As applications become more specialized, customers will expect suppliers to provide not only material but also applicable documentation, handling guidance, and qualification support. Suppliers that can align their commercial offerings with the practical needs of research, pilot scaling, and industrial production will build deeper customer relationships and reduce churn. At the same time, potential risks remain. Raw material volatility, regulatory changes around organometallic handling, and shifts in downstream procurement budgets could introduce periodic demand softness or margin pressure. Companies that treat these factors as manageable variables rather than external shocks will be better prepared to sustain growth through cyclical disruptions.
Worldwide Aluminum Alkyls Market
Actionable Guidance for Decision-Makers
For manufacturers and suppliers, the priority is to align production and quality systems with the diverging requirements of high-purity and standard-grade segments while maintaining cost flexibility in the face of input volatility. Diversifying feedstock sourcing, regionalizing inventory where feasible, and investing in documentation and handling protocols will strengthen both margin resilience and customer trust. Differentiation should focus on reliability, technical support, and format flexibility rather than on price alone, particularly as downstream customers increasingly value supply continuity and qualification speed.
For investors, the market presents opportunities in companies with disciplined quality systems, flexible procurement models, and clear application-focused positioning. Attention should be directed toward suppliers that can demonstrate consistent performance across purity tiers, manage raw material exposure effectively, and serve high-growth application corridors without overextending into undifferentiated commodity competition. Due diligence should weigh not only current revenue profiles but also the ability to sustain supply reliability and technical credibility through periods of input cost fluctuation.
For procurement and supply chain leaders, the strategic focus should be on qualifying multiple capable suppliers, establishing clear purity and packaging requirements, and building contingency plans for feedstock-driven price movements. Engaging suppliers that offer transparent documentation, predictable lead times, and responsive technical support will reduce qualification risk and improve operational continuity. Evaluating total cost of ownership, including handling, storage, and qualification overhead, will yield better outcomes than focusing solely on unit price. Detailed segment-level data, regional cost structures, and customized procurement scenarios can further sharpen these decisions, and the full research report provides the granular breakdowns and scenario analysis needed to translate these strategic directions into specific operational plans.
Worldwide Aluminum Dimethyl Isopropoxide Market
For detailed analysis of this topic, please visit the official page: Worldwide Aluminium Tert Butoxide Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com