

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Worldwide Bathroom Product Market 2026: 5.85% CAGR Growth Drivers & Key Shifts Until 2032

The Changing Face of the Global Bathroom Product Market: Strategic Trends and Commercial Opportunities
Market Landscape: Size, Growth, and Structural Headwinds
The worldwide bathroom product market has transitioned from a mature, slow-growth sector into a structurally expanding market defined by steady capital deployment, product differentiation, and regional recalibration. Over the past half-decade, the industry moved from just under 100 billion USD in 2020 to approximately 128 billion USD in 2025, reflecting consistent annual expansion despite periodic supply disruptions and shifting demand patterns. The forward trajectory points to continued growth, with the market projected to reach roughly 137 billion USD by 2026 and approach 191 billion USD by 2032. This implies a compound annual growth rate of approximately 5.85 percent across the forecast horizon, a pace that signals more than cyclical recovery and instead indicates underlying shifts in how bathroom spaces are designed, purchased, and experienced. Growth is being distributed across the full product spectrum, from foundational ceramic sanitaryware to faucets, showers, vanities, and bathtubs, with the mix continually weighted by regional consumption habits and construction activity.
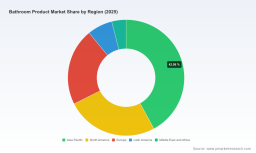
The regional footprint of the market reflects long-standing demand centers alongside faster-moving emerging corridors. Asia Pacific currently accounts for the largest share of global consumption, supported by strong residential construction, urbanization, and increasing per-capita spending on bathroom upgrades. North America and Europe together represent a substantial portion of the market, anchored by replacement demand, renovation cycles, and a consumer base that increasingly values design-led and water-efficient solutions. Latin America and the Middle East and Africa, while smaller in absolute scale, contribute meaningful pockets of growth tied to infrastructure development and expanding middle-class households. Distribution channels remain anchored in offline retail and wholesale networks, reflecting the tactile, specification-driven nature of many bathroom purchases, though digital channels continue to gain traction for catalog browsing, comparison, and direct-to-consumer experimentation. The market remains relatively fragmented, with no single company commanding dominant share, and the top few players collectively representing a modest concentration. This open structure creates room for new entrants, brand differentiation, and targeted geographic expansion.
Despite the favorable growth trajectory, the market faces several structural challenges that will shape competitive outcomes over the next several years. First, input cost volatility and material availability continue to pressure margins across ceramic production, metal fabrication, and finishing processes. Fluctuations in raw material pricing and energy costs have forced manufacturers to balance price increases with consumer sensitivity, particularly in mid-tier segments where substitution and deferred purchases are more likely. Second, regulatory pressures around water efficiency, safety, and sustainability are reshaping product requirements and compliance timelines. Buyers and specifiers increasingly expect fixtures that reduce consumption without compromising performance, while safety standards in certain categories, including infant and baby bath products, have drawn heightened scrutiny and recall activity. Third, trade policy uncertainty adds complexity to cross-border sourcing strategies. Announcements regarding potential tariffs on imported bathroom vanities and related products illustrate how quickly cost structures and supply routes can be disrupted, prompting companies to reconsider manufacturing footprints, inventory buffers, and regional sourcing mixes. These challenges do not threaten the overall growth narrative, but they do raise the bar for operational agility, product planning, and market entry timing.
Core Drivers Reshaping Demand and Competitive Advantage
Technology innovation is moving from a differentiator to a baseline expectation in bathroom products. Smart fixtures, sensor-based faucets, thermostatic shower controls, and integrated hygiene features are increasingly appearing across premium and mid-premium segments, driven by consumer interest in convenience, water management, and modern aesthetics. Recent trade show activity highlights how quickly product roadmaps are evolving. At the International Bathroom Exhibition in Milan in 2026, multiple manufacturers showcased sustainable materials, connected functions, and refined design language as central themes. The same pattern appeared at the Kitchen & Bath Industry Show in Orlando in 2026, where launches emphasized smart fixtures and sustainable solutions. These events reflect a broader shift in product strategy: companies are no longer treating smart features as isolated gadgets, but as part of integrated bathroom experiences that combine water efficiency, user interface design, and durability. TOTO’s unveiling of next-generation smart, sustainable, and luxury innovations, including matte color vessel lavatories at KBIS in 2025, illustrates how leading brands are pairing surface aesthetics with functional sophistication to capture attention in crowded showrooms and specification processes.
Policy and regulatory dynamics are equally influential in shaping product selection and market access. Water-saving requirements, safety mandates, and sustainability certifications are becoming more visible in procurement criteria and consumer preferences. The broader industry context is also seeing sustainability move into event and supply-chain standards themselves, as reflected by CERSAIE’s ISO 20121:2024 certification for sustainable event management in the ceramic tile and bathroom furnishings sector. Such signals matter because they indicate that sustainability is being institutionalized across the value chain, not simply used as a marketing message. For manufacturers and distributors, this means that compliance readiness, documentation, and transparent sustainability claims are becoming part of competitive positioning. Regulatory attention in specific categories can also have immediate commercial consequences. Recent safety warnings and recalls involving unstable infant and baby bath seats point to the importance of design validation and post-market monitoring, especially for products used by vulnerable populations. Companies that embed rigorous testing and usability review into product development are better positioned to avoid disruptions and protect brand trust.
Consumer and specifier behavior is shifting in ways that favor design coherence, performance reliability, and total cost perception. In renovation and new-construction settings, bathroom decisions are increasingly made with a broader view of water usage, maintenance, and long-term durability rather than initial sticker price alone. Ceramic continues to hold strong appeal in sanitaryware due to its durability and chemical resistance, a reputation that supports its continued dominance in many markets. At the same time, consumers are responding to broader style shifts, including matte finishes, integrated vanities, and coordinated fixture families that make smaller or aging bathrooms feel more contemporary. The purchasing journey is also evolving. Offline retail and wholesale channels still handle the majority of transactions because bathroom products often require physical evaluation, measurement, and installation coordination. Yet online channels are growing as a discovery and comparison layer, and in some cases as a transaction channel for accessories, replacement parts, and simpler fixtures. This dual-channel reality means that brands must maintain consistent product information, visual presentation, and availability signals across both environments to avoid losing prospects during the specification journey.
Supply chain and cost structure changes are becoming a strategic variable rather than a background condition. Tariffs and trade policy risk can quickly alter the economics of imported vanities and related bathroom products, and operators in North America and other import-dependent markets have had to plan for potential cost shocks. In parallel, producer price movements in key manufacturing regions have affected the economics of ceramic sanitary fixtures. Recent eurozone data showed producer prices for ceramic sanitary fixtures in France at elevated index levels in late 2025, underscoring how regional cost conditions can differ materially even within a globalized industry. These dynamics are encouraging companies to diversify sourcing, consider regional production or assembly where feasible, and improve demand forecasting to reduce inventory risk. For suppliers that can manage cost, quality, and lead times simultaneously, the current environment offers an opportunity to win share from competitors that are slower to adapt their sourcing or pricing models.
Competitive Landscape: Positioning, Differentiation, and Structural Shifts
The competitive field is broad and geographically diverse, with strong representation from established multinational brands and increasingly capable regional players. Kohler continues to compete on the strength of a comprehensive product range spanning faucets, showers, sinks, toilets, bidets, and smart fixtures, with emphasis on design, water efficiency, and the residential and commercial segments. TOTO has built a reputation around advanced sanitaryware, smart toilet systems, and water-saving technology that links hygiene, sustainability, and luxury performance. LIXIL operates through a portfolio of well-known brands and offers complete bathroom solutions across faucets, showers, sanitaryware, and water-efficient systems for global use. Roca combines ceramic sanitaryware, faucets, showers, and bathroom furniture with a focus on design, sustainability, and quality. Geberit is distinct in its emphasis on concealed plumbing systems and innovative bathroom technologies for both commercial and residential installations. European premium players such as Villeroy & Boch and Duravit compete through luxury design, high-quality materials, and modern aesthetics, while Hansgrohe focuses on premium shower systems and faucets with water-saving technology and design-led positioning. In the North American market, American Standard and Moen maintain strong recognition for reliable, accessible fixtures, and Masco plays a significant role through brands that serve residential plumbing needs. In emerging markets, RAK Ceramics, Jaquar, CERA, and Hindware are expanding the middle-to-premium pipeline, using local market knowledge and scale to compete across sanitaryware, faucets, and related products.
The differentiating success factors in this landscape are becoming clearer. First, product breadth and system thinking matter. Companies that can offer coordinated faucets, showers, sanitaryware, and vanities reduce friction for specifiers and renovators who want a unified look and predictable installation outcome. Second, technology integration and water efficiency are increasingly linked to brand relevance. Smart functions, flush performance, sensor-based hygiene, and reduced water consumption are no longer niche features; they are central to winning in premium and semi-premium segments where buyers expect a combination of comfort and sustainability. Third, regional credibility remains powerful. Multinational brands benefit from global scale and design language, but regional players often win by tailoring products to local tastes, price points, and installation practices. This is especially visible in markets where bathroom styles, water conditions, and consumer price sensitivity differ substantially from the global average.
Bathroom Vanities Market
The market structure is evolving through a mix of consolidation pressure and segmentation depth. Concentration remains moderate, which leaves space for brand specialization and regional expansion, but the competitive center of gravity is shifting toward companies that can manage design, technology, and supply chain performance at the same time. Recent industry events suggest that innovation is being presented in more integrated ways, with sustainability, technology, and design presented as a combined narrative rather than separate product claims. This points to a future in which the winners are less defined by a single hero product and more by the ability to deliver consistent experiences across categories. At the same time, new entrants and brand extensions continue to test niche positioning in wellness, designer collaborations, and smart home connectivity, keeping the market dynamic. The most important structural question for incumbents is whether they can scale innovation without eroding the margin and quality control that support premium positioning.
Forward Outlook: Three Trends Shaping the 2026–2030 Horizon
One of the clearest forward trends is the accelerating normalization of smart and water-conscious bathroom products as mainstream expectations rather than premium add-ons. Over the next few years, sensor-driven fixtures, efficient flush technologies, and more intuitive control interfaces are likely to move further down the price pyramid as manufacturing processes mature and component costs stabilize. This will create opportunity for brands that can deliver reliability and simple user experiences rather than feature-heavy products that complicate installation or maintenance. The commercial opportunity lies in specification-friendly systems that help contractors and renovators meet efficiency goals without sacrificing design quality, especially in multifamily housing, hospitality, and renovation programs where long-term operating costs matter.
A second trend is the growing importance of regional supply resilience and pricing agility. Trade policy uncertainty, raw material price variation, and shifting production costs will continue to reward companies that can adjust sourcing strategies and portfolio pricing with speed. This does not necessarily mean abandoning global sourcing, but it does favor organizations that maintain flexible manufacturing networks, clear visibility into cost drivers, and disciplined portfolio management. Businesses that can hold quality steady while responding to tariff exposure and input price movement will gain share in markets where competitors are slower to recalibrate. There is also an opportunity in mid-market segments, where consumers may delay upgrades if price increases outpace perceived value, making value engineering and design coherence particularly important.
A third trend is the continued blending of hygiene, wellness, and design in bathroom product offers. Post-pandemic attention to cleanliness did not disappear; it evolved into broader expectations for easy-to-clean surfaces, controlled water contact, and finishes that support both aesthetics and maintenance. Combined with consumer interest in spas, relaxation, and contemporary interiors, bathroom products are increasingly positioned as part of a wellness experience rather than purely utilitarian fixtures. The risk here is that trend-led launches can outpace practical performance, especially if features add complexity or reduce durability. Companies that balance style with robust engineering and clear installation guidance will be better positioned to convert interest into repeat business and favorable specification outcomes. A related uncertainty is the pace of regulatory change and trade policy adjustments, which can alter regional economics quickly and require companies to revise launch timing, channel strategy, and sourcing plans with limited lead time.
Actionable Priorities for Decision-Makers
For manufacturers, the priority is to strengthen portfolio coherence and reduce friction across the specification-to-installation journey. That means aligning faucets, sanitaryware, showers, and vanities in ways that make it easier for buyers to choose a complete solution, while ensuring that smart and water-saving features add genuine value rather than complexity. Equally important is building flexibility into sourcing and pricing so that potential tariff exposure and raw material movement can be managed without sudden erosion of margin or inconsistent product availability. Companies that can demonstrate reliable lead times, stable quality, and clear sustainability and safety documentation will have an advantage when specifiers compare options.
PW Consulting
For investors, the opportunity lies in identifying operators with durable brand relevance, disciplined cost structures, and the ability to scale innovation without compromising quality. The market’s moderate concentration and continued growth create room for selective value creation, especially where companies have strong regional positioning or differentiated technology in water efficiency, hygiene, or designer appeal. Attention should be paid to supply chain resilience and product mix, since businesses overly reliant on a narrow set of cost-sensitive inputs or import-heavy routes may face more volatility than peers with diversified production and channel strategies.
For procurement and retail leaders, the strategic task is to keep product information, availability, and visual presentation consistent across offline and online touchpoints while managing exposure to policy and cost shocks. This includes developing clear category plans that balance replacement demand with upgrade cycles, maintaining relationship strength with installation partners, and using flexible sourcing options to reduce vulnerability to tariff-related price increases. For deeper segmentation detail, regional sizing, competitive share estimates, and channel-specific scenarios, the full research report provides the supporting data and structured frameworks needed for more precise portfolio and sourcing decisions.
Toilet Seat Market
For detailed analysis of this topic, please visit the official page: Worldwide Bathroom Product Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com