

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Phlegm Suction Tube Market Set to Hit $926.88M by 2032: Shifts Beyond the 5.2% CAGR

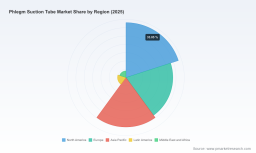
Strategic Trends and Commercial Opportunities in the Worldwide Phlegm Suction Tube Market
Market Snapshot and Core Challenges
The global phlegm suction tube market is navigating a phase of steady expansion, characterized by a compound annual growth rate that reflects the underlying health of respiratory care infrastructure worldwide. Revenue projections over the coming decade indicate a market trajectory moving toward higher valuation thresholds, driven by consistent demand across established healthcare economies. This growth is not uniform but rather paced by regional healthcare spending patterns, procurement cycles, and the gradual modernization of acute care facilities in developing regions.
Worldwide Expectoration Machine Market
A defining feature of the current landscape is the concentration of market value among a relatively small group of major players, reflecting consolidated distribution channels and entrenched supplier relationships in key hospital networks. This concentration shapes pricing dynamics and creates barriers for new entrants seeking to scale without established clinical references. At the same time, the product mix continues to shift as clinicians weigh the clinical outcomes of closed versus open suction approaches, particularly in environments where infection control protocols carry significant operational weight.
Despite steady growth, the sector faces three pressing inflection points. First, sterility assurance remains a persistent operational risk. A high-profile recall involving closed suction catheter systems, linked to potential sterility lapses from gamma irradiation process variations, underscored how quality control failures can erode clinical trust and disrupt supply continuity across multiple product lines. Second, regulatory and reimbursement frameworks are evolving in ways that reward specific design attributes. Standards governing dimensional precision, flow resistance, leakage performance, and protective sleeve integration are increasingly treated as baseline expectations rather than optional enhancements. Reimbursement policies tied to suction pumps and designated catheter categories further influence purchasing decisions, requiring manufacturers to align product portfolios with coding and coverage parameters in major markets. Third, raw material sourcing introduces cost and flexibility trade-offs. Medical-grade PVC and silicone dominate production, yet the broader medical tubing supply environment carries volatility tied to petrochemical feedstock pricing, capacity constraints, and shifting demand for biocompatible, flexible materials in single-use devices.
For executives and planners, the central question is how to navigate these pressures while capturing growth from expanding respiratory care volumes, procedural complexity, and the gradual shift of certain suction needs into lower-acuity and home-based settings. Success increasingly depends on anticipating quality scrutiny, aligning with evolving standards, and positioning product offerings where clinical and economic value intersect.
Key Drivers Shaping Market Dynamics
Technology innovation is reshaping how airway secretion management is approached, with design refinement taking center stage. Closed suction systems continue to gain clinical preference in intensive care and mechanically ventilated environments, where minimizing circuit disconnection reduces exposure to contaminants and supports ventilator-associated pneumonia prevention strategies. Integrated suction control features, reinforced lumens, and protective sleeve architectures are becoming standard expectations rather than premium add-ons. At the same time, open suction catheters remain relevant in specific procedural and emergency scenarios, particularly where rapid access, tactile feedback, or compatibility with certain airway configurations is prioritized. Manufacturers are responding by refining tip geometries, flexibility profiles, and material performance to reduce tissue trauma while maintaining suction efficiency across a range of sizes and clinical use cases.
Policy and regulatory conditions are reinforcing a compliance-first product development mindset. International standards such as ISO 8836 specify critical performance parameters for airway suction catheters, including dimensional tolerances, leakage behavior, flow resistance, and information requirements for manufacturers. In the United States, tracheobronchial suction catheter kits are generally classified as Class II devices, with many open suction catheters exempt from premarket notification but still subject to general controls, quality system expectations, and labeling requirements. A recent FDA clearance granted to disposable irrigation and suction catheter models for surgical suction and irrigation procedures illustrates how regulatory pathways are adapting to accommodate products used alongside endoscopic and handpiece applications. At the same time, voluntary recalls tied to sterility risks serve as a reminder that regulatory permissions do not eliminate the need for robust manufacturing process control, especially where gamma irradiation or sterilization validation is involved. For commercial teams, the implication is clear: evidence of compliance, validated manufacturing controls, and transparent labeling increasingly influence formulary acceptance and procurement confidence.
Tracheostomy Tube Market
Demand-side behavior is changing as healthcare delivery models diversify. Hospital and clinic settings remain the primary absorption point for suction catheters, reflecting high patient volumes, procedural intensity, and the continued centrality of airway management in critical care. However, the broader care continuum is expanding. Home care settings and ambulatory surgical centers are generating incremental demand for compact, disposable, and clinician-friendly suction solutions, particularly where patient mobility, outpatient procedures, and decentralized respiratory management are growing. This shift is not simply about volume; it is about context. Products designed for institutional use must be evaluated differently when deployed in environments with limited staffing, different storage constraints, or varied patient education needs. As a result, differentiation is increasingly tied to usability, packaging convenience, and compatibility with the equipment and workflows present in each setting.
Supply chain and cost structure dynamics are also exerting pressure on margins and sourcing strategies. The medical tubing market remains anchored in materials such as medical-grade PVC and silicone, both valued for flexibility, biocompatibility, and processability in disposable device manufacturing. Demand for these materials continues to be supported by broader adoption of single-use devices, but pricing exposure to raw material fluctuations, logistics complexity, and regional manufacturing capacity creates operational sensitivity. Companies are increasingly balancing proximity to end markets against cost efficiency, with some manufacturers building export-oriented production footprints to serve multiple geographies while others focus on localized supply to reduce lead times and improve responsiveness. The net effect is a market where procurement leverage is tied not only to unit price but also to reliability, consistency, and the ability to support bulk ordering without compromising product integrity.
PW Consulting
Competitive Landscape and Leading Strategies
The competitive field is populated by a mix of large diversified medical-supply organizations, specialized respiratory-care manufacturers, and export-focused producers based in Asia. Major U.S.-based players occupy positions where breadth of product availability, established distributor networks, and integration into institutional procurement systems provide a strong advantage. These organizations often compete on reliability, catalog breadth, and the ability to support large-scale purchasing across multiple care settings. At the same time, several specialized manufacturers focus on suction catheters as part of broader surgical or respiratory portfolios, leveraging flexible manufacturing, disposable-product expertise, and regional cost advantages to serve both domestic and international markets.
Leading companies are pursuing differentiation through a combination of product architecture, clinical positioning, and supply reliability. One common strategy is to emphasize closed-system capabilities for critical care and respiratory applications, where sterility, ease of integration with ventilation circuits, and reduced contamination risk are central selling points. Another approach centers on offering a full size range and multiple tip or valve configurations, enabling hospitals to standardize on fewer product families while still matching catheter selection to patient anatomy and procedure type. A third path involves disposable-focused manufacturing models that emphasize sterile packaging, variable order quantities, and rapid replenishment, which is particularly relevant for high-use facilities managing inventory turnover and contamination control.
Several strategic patterns stand out in how these players position themselves. Diversified suppliers tend to reinforce value through breadth and purchasing convenience, making it easier for procurement teams to consolidate orders across multiple consumables. Mid-sized and export-oriented manufacturers often compete on responsive production, competitive pricing, and adaptability to custom specifications, which can be attractive to buyers seeking flexibility or regional sourcing alternatives. In addition, product recall events have intensified attention to manufacturing controls and sterility assurance across the sector. Companies that can clearly demonstrate process discipline, traceability, and corrective action capability are better positioned to maintain trust after industry-wide quality disruptions. Conversely, organizations perceived as reliant on opaque supply processes may face heightened scrutiny from clinical and procurement stakeholders.
The market structure is evolving through a blend of consolidation pressures and segmentation opportunities. On one side, larger buyers increasingly prefer suppliers who can offer integrated consumables portfolios, consistent quality documentation, and the scale to support contract manufacturing or private-label arrangements. On the other side, niche and regionally focused producers continue to find room by addressing size ranges, material preferences, or application-specific needs that may be underserved in standardized catalogs. New entrants face a meaningful hurdle in building clinical references and distribution relationships, but product-level innovation, regulatory clearances for expanded indications, and strong regional manufacturing leverage can still create viable entry points. Over time, the competitive edge is likely to belong to organizations that combine dependable quality systems with clear differentiation in suction performance, usability, and compatibility with evolving care settings.
Forward-Looking Trends and Commercial Implications
Over the next three to five years, one defining trend will be the continued clinical prioritization of closed suction systems in ventilated and critical care environments, supported by infection-control expectations and workflow preferences. This will likely sustain demand for closed-system designs with reliable suction control, protective sleeve integrity, and strong leakage and flow-resistance performance. Companies that can deliver consistent quality while maintaining competitive cost structures will be well placed to capture share in institutions standardizing on closed-circuit airway management.
A second trend is the gradual broadening of suction catheter demand beyond traditional inpatient settings. As home care and ambulatory surgical activity expand, product requirements will increasingly emphasize ease of use, compact packaging, role-specific configurations, and compatibility with portable or lower-resource equipment. This creates opportunities for streamlined, disposable-focused product lines and kits that reduce setup complexity and support decentralized care models. At the same time, this shift brings reimbursement complexity, since coverage rules differ across catheter categories and depend on associated equipment justifications, meaning commercial success will depend on alignment with coding and coverage realities in each market.
A third trend is the growing importance of manufacturing process discipline and traceability. Sterility-related recalls in the sector have highlighted how quality failures can quickly translate into supply interruptions, clinical concern, and reputational damage. In response, procurement teams are likely to place greater weight on documented quality systems, sterilization validation, and responsiveness to corrective actions. This trend favors suppliers that can provide transparent evidence of process control and that have built resilience into their production and distribution networks. The associated risk is that any new quality incident can affect not only the involved company but also broader market confidence in specific product types or sterilization methods. Market participants should therefore treat quality assurance as a commercial differentiator rather than a back-office function.
Actionable Guidance for Decision Makers
For manufacturers, the priority is to align product roadmaps with clinical demand trends while strengthening the operational foundations that support trust in the field. This means investing in design refinements that improve suction efficiency, usability, and compatibility across care settings, while simultaneously reinforcing sterilization validation, dimensional consistency, and labeling clarity. Companies should also evaluate whether their portfolios are sufficiently flexible to serve both institutional and decentralized-care buyers, since those segments increasingly influence total demand.
For investors, the most compelling signal is the combination of steady volume growth and differentiation opportunities around quality, infection-control value, and setting-specific product design. Capital allocation should favor businesses with demonstrable manufacturing discipline, diversified end-market exposure, and the ability to navigate reimbursement nuances without overreliance on any single buyer segment. Competitive positions built on scale alone are less durable where clinical stakeholders are increasingly attentive to sterility assurance and compliance documentation.
For procurement and supply chain leaders, the strategic focus should move beyond unit cost to include supplier reliability, traceability, and the capacity to support bulk ordering without compromising sterility or delivery consistency. Evaluating suppliers on their documentation practices, recall readiness, and ability to meet recognized technical specifications can reduce downstream disruption risk. In markets where regulatory frameworks and reimbursement conditions shape purchasing, aligning product selection with those parameters can also improve cost predictability and access.
The strategic picture is clear enough to guide immediate decisions, but the granular opportunities, segment-specific pricing dynamics, and regional procurement realities require deeper evaluation. For decision makers seeking detailed segmentation data, company-level positioning, and tailored scenario analysis, the full PW Consulting report provides the depth needed to translate these market trends into targeted commercial action.
For detailed analysis of this topic, please visit the official page: Worldwide Phlegm Suction Tube Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com