

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Category: market research
FPD Lithography Systems Market: Why 5.71% CAGR and APAC's 85% Share Redefine Global Competition
By pmarketresearch, 2026-09-18
Worldwide FPD Lithography Systems Market: Strategic Trends and Commercial Opportunities Through 2032
Market Context and Core Challenges
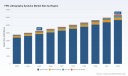
The global market for flat panel display lithography systems has expanded steadily over the past five years, with total revenue reaching approximately $4.28 billion in 2025 and projected to grow at a compound annual growth rate of 5.71 percent through 2032. This trajectory reflects sustained capital investment in display manufacturing capacity, driven by demand for larger, higher-resolution, and more specialized screens across consumer electronics, automotive, and commercial applications. Asia Pacific dominates absolute market volume due to the concentration of panel fabrication facilities and equipment procurement clusters, while North America, Europe, and other regions maintain smaller but strategically important installations, often tied to specialized display formats, defense-related applications, or regional supply chain diversification efforts.
Within this landscape, the competitive structure remains highly concentrated. A small number of established suppliers account for the overwhelming majority of shipments, reflecting the capital intensity, precision engineering requirements, and long qualification cycles associated with lithography equipment. This concentration provides stability in service and support ecosystems but also constrains rapid price competition and slows the entry of alternative technology approaches. At the same time, the product mix continues to be shaped by the relative demand for steppers and scanners, with each architecture serving distinct patterning needs depending on panel size, resolution targets, and throughput requirements.
Several structural challenges define the current inflection point. First, panel manufacturers are navigating a period of mixed demand signals, where near-term investment timing is being reassessed as buyers evaluate the impact of trade policy shifts and downstream consumption patterns. This has introduced short-term volatility in equipment order books, even as the medium-term build-out of advanced display capacity continues. Second, environmental and chemical compliance frameworks are reshaping process choices. Regulatory pressure to reduce hazardous substances in lithography-related consumables and cleaning steps is increasing validation costs and influencing equipment design, particularly for suppliers serving multiple regulatory jurisdictions. Third, the boundary between display patterning and advanced packaging is blurring as multi-lens lithography concepts are adapted for back-end semiconductor processes. This cross-pollination creates both opportunity and complexity, as equipment roadmaps must increasingly account for applications that extend beyond traditional panel lines. These dynamics mean that market growth cannot be understood purely as a function of capacity expansion; it now depends on how well suppliers and buyers align technology choices with evolving regulatory, geopolitical, and application-specific requirements.
Key Drivers Shaping Market Change
Technology innovation remains the most direct catalyst for differentiation in FPD lithography. Multi-lens architectures, improved overlay control, and new light-source optimizations are enabling higher throughput and finer definition on larger substrates. Recent product announcements illustrate this direction clearly. In late 2025, Nikon began accepting orders for Gen 8 FPD lithography systems using UV-LED light sources, with a commercial launch planned for 2026. These models emphasize reduced power consumption alongside high-definition LCD and OLED panel production, signaling a shift toward energy efficiency as a competitive attribute rather than a secondary consideration. The same multi-lens lineage is also being extended into back-end semiconductor packaging, where a digital lithography system announced in mid-2025 targets one-micron resolution and high productivity. This dual-use technology strategy broadens the addressable market for core optical and mechanical competencies while reinforcing the value of established engineering know-how.
PW Consulting
Policy and regulatory conditions are equally influential. Export controls on advanced semiconductor manufacturing equipment have expanded to cover certain lithography systems and components, with restrictions targeting specific entities and broader categories such as DUV and advanced packaging tools. These measures reshape cross-border equipment flows, encourage regional sourcing strategies, and increase the importance of compliance infrastructure for both suppliers and end users. At the same time, European chemical regulations continue to constrain the use of certain hazardous materials in lithography-adjacent processes. While these frameworks do not directly ban FPD lithography machines, they raise compliance costs and influence material selection, cleaning protocols, and vendor qualification timelines. For global suppliers, the practical implication is that product support cannot be decoupled from jurisdictional readiness; systems that can be deployed with fewer material and documentation risks gain an advantage in multi-region programs.
Demand-side behavior is evolving as display applications diversify. Automotive dashboards, ruggedized interfaces, and specialty display formats are increasing interest in larger-area panel processing, while smartphone and portable device requirements continue to drive volume in smaller and medium panel segments. This split is not merely a matter of substrate size; it affects cycle times, yield expectations, and the relative importance of overlay precision versus throughput. Buyers are increasingly selecting equipment based on application fit and total cost of ownership rather than on headline specifications alone. As a result, suppliers that can demonstrate predictable performance across multiple panel formats, with flexible light sources and robust service networks, are better positioned to capture multi-year deployment cycles.
Worldwide Direct-write Photolithography Systems Market
Supply chain and cost structure considerations further shape the market. Panel makers are balancing the desire for cutting-edge capability with the need to manage capital exposure, especially when macroeconomic signals or tariff environments introduce uncertainty. This has led to more deliberate investment pacing, with buyers weighing whether to accelerate capacity, defer purchases, or select systems that offer broader compatibility across current and future panel generations. For equipment vendors, this environment rewards designs that reduce operating energy, simplify consumables handling, and provide modular upgrade paths. The net effect is a market where technical performance still matters profoundly, but commercial resilience—through lower running costs, flexible configuration, and regulatory adaptability—is becoming equally important in procurement decisions.
Competitive Landscape and Leading Strategies
The competitive structure in FPD lithography systems is anchored by a small group of incumbent suppliers with deep optical, mechanical, and process-integration expertise. Nikon maintains a prominent position through its FX-series platform for large-area plates, and its recent focus on UV-LED light sources reflects an effort to align performance with energy efficiency and high-definition panel requirements. The company's expansion of multi-lens technology into digital lithography for back-end packaging also illustrates a broader strategy: leverage core optical competencies across adjacent markets to extend revenue potential and amortize development costs. Canon continues to compete with mirror-projection systems designed for array, color filter, and touch panel processes, with recent releases supporting Gen 6 plates for dashboard displays and smartphones. This product emphasis highlights a strategy centered on application-specific productivity and overlay accuracy for high-volume consumer and automotive display segments.
A third dimension in the landscape comes from domestic equipment development in China, where suppliers are building FPD lithography capabilities as part of broader semiconductor and display equipment initiatives. This development introduces a longer-term dynamic around regional self-sufficiency and localized support ecosystems. While the established incumbents still dominate overall shipment value, the presence of new and expanding suppliers can influence pricing expectations, service competition, and the pace at which regional buyers diversify their vendor base. The practical outcome is a market that remains concentrated but is gradually being tested by localized capability building, especially where policy incentives and domestic panel expansion reinforce demand for homegrown equipment alternatives.
Looking at strategic positioning, the leading suppliers are differentiating along three axes. The first is platform versatility, where the ability to serve multiple panel sizes and light-source configurations reduces the risk of stranded investment for buyers. The second is application extension, where technology reuse across FPD and advanced packaging broadens the commercial base and creates cross-functional engineering leverage. The third is compliance and support readiness, where suppliers that can navigate export control frameworks, chemical regulations, and regional service expectations are better equipped to sustain multi-country programs. These axes matter because FPD lithography is not a purely specification-driven purchase; it is a long-cycle capital decision shaped by qualification timelines, process integration, and operational risk. In that context, suppliers that deliver predictable performance with lower regulatory and energy-related friction are likely to capture disproportionate share in multi-year deployment cycles.
Future Trends and Commercial Implications
Over the next three to five years, the market is likely to consolidate around a few durable trends. The first is the continued migration toward energy-efficient light sources and process optimizations that lower operating costs without sacrificing throughput or definition. As panel makers face both cost pressure and sustainability expectations, equipment that reduces power consumption while maintaining high-definition output will become a stronger differentiator in procurement evaluations. The second trend is the growing relevance of multi-lens and digital lithography concepts beyond traditional panel lines. As back-end packaging and specialty patterning applications adopt similar optical architectures, suppliers with adaptable platforms can capture incremental demand and create cross-market roadmap synergies. This expansion also increases the strategic importance of resolution, overlay stability, and productivity in a wider set of use cases.
Flat Panel Display (FPD) Inspection Equipment Market
The third trend is a more regionally differentiated market rhythm. Export controls, aligned policy actions, and shifting tariff environments are prompting panel manufacturers and equipment buyers to reassess procurement timing and vendor selection. In the near term, this can manifest as temporary pauses in investment as buyers gauge downstream demand and policy impacts. Over a longer horizon, it is likely to encourage more diversified sourcing strategies and greater emphasis on regional support, documentation readiness, and compliance-compatible configurations. The commercial opportunity here lies in aligning product roadmaps with deployment realities: systems that can be integrated quickly across multiple regulatory contexts, supported locally, and scaled across panel formats will be better positioned to win in a fragmented but still growing market.
Potential risks should not be underestimated. Demand timing remains sensitive to consumer electronics cycles, automotive display programs, and broader trade policy uncertainty. Chemical and environmental compliance costs may rise further, particularly for suppliers operating across multiple jurisdictions. And while platform versatility is valuable, overextension into adjacent applications can strain engineering resources if qualification and service commitments are not matched to market readiness. The commercial implication is that growth will increasingly accrue to participants who can balance technical ambition with operational pragmatism, selecting where to lead on performance and where to compete on total cost of ownership and deployment flexibility.
Strategic Actions for Decision Makers
For display and equipment manufacturers, the priority is to align product and capacity planning with the applications that offer the best balance of volume, margin, and regulatory compatibility. This means evaluating light-source efficiency, multi-panel flexibility, and service readiness as first-order decisions rather than secondary features. For investors, the opportunity lies in identifying participants with durable platform reuse, strong compliance infrastructure, and credible paths into adjacent packaging or specialty patterning applications, while monitoring demand-pacing signals that can affect near-term order visibility. For procurement teams and panel makers, the focus should be on total cost of ownership across the deployment lifecycle, including energy consumption, consumables and chemical compliance, qualification lead times, and regional support coverage. In a market where investment timing is increasingly sensitive to policy and demand uncertainty, detailed visibility into product roadmaps, regulatory impact, and application-specific requirements can materially improve capital allocation decisions. A closer review of the full market data set, including segmentation detail and company-level developments, can help decision makers sharpen those choices with greater precision.
For detailed analysis of this topic, please visit the official page: Worldwide FPD Lithography Systems Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Worldwide Graphene Electric Floor Heating Market: 14.85% CAGR and $1.67B Trajectory
By pmarketresearch, 2026-09-18
Strategic Trends and Commercial Opportunities in the Worldwide Graphene Electric Floor Heating Market
Market Overview and Core Challenges
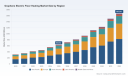
The worldwide graphene electric floor heating market has entered a phase of accelerated expansion, moving from a niche technological concept to a commercially viable heating solution. Valued at approximately USD 634.52 million in 2025, the market has demonstrated consistent growth since 2020, when revenues stood at 315.6 million. The trajectory suggests a compound annual growth rate of 14.85 percent through 2032, with projected revenues reaching 1,672.41 million by the end of the forecast period. This growth curve indicates that graphene-based heating is no longer merely an alternative but is becoming a significant component of the broader electric heating ecosystem.
The market structure reveals a fragmented landscape despite the rapid revenue expansion. Concentration ratios remain relatively low, with the top three players holding approximately 18.25 percent of the market and the top five capturing 27.6 percent. This fragmentation suggests that while leading innovators are carving out strong positions, significant room remains for consolidation or for new entrants to capture share through differentiated technology or regional focus. The revenue base is heavily weighted toward specific product forms and applications, indicating where commercial adoption is currently most mature.
Several critical challenges define the current industry inflection point. First, the translation of laboratory-grade graphene performance into consistent, scalable manufacturing remains a hurdle. While thermal efficiency claims are strong, maintaining uniform dispersion of graphene within heating films or mats across large production runs requires precise process control. Variability in material quality can impact heating consistency and product longevity, creating a barrier for widespread adoption in commercial and industrial settings where reliability is paramount.
Second, the market faces a certification and standardization gap. Although multiple manufacturers hold international certifications such as RoHS, REACH, CE, UL, and TUV, the absence of a single unified global standard for graphene heating performance can complicate cross-border trade and procurement decisions. Buyers in regulated sectors often require extensive verification, slowing deployment cycles. As the market scales, harmonized standards will likely become a competitive differentiator rather than just a compliance checkbox.
Underfloor Heating Market
Third, the integration of graphene heating into existing building infrastructure presents both an opportunity and a friction point. Modular designs that enable retrofitting without significant floor height loss are emerging, yet widespread adoption requires alignment with construction workflows, electrical system capacities, and installer training. The labor cost savings associated with simplified installation are compelling, but realizing these savings at scale depends on industry-wide familiarity with the technology and reliable supply chains for compatible flooring and control systems.
Key Drivers of Market Dynamics
The expansion of the graphene electric floor heating market is propelled by a convergence of technological breakthroughs, regulatory momentum, shifting demand patterns, and evolving supply chain economics. Each driver reinforces the others, creating a self-accelerating adoption cycle in specific regions and applications.
Technological Innovation and Performance Breakthroughs
Graphene materials have enabled far-infrared conversion rates reaching up to 76 percent in electric floor heating systems, supporting high thermal efficiency with power density around 16W/m²/h for building-area calculations. This efficiency profile translates into faster heat-up times, more even heat distribution, and the potential for energy savings of 50 to 70 percent compared to conventional systems in real-world trials. These performance characteristics are not merely technical specifications; they directly address the core value proposition that building owners and occupants care about: comfort, control, and operating cost reduction.
Recent commercial milestones illustrate how technology is crossing the valley from prototype to deployed reality. In December 2024, a real-world deployment at Eden House respite care home demonstrated 50 percent less energy consumption than a gas boiler, providing tangible evidence of operational savings in a setting where heating reliability and efficiency are critical. The scientific and economic case for this approach was formalized in a white paper released in March 2025, strengthening the narrative for procurement teams and investors evaluating the technology's maturity.
Product certification progress further signals commercial readiness. The launch of a graphene underfloor heating system with UL certification in April 2025 removed a significant barrier for market entry in regions where safety and performance validation is mandatory. By mid-2025, the manufacturer had secured UL certification, positioning the product for broader commercialization in North American and other regulated markets.
Policy and Regulatory Environment
Regulatory frameworks and sustainability mandates are reshaping heating procurement decisions globally. Graphene underfloor heating systems comply with international standards including RoHS, REACH, CE, UL, and TUV certifications, ensuring no electromagnetic radiation or harmful emissions. This compliance profile aligns with tightening building codes and indoor air quality requirements, making graphene heating an attractive option for projects that must meet stringent environmental and safety criteria.
The broader macro trend toward net-zero goals provides additional tailwinds. Graphene-based electric floor heating supports decarbonization objectives through faster heat-up times, even distribution, and potential energy savings that reduce overall electricity demand. In regions where electrification of heat is being prioritized over fossil fuel systems, the efficiency advantages of graphene heating strengthen the economic case for adoption. Policy incentives for energy-efficient renovations, low-carbon heating installations, and smart building integration are likely to amplify demand, particularly in markets where retrofit activity is accelerating.
Demand-Side Shifts in Consumer and Enterprise Behavior
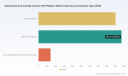
Demand is being shaped by a dual dynamic: residential consumers seeking comfortable, energy-efficient heating solutions and commercial entities under pressure to reduce operating costs while meeting sustainability targets. The residential segment currently represents the largest application base, reflecting the technology's suitability for homes where even heat distribution and zone-level control deliver noticeable comfort improvements. However, the commercial segment is gaining momentum as facility managers evaluate heating upgrades that can deliver measurable energy savings and align with corporate ESG commitments.
The industrial segment, while smaller in current revenue terms, represents a strategic frontier. Applications requiring uniform radiant heat in controlled environments, such as drying processes or specialized manufacturing spaces, could benefit from graphene heating's efficiency and modularity. As operators in these sectors look to reduce energy intensity and improve process control, graphene-based solutions may find niche but high-value deployments.
Consumer and buyer behavior is also being influenced by the growing availability of verified performance data. The shift from theoretical efficiency claims to documented case studies, such as the Eden House deployment, reduces perceived risk for early adopters. As more real-world evidence accumulates, procurement cycles are likely to shorten, particularly in sectors where heating costs are a significant line item.
Supply Chain and Cost Structure Evolution
The supply chain for graphene electric floor heating is evolving from fragmented, region-specific production toward more integrated value chains that emphasize material consistency, certification readiness, and installation simplicity. Modular graphene electric underfloor heating designs enable easy DIY or retrofit installation without occupying floor height, reducing labor requirements for installation and maintenance. These design advantages directly impact total cost of ownership by lowering both upfront installation expenses and long-term maintenance burdens.
At the same time, the cost structure of graphene materials and their integration into heating films, mats, and cables continues to mature. As production processes stabilize and demand scales, economies of scale are expected to improve margin profiles for manufacturers that can maintain quality control while expanding volume. Suppliers that invest in capacity, certification, and application-specific product variants are better positioned to capture value as the market transitions from early adoption to broader commercial penetration.
Competitive Landscape and Leading Strategies
The competitive landscape is characterized by a mix of specialized graphene technology firms, established heating manufacturers, and regional players with strong distribution networks. The market's low concentration ratios indicate that no single entity currently dominates, creating opportunities for companies that can combine technological differentiation with scalable commercial execution.
Strategic Positioning of Key Players
Haydale Graphene Industries, based in Ammanford, United Kingdom, has positioned itself at the intersection of material science and applied heating systems. Its Just Heat functionalised graphene underfloor heating system leverages patented HDPlas® technology to deliver low-voltage, energy-efficient electric floor heating with rapid response and even heat distribution. The company's recent activities reflect a deliberate progression from technical validation to commercial scaling. The release of a scientific and economic case white paper in March 2025, combined with a completed real-world deployment demonstrating 50 percent energy savings versus a gas boiler, strengthens its credibility with procurement teams and partners. The subsequent UL certification and a distribution agreement with Interfloor for an integrated flooring range, with commercial launch targeted for the first half of 2026, signal a shift toward channel-driven growth and broader market access.
In China, several manufacturers have established strong positions in graphene heating films and underfloor heating solutions. Clean Concept Technology Limited (CCT), operating from Shanghai and Jiangsu, manufactures and exports graphene floor heating films and underfloor heating solutions, including waterproof PE/PVC-encapsulated mats suitable for dry and wet environments. Its portfolio of certifications, including ISO9001, ISO14001, ISO45001, CE, RoHS, and TUV, supports its export-oriented strategy and reinforces trust in regulated markets. Wuxi BENELLI New Material Co., Ltd. supplies graphene electric heating floor systems that utilize advanced graphene materials for uniform, energy-efficient radiant heating suitable for various flooring types, emphasizing compatibility and versatility. Nuanjia Graphene Carbon New Energy (Qingdao) Co., Ltd. is one of the early entrants in clean energy heating in China and has played a role in setting graphene and electric heat film standards, giving it a foundational position in shaping industry norms. 2D Carbon (Changzhou) Tech Inc., Ltd. develops and supplies graphene underfloor heating films and systems with a focus on even heat distribution and energy efficiency, complemented by established graphene transparent conductive film production capabilities that may support broader material applications. Levson Tech (Levson Green Heating) offers graphene electric underfloor heating modules with rapid uniform heating, IPX7 waterproofing, and far-infrared radiation, holding certifications including UL, RoHS, CE, and TUV, and claims a role as a graphene floor heating industry standard setter in China. Shengxihong (Shengxihong Heat Tech) specializes in graphene heating film products and systems emphasizing energy efficiency and even heat distribution, rounding out a competitive field where product reliability and certification portfolios are central to winning bids.
ALIKO CO., LTD., based in South Korea, produces and exports graphene PTC carbon floor heating films for infrared radiant electric underfloor heating systems, highlighting the regional diversity of innovation and the importance of geographic reach in serving localized demand.
Differentiation and Competitive Advantages
Across this landscape, differentiation is emerging along several axes. Technology-led players emphasize patented material functionalization, low-voltage operation, and documented energy savings, targeting customers who prioritize performance verification and long-term operating cost reduction. Manufacturers with strong certification portfolios and waterproof or versatile product designs are better positioned for commercial and multi-environment applications where durability and compliance are non-negotiable. Early entrants that have contributed to standard-setting activities gain influence over product specifications and testing expectations, which can create barriers for later entrants and strengthen customer confidence.
Channel strategy is also becoming a critical differentiator. Partnerships with flooring integrators, distribution agreements, and integrated product ranges can accelerate adoption by reducing the friction of specifying and installing graphene heating as part of a broader building solution. Companies that align their products with existing construction and renovation workflows are likely to gain share more rapidly than those requiring entirely new installation paradigms.
Market Structure Evolution
The market is expected to evolve through a combination of consolidation, specialization, and new entry. As the technology matures, larger heating or building materials companies may seek to acquire or partner with specialized graphene heating firms to add efficient electric heating capabilities to their portfolios. Simultaneously, regional players with strong local certifications, distribution networks, and cost advantages will continue to compete effectively in their home markets and export channels. New entrants may find opportunities in adjacent applications, advanced control integration, or hybrid systems that combine graphene heating with smart building management platforms. The balance between consolidation and fragmentation will depend on how quickly standards harmonize, how rapidly demand scales in commercial and industrial segments, and whether material supply chains stabilize at scale.
PW Consulting
Future Trends and Commercial Implications
Looking ahead to the next three to five years, several trends are likely to shape the trajectory of the graphene electric floor heating market and define where commercial value is captured.
First, the transition from residential-led growth to broader commercial and light industrial adoption will accelerate as verified performance data accumulates and certification coverage expands. Projects that can demonstrate measurable energy savings, such as the 50 percent reduction observed in the Eden House deployment, will serve as reference points for procurement teams evaluating heating retrofits and new builds. Commercial opportunities will emerge for solution providers that can bundle graphene heating with energy management controls, flooring integration, and performance guarantees, reducing the perceived risk of adoption.
Second, standardization and certification harmonization will become a competitive battleground. As more manufacturers achieve UL, CE, TUV, and other certifications, buyers will increasingly compare not just compliance but the depth and relevance of testing to their specific applications. Companies that invest in application-specific validation and transparent performance reporting will be better positioned to win in regulated sectors and cross-border markets. This trend also creates an opportunity for industry associations and standards bodies to define consistent testing protocols, which could reduce procurement friction and accelerate mainstream adoption.
Third, integration with smart building ecosystems and modular retrofit designs will expand the addressable market. Modular graphene electric underfloor heating designs that enable easy installation without significant floor height loss align with the growing demand for renovation-friendly solutions. When combined with intelligent controls that optimize heating schedules, zone temperatures, and energy usage, graphene systems can deliver compound value through both efficiency and convenience. Manufacturers and partners that develop integrated offerings spanning heating, controls, and flooring will capture more of the project value chain.
Potential risks and uncertainties remain. Material cost volatility, scaling challenges in graphene dispersion and film production, and the pace of regulatory alignment could affect margin profiles and deployment timelines. In addition, competition from alternative low-carbon heating technologies, including heat pumps and other electric heating formats, will require graphene heating to continually demonstrate its comparative advantages in comfort, installation ease, and energy efficiency. Market participants should monitor these dynamics closely, as the relative attractiveness of graphene heating will depend on how it performs against alternatives in real-world cost, reliability, and user experience terms.
Graphene Chip Market
Strategic Recommendations for Decision-Makers
For manufacturers, the priority is to strengthen the link between material innovation and commercial execution. Investing in consistent production quality, expanding certification coverage, and developing application-specific product variants can differentiate offerings in a fragmented market. Partnerships with flooring integrators, distributors, and control system providers can accelerate adoption by embedding graphene heating into familiar procurement and installation pathways. Companies that can document real-world energy savings and reliability across diverse environments will be best positioned to move from early adoption to broader market penetration.
For investors, the market presents opportunities in companies with clear technological differentiation, credible certification portfolios, and demonstrated deployment evidence. Due diligence should focus on manufacturing scalability, material supply stability, and the ability to transition from pilot projects to repeatable commercial sales. Exposure to players that are building integrated product ranges or securing distribution agreements may offer stronger commercial momentum than those relying solely on standalone product sales. Monitoring standardization developments and regional policy incentives will also help identify where demand is likely to accelerate.
For procurement and facility decision-makers, the emphasis should be on evaluating total cost of ownership rather than upfront price alone. Requesting verified performance data, checking certification relevance to the intended application, and piloting installations in controlled settings can reduce adoption risk. Engaging with suppliers that offer modular, retrofit-friendly designs and clear integration pathways with existing electrical and flooring systems can lower installation complexity and labor costs. As the market matures, early engagement with vendors that provide transparent documentation and performance guarantees will support more confident investment decisions.
For stakeholders seeking deeper segmentation data, regional breakdowns, and customized strategic guidance, the full research report provides detailed figures and scenario analysis to support planning and investment decisions.
For detailed analysis of this topic, please visit the official page: Worldwide Graphene Electric Floor Heating Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Worldwide Submersible Market Surpasses $285M: The 8.74% CAGR Playbook
By pmarketresearch, 2026-09-18
Navigating the Strategic Currents: Commercial Submersible Market Trends and Opportunities Through 2032
Market Status and Core Challenges
The global commercial submersible market has demonstrated robust momentum over the past five years, evolving from a mature industrial segment into a dynamic growth arena. Valued at approximately $182.15 million in 2020, the market expanded steadily to reach $285.5 million by 2025, reflecting a compound annual growth rate of 8.74 percent projected through the 2032 forecast period. This trajectory signals more than incremental improvement; it indicates a structural shift where submersible technology is becoming integral to broader commercial and industrial workflows. The projected valuation ceiling of over $513 million by 2032 underscores the accelerating adoption across diverse operational environments.
Despite this positive momentum, the industry stands at a critical inflection point defined by three interconnected challenges. First, the regulatory landscape is tightening globally, forcing manufacturers to reconcile performance demands with increasingly stringent efficiency standards. The drive toward sustainability is no longer optional but a licensing requirement for market access in key regions. Second, supply chain volatility continues to pressure cost structures, particularly regarding raw material pricing and availability. Fluctuations in steel markets directly impact production economics, creating margin compression risks for companies unable to optimize procurement or redesign for material efficiency. Third, the market is experiencing a divergence in application requirements, where the needs of heavy industrial operations increasingly conflict with the precision and reliability demands of municipal and commercial infrastructure. Manufacturers must decide whether to specialize deeply or maintain broad portfolios capable of addressing conflicting specifications.
Underwater Pelletizer Market
Key Drivers of Market Change
Technological Innovation and Performance Breakthroughs
Technological advancement remains the primary catalyst propelling market expansion. The industry is witnessing a transition from conventional mechanical designs to engineered systems that prioritize energy efficiency, material durability, and operational intelligence. Recent product introductions highlight this shift toward purpose-built submersible solutions. KSB SE & Co. KGaA expanded its portfolio with the CORAChrom stainless-steel range engineered for deep borehole and demanding freshwater and saline environments. This launch targets irrigation, dewatering, construction, mining, and commercial building sectors, addressing the need for corrosion-resistant performance in harsh conditions. Later in the same year, the company introduced submersible motor pumps featuring axial propellers, demonstrating continued investment in hydrodynamic optimization for enhanced efficiency.
Similarly, Franklin Electric advanced its position through targeted product development. The launch of the Pioneer Pump Minetuff series in early 2025 focused on abrasive material handling with durable construction and adjustable hydraulics. This was followed by an expansion of the FPS Wastewater Pumps lineup, adding sump, effluent, and grinder models designed for commercial applications with improved solids-handling capabilities. These developments reflect a broader industry pattern where manufacturers are engineering products for specific operational pain points rather than offering generic solutions. The emphasis on anti-clogging hydraulics, explosion-proof options, and variable operating conditions indicates that customers increasingly demand reliability under extreme or unpredictable conditions.
Regulatory and Policy Environment
Regulatory frameworks are reshaping competitive dynamics by establishing minimum performance thresholds that all market participants must meet. The EU Ecodesign Regulation establishes efficiency benchmarks for water pumps, requiring a Minimum Efficiency Index value at or above 0.4, with ongoing reviews exploring expansion to wastewater and industrial submersible pumps. This regulatory trajectory pushes manufacturers to prioritize motor efficiency and hydraulic optimization during the design phase rather than treating efficiency as an afterthought. In the United States, energy conservation standards and test procedures emphasize wire-to-water efficiency for submersible motor-driven pumps, covering hydraulic performance, hydrostatic, mechanical, and electrical acceptance tests. Compliance with these standards is becoming a baseline requirement for commercial procurement, particularly in government and municipal contracts where regulatory adherence is mandatory.
Beyond efficiency mandates, policy-driven infrastructure investment is creating sustained demand. Increasing infrastructure investments and urbanization are driving demand for submersible pumps in wastewater management and groundwater extraction across commercial sectors. Government spending on water infrastructure, flood mitigation, and urban development projects generates recurring procurement cycles that favor established suppliers with proven compliance records. However, regulatory fragmentation across regions also creates complexity, as manufacturers must navigate differing standards when serving global markets.
Demand-Side Shifts and Application Diversification
Customer behavior and application requirements are evolving in ways that expand the addressable market while raising performance expectations. The growing emphasis on sustainable water management and resilient infrastructure is pushing end users to adopt submersible solutions that offer longer service life, lower total cost of ownership, and reduced environmental impact. In commercial and industrial settings, operators are prioritizing systems that minimize downtime and maintenance intervention, recognizing that operational continuity directly impacts revenue and compliance. This shift favors suppliers who can provide integrated solutions combining durable materials, efficient motors, and application-specific hydraulic designs.
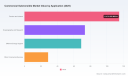
Material composition trends also reflect changing demand patterns. Cast iron accounts for approximately 41 percent of submersible pump material usage in industrial and municipal applications due to its durability and cost-effectiveness, while stainless steel holds a 34 percent share driven by corrosion resistance. This material distribution indicates that customers are making deliberate trade-offs between initial cost and long-term performance based on their operating environment. As applications extend into more corrosive or abrasive conditions, the demand for advanced materials is likely to grow, pushing manufacturers to expand their material engineering capabilities.
Supply Chain and Cost Structure Dynamics
Cost structures remain a critical factor influencing market competitiveness. Input material pricing, particularly steel, directly affects manufacturing economics and final product pricing. US steel prices are expected to range between $931 and $1,100 per ton by the second quarter of 2026, influenced by tariffs and infrastructure demand. This pricing environment creates both challenges and opportunities. Manufacturers with diversified sourcing strategies, vertical integration, or material optimization expertise can mitigate cost pressures and maintain margin stability. Conversely, companies reliant on single-source procurement or lacking engineering flexibility may face significant margin erosion. The dynamic also encourages innovation in material substitution and design efficiency, as reducing material intensity without compromising performance becomes a competitive differentiator.
Competitive Landscape and Leading Strategies
The market exhibits moderate concentration, with the top three firms capturing approximately 45.5 percent of revenue and the top five firms accounting for 62.3 percent. This concentration indicates a landscape where established players hold significant market share but leave substantial room for specialized competitors and regional specialists. The competitive environment is characterized by a mix of global technology leaders, regional manufacturers with strong cost positions, and niche providers focused on specific applications or material specialties.
Xylem Inc., headquartered in Washington, DC with major operations in Rye Brook, NY, offers a broad portfolio of submersible pumps including the Flygt brand for wastewater, drainage, and industrial and commercial applications. The company's strategic emphasis on solids-handling and energy-efficient designs positions it as a solutions provider for complex wastewater and drainage challenges. Grundfos Holding A/S, based in Bjerringbro, Denmark, provides submersible pumps for commercial wastewater, drainage, and rainwater systems in buildings. Its focus on reliability, high efficiency, and sustainability solutions aligns with regulatory trends and the growing demand for environmentally responsible infrastructure equipment. Sulzer AG, operating from Winterthur, Switzerland, supplies submersible pumps as part of broader fluid engineering solutions for wastewater, industrial processes, and water treatment applications, leveraging its engineering heritage to serve customers requiring integrated system performance.
European manufacturers continue to demonstrate strong product innovation and engineering specialization. KSB SE & Co. KGaA, headquartered in Frankenthal, Germany, manufactures submersible pumps including the CORAChrom stainless-steel range for borehole, dewatering, irrigation, and industrial applications in demanding freshwater and saline environments. The company's recent launches, including axial propeller motor pumps, highlight a strategy centered on continuous hydraulic and material innovation. This approach allows KSB to command premium positioning in applications where performance and durability justify higher initial investment.
North American suppliers are emphasizing application-specific durability and system integration. Franklin Electric Co., Inc., based in Fort Wayne, Indiana, specializes in submersible motors, pumps, and systems including the Pioneer Pump Minetuff series for dewatering and FPS wastewater pumps for sump, effluent, and grinder applications in commercial and industrial settings. The company's recent expansion of its wastewater pump lineup demonstrates a focus on capturing demand from municipal and commercial infrastructure projects that require reliable solids handling and flexible configuration options.
Japanese manufacturers maintain a strong presence through robust design philosophies and global distribution networks. Tsurumi Pump, headquartered in Osaka, Japan with global subsidiaries, produces durable cast-iron submersible pumps for wastewater, dewatering, and sewage, including the AVANT line with anti-clogging hydraulics and explosion-proof options for commercial and industrial use. The company showcased these products at major industry events, reinforcing its commitment to visibility and customer engagement in key markets. Ebara Corporation, based in Tokyo, Japan, offers submersible pumps for water supply, wastewater, and industrial applications with robust designs tailored for global commercial markets, emphasizing reliability and broad applicability.
Specialized industrial suppliers serve demanding segments where abrasive handling and harsh environment performance are critical. Flowserve Corporation, headquartered in Irving, Texas, provides submersible pumps for industrial, oil and gas, and chemical process applications with a focus on reliability in harsh commercial environments. Weir Group PLC, based in Glasgow, Scotland, supplies heavy-duty submersible slurry pumps such as the WARMAN SHW-XTR series for mining and industrial abrasive applications, targeting sectors where conventional pump designs fail under extreme wear conditions. Taian OCEAN Pump Co., Ltd., operating from Taian, Shandong, China, manufactures submersible slurry and sand pumps such as the ZJQ series for industrial, mining, and dredging commercial uses, exporting to over 60 countries. This company represents the growing influence of cost-competitive manufacturers expanding their global footprint through export-oriented strategies.
The competitive landscape is evolving through a combination of consolidation and differentiation. Larger players are acquiring or developing specialized technologies to broaden their application coverage and strengthen their position in high-value segments. At the same time, regional and application-focused manufacturers are carving out sustainable niches by offering tailored solutions, responsive service, and competitive pricing. New entrants face significant barriers related to engineering expertise, regulatory compliance, and established distribution networks, but opportunities exist in underserved regions or specialized applications where incumbent coverage is limited. The trend points toward a market where success depends on balancing scale advantages with the agility to address specific customer requirements.
Future Trends and Predictions
Looking ahead to the 2027 through 2030 period, several interconnected trends will shape the commercial submersible market and create distinct business opportunities. The first major trend is the acceleration of efficiency-driven product evolution. As regulatory standards broaden and customer total cost of ownership calculations become more sophisticated, manufacturers that lead in motor efficiency, hydraulic optimization, and material durability will capture premium market segments. Companies investing in advanced materials, corrosion-resistant alloys, and smart monitoring capabilities will be well positioned to serve applications where downtime costs and environmental compliance are critical. The opportunity lies in developing integrated solutions that combine high efficiency with long service life, reducing lifecycle costs for end users while differentiating from commoditized alternatives.
The second trend is the geographic expansion of demand driven by infrastructure development and urbanization in emerging markets. Regions experiencing rapid industrial growth, water scarcity challenges, and investment in wastewater management will generate sustained procurement activity. Manufacturers that establish local service presence, adapt products to regional operating conditions, and navigate local regulatory requirements will benefit from this expansion. The opportunity extends beyond equipment sales to include maintenance contracts, system upgrades, and performance-based service models that generate recurring revenue and deepen customer relationships. However, competition in these markets will intensify as both global players and regional manufacturers pursue growth, requiring clear value propositions and operational excellence.
The third trend involves the increasing importance of supply chain resilience and cost management as strategic capabilities. With input material prices subject to volatility from tariffs, infrastructure demand, and geopolitical factors, manufacturers must develop flexible sourcing strategies, invest in material efficiency, and explore alternative materials where performance allows. The ability to maintain stable pricing while preserving quality will become a competitive advantage, particularly in price-sensitive commercial segments. At the same time, customers will increasingly value suppliers who can provide transparency, reliable delivery, and risk mitigation support. Companies that integrate supply chain agility with engineering innovation will be better equipped to navigate cost pressures while meeting evolving customer expectations.
Potential risks include regulatory fragmentation that increases compliance complexity, sudden shifts in raw material availability that disrupt production planning, and economic downturns that delay infrastructure investment cycles. Manufacturers and investors should monitor policy developments, material market indicators, and regional infrastructure spending patterns to anticipate changes and adjust strategies proactively.
Commercial Small Batteries Market
Strategic Recommendations for Decision Makers
For manufacturers, the priority should be deepening application-specific engineering capabilities while maintaining cost discipline. Investing in advanced materials, efficiency optimization, and modular design architectures enables companies to serve demanding segments without sacrificing margin stability. Building robust service and support networks, particularly in growth regions, strengthens customer retention and creates opportunities for value-added offerings beyond equipment sales.
For investors, the market presents opportunities in companies with strong technology differentiation, regulatory compliance records, and exposure to infrastructure-driven demand cycles. Evaluating suppliers based on their ability to manage cost volatility, expand into high-growth applications, and maintain competitive positioning in concentrated segments will help identify resilient investment targets. Monitoring recent product launches, trade show presence, and material innovation pipelines provides early signals of competitive momentum.
PW Consulting
For procurement and operations leaders, selecting submersible solutions requires balancing initial cost with lifecycle performance, regulatory compliance, and supplier reliability. Prioritizing manufacturers with proven efficiency credentials, durable material specifications, and responsive service capabilities reduces operational risk and supports long-term cost management. Engaging with suppliers that offer application engineering support and transparent total cost of ownership analysis leads to better procurement decisions aligned with operational goals.
Detailed segmentation data, regional breakdowns, competitive benchmarking, and customized strategic assessments provide the depth required for precise decision making. Accessing comprehensive market intelligence enables stakeholders to validate assumptions, identify underserved segments, and develop targeted strategies that align with evolving market dynamics.
For detailed analysis of this topic, please visit the official page: Worldwide Commercial Submersible Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Automotive Connectivity Control Unit Platform Market: Why 15.62% CAGR Redefines Future Competition
By pmarketresearch, 2026-09-18
The Connected Cabin Takes Command: Strategic Shifts in the Global Automotive Connectivity Control Unit Platform Market
Market Snapshot: Growth Trajectory and Structural Tension
The global automotive connectivity control unit (CCU) platform market has entered a phase of rapid expansion, driven by the critical need to keep vehicles continuously linked to cloud services, telematics infrastructure, and external networks. The sector has grown substantially over the past five years and is projected to maintain a robust annual growth rate through the early 2030s. Valued at roughly 1.8 billion USD in 2020, the market surpassed 4 billion USD by 2025 and is on track to exceed 11 billion USD by 2032. This sustained trajectory reflects a structural shift rather than a temporary surge: automakers are embedding connectivity as a foundational layer of vehicle architecture, moving from isolated infotainment modules to centralized compute platforms that handle data routing, over-the-air updates, and cloud synchronization across the entire vehicle fleet.
This growth, however, operates within a landscape defined by logistical and technological friction. Manufacturers are navigating a period where vehicle intelligence is no longer optional, yet the physical and regulatory constraints of deployment create a pronounced tension between ambition and execution. Several structural challenges are defining the current inflection point.
First, semiconductor reliability remains a persistent vulnerability. Continental automotive controllers and connectivity modules depend on highly specialized chips that are subject to geopolitical and manufacturing disruptions. When key suppliers face interruptions, the ripple effect delays platform launches, disrupts production schedules, and forces engineering teams to redesign around alternative components without compromising performance. The automotive supply chain for electronic control units has proven highly sensitive to single points of failure, and connectivity platforms sit at the center of this dependency. The continued reliance on multi-thousand-chip architectures means that even targeted shortages can bottleneck vehicle assembly lines and delay software-integrated feature rollouts.
Second, the industry is wrestling with architecture consolidation. Traditional centralized domain controllers are giving way to integrated one-board, one-chip computing units that house multiple functions in a single physical envelope. While this shift reduces size and weight, improves thermal management, and simplifies wiring complexity, it introduces new validation and supply demands. Engineers must prove that consolidated platforms meet safety, security, and performance standards across multiple domains simultaneously, and suppliers must rethink validation cycles, testing protocols, and certification pathways. The engineering effort to merge connectivity, compute, and control functions onto unified hardware is substantial and changes the economics of platform development.
Third, the global regulatory mosaic around digital keys, V2X communication, and cybersecurity is still maturing. Organizations pushing for unified standards are advancing the conversation, but compliance remains fragmented across regions. Manufacturers deploying connectivity platforms must balance the pressure to introduce features quickly with the need to satisfy differing certification regimes, data governance expectations, and interoperability requirements. Platforms that work seamlessly in one market can face architectural or certification hurdles in another, making global scalability a material execution challenge.
These factors collectively shape a market that is expanding rapidly but demanding more sophisticated execution. The winning platforms will be those that can deliver connectivity capacity, secure data handling, and architecture flexibility without becoming choke points in the broader vehicle development and supply chain.
Key Drivers of Change: Technology, Policy, Demand, and Supply Dynamics
The expansion of the CCU platform market is propelled by a convergence of forces that are reshaping how vehicles are designed, validated, and monetized after sale. The most influential driver is the evolution of hardware and software architecture toward integrated connectivity-centric compute. The industry is shifting toward one board and one chip solutions that consolidate connectivity, domain control, and data processing into a single platform. This consolidation compresses the physical footprint of central computing units, reduces weight and wiring complexity, and streamlines thermal and power management. For automakers, the operational benefit is clear: fewer discrete modules mean simpler integration, faster development cycles, and more efficient update delivery. Connectivity platforms embedded in centralized architectures also become the strategic hub for over-the-air updates, fleet telemetry, and cloud-based service layers, turning connectivity into a platform for long-term vehicle value rather than a standalone feature.
Policy and standardization activity is the second major driver. Governments and industry bodies are moving toward unified frameworks for digital keys, vehicle-to-everything communication, and connected service interoperability. These efforts are reducing uncertainty for manufacturers who need to deploy features across multiple markets without rebuilding connectivity architectures for each regulatory environment. As standards around secure access, authentication, and external communication gain traction, platforms that can align with global certification pathways gain a distinct advantage. At the same time, regulatory attention to cybersecurity and data handling is raising the bar for connectivity modules, pushing manufacturers to design security and data governance into the platform layer rather than layering it on after the fact. This shift makes secure, standards-aligned connectivity hardware and software a market prerequisite rather than a differentiator.
Consumer and enterprise demand is reshaping the value proposition of connected platforms from both ends of the vehicle lifecycle. On the consumer side, expectations for seamless connectivity, remote diagnostics, subscription-based services, and intelligent digital access are accelerating. Digital key adoption, telematics-enabled features, and cloud-managed vehicle services are moving from niche offerings to mainstream expectations. On the enterprise side, fleet operators and mobility providers are demanding telemetry, asset tracking, remote diagnostics, and centralized management capabilities that scale across large vehicle populations. These use cases push connectivity control units beyond passenger convenience toward fleet intelligence, predictive maintenance, and operational optimization. As vehicles become data-generating assets, the connectivity layer becomes the interface between the vehicle and the services that extract value from that data.
Supply chain structure and cost dynamics are also acting as a catalyst for platform strategy. The average vehicle relies on over a thousand semiconductor components, and the connectivity stack sits at the intersection of this dependency. Manufacturers are actively rethinking how connectivity modules are sourced, integrated, and validated to reduce exposure to single-supplier risk and component volatility. This has encouraged a wave of platform thinking that prioritizes modularity, standardized interfaces, and forward-compatible architectures that can accommodate evolving chip roadmaps without full redesigns. Cost structures are further influenced by the move toward integrated compute, which can reduce bill-of-materials complexity when executed well, but demands careful engineering to avoid performance or security trade-offs. The net effect is that connectivity platforms are no longer evaluated solely on bandwidth or communication protocol support; they are increasingly assessed on their ability to anchor broader vehicle architecture, withstand supply disruption, and support long-term service monetization.
Competitive Landscape and Strategic Positioning
The competitive environment is defined by a mix of established tier-one suppliers, technology-rich electronics manufacturers, and software-focused entrants that are expanding their footprint in centralized connectivity architectures. A handful of global players collectively hold the largest share of platform revenue, while a broader group of specialists competes on regional expertise, software integration, and domain-specific capabilities. The market is neither fully consolidated nor fragmented; it is evolving toward a structure where scale in hardware integration matters, but differentiation increasingly comes from how connectivity platforms interface with software, cloud services, and vehicle architectures.
A core group of established players is positioning connectivity control as the bridge between hardware and cloud-connected vehicle services. Leading global tier-one suppliers are offering connectivity hubs and control units that serve as central hardware for vehicle-to-cloud communication, data collection, OTA management, and third-party application integration. These platforms are designed to operate across passenger and commercial vehicles, and they increasingly embed 5G and V2X capabilities to support smart connectivity and software-defined vehicle architectures. Their strengths lie in broad engineering scale, established supplier relationships, and deep integration experience across vehicle domains. For automakers, these platforms reduce integration risk because they come from suppliers with proven automotive validation pipelines and broad service portfolios. The trade-off is that differentiation often comes from integration depth and reliability rather than sweeping architectural innovation, which places pressure on these players to keep pace with more aggressive consolidation trends.
Electronics and software-oriented manufacturers are pursuing a different strategic angle. Some are building connectivity solutions that combine telematics control with infotainment, cloud connectivity, and emerging communication modalities such as satellite support. Others are focusing on advanced 5G-based telematics and AI-enabled connectivity features for premium and luxury vehicles. A distinct segment of players is concentrating on safe, secure connectivity hardware and software stacks optimized for intelligent mobile computing platforms, emphasizing platform security and integration of connectivity control with broader vehicle operating environments. These entrants are often faster to adapt to emerging communication capabilities because their roadmaps are tightly coupled to software and connectivity innovation rather than traditional hardware cycles. Their strategic advantage is the ability to create platforms that feel modern and software-forward, appealing to automakers pursuing aggressive digital transformation and next-generation user experiences.
PW Consulting
The recent developments in the market illustrate how quickly these strategic positions are being tested. Technology unveilings at major events have highlighted next-generation connectivity platforms that compress functionality into tighter hardware footprints and emphasize advanced communication support. Partnerships are increasingly combining connectivity hardware with external technology partners to extend capability, particularly around non-terrestrial network support and cloud-connected telematics. Meanwhile, automakers are pushing centralization further by unveiling centralized compute platforms that consolidate connectivity functions alongside high-performance processing for electric and conventional vehicles. These moves signal that connectivity hardware is moving closer to the center of vehicle compute strategy, not just sitting alongside it. Standard-setting bodies are also actively advancing unified frameworks for digital keys, fleet management use cases, and broader connectivity interoperability, which is gradually reducing the fragmentation risk that has historically complicated global platform deployment.
The market is evolving along two simultaneous vectors. Integration is accelerating at the hardware level, as consolidation reduces size, weight, and complexity while increasing the strategic importance of the central connectivity compute node. At the same time, differentiation is widening in the software and services layer, where the ability to manage updates, telemetry, security, and third-party applications determines commercial value over the vehicle lifecycle. New entrants with strong software and connectivity expertise are gaining traction in premium and tech-forward segments, while established players are leaning on scale, integration breadth, and supplier relationships to defend their position. The most probable outcome is continued enterprise-level consolidation among platform suppliers, paired with a rich ecosystem of software, cloud, and service innovation layered on top of the core connectivity hardware.
Forward Outlook: Three Shifts That Will Define the Next Three to Five Years
The next few years will likely be shaped by three overlapping trends that turn connectivity platforms from communication components into core elements of vehicle value architecture. The first is the deepening integration of connectivity into centralized and zonal compute platforms. As automakers move toward unified compute environments, connectivity control units will increasingly sit at the center of vehicle data flow, OTA governance, and cloud-facing services. This will expand the role of connectivity hardware from enabling communication to enabling fleet intelligence, software monetization, and remote service orchestration. The commercial opportunity lies in platforms that can anchor these functions with reliable performance, strong security, and architecture flexibility that adapts as vehicle compute strategies evolve.
Worldwide Car Audio Head Units Market
The second trend is the widening reach of communication modalities beyond traditional cellular networks. Satellite-enabled telematics and broader communication support are beginning to complement terrestrial networks, especially for areas where continuous connectivity is critical or where network coverage is uneven. This is creating new use cases for fleet tracking, remote diagnostics, and service continuity, and it is pushing connectivity platforms to support a more diverse set of communication pathways. Platforms that can integrate multiple communication options without adding excessive complexity will have a clear advantage. The risk is that expanded communication support increases integration and certification complexity, particularly where standards across communication modalities and regional regulations are still maturing.
The third trend is the shift toward unified standards and secure digital access frameworks that reduce fragmentation and accelerate global deployment. As interoperability expectations grow around digital keys, V2X, and connected service access, platforms aligned with global standards will gain preference because they lower the cost and risk of cross-market rollout. This trend favors suppliers that can demonstrate both technical capability and compliance readiness. The uncertainty remains where regulatory timelines diverge and where cybersecurity expectations continue to evolve. Platforms that lag in security-by-design or lack a clear path to standard alignment will face increasing friction as the market matures and enterprise buyers demand more predictable compliance postures.
Telematics Control Unit (TCU) Market
Together, these trends point to a market where connectivity platforms become strategic assets for long-term vehicle value. The upside is significant: more capable platforms enable richer services, stronger fleet intelligence, and more resilient communication architectures. The risk lies in execution complexity, supply chain sensitivity, and the pace at which standards and security expectations become mandatory rather than aspirational.
Actionable Moves for Decision-Makers
Automakers and vehicle platform architects should treat connectivity control units as central architecture components rather than peripheral modules. Prioritizing integrated compute and connectivity platforms that support consolidated hardware, secure OTA governance, and flexible communication options will reduce long-term integration risk and better position vehicles for service monetization. Building validation and certification roadmaps around emerging unified standards will also shorten the path to global deployment and reduce region-by-region rework. Procurement teams should focus on platform suppliers that demonstrate supply resilience, security-by-design, and a clear path to forward-compatible chip and software roadmaps, since these attributes will determine how well a connectivity platform withstands disruption and scales over the vehicle lifecycle.
Investors and strategy teams should evaluate connectivity platform exposure through the lens of architecture centrality. The most durable commercial value will accrue to platforms that sit at the intersection of communication, software update, telemetry, and secure cloud connectivity, particularly as centralized compute becomes the norm. Companies that can combine hardware integration strength with fast-moving software and connectivity capabilities are well placed to capture value in premium and tech-forward segments, while established players with broad integration footprints remain attractive for scale deployment and standardization alignment. Portfolio decisions should weigh not just current platform capability but also the supplier's ability to adapt to one-board consolidation, multi-modal communication, and unified compliance expectations over the next several years.
The pace of change in connectivity architectures, communication modalities, and standards alignment makes detailed, segment-level intelligence a practical necessity rather than a nice-to-have. Decision-makers who need granular views by platform type, vehicle class, region, supplier positioning, and supply chain exposure will benefit from full research coverage that translates these dynamics into actionable planning data. Comprehensive research can help teams validate assumptions, compare supplier strategies, and map commercial opportunities against the market trajectory and regional nuances that shape deployment decisions.
For detailed analysis of this topic, please visit the official page: Worldwide Automotive Connectivity Control Unit Platform Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Worldwide RNA Cleanup Market: Why 8.85% CAGR and NGS Demand Redefine Growth
By pmarketresearch, 2026-09-18
Strategic Trends and Commercial Opportunities in the Global RNA Cleanup Market
Market Landscape and Core Challenges
The worldwide RNA cleanup market has grown substantially over the past five years, expanding from approximately USD 345.5 million in 2020 to USD 525.0 million in 2025. This trajectory reflects a compound annual growth rate of 8.85 percent, with projected revenue reaching USD 950.5 million by 2032. The sustained expansion underscores the critical role of RNA purification and cleanup in contemporary molecular biology, diagnostics, and therapeutic development. As downstream applications grow more demanding in terms of RNA integrity, purity, and throughput, the cleanup step has evolved from a routine laboratory procedure to a strategic component of workflow design.
Two structural challenges currently shape market dynamics. The first centers on supply chain fragility for essential consumables. Silica membranes and magnetic beads, which form the backbone of most commercial cleanup kits, are predominantly sourced from a concentrated set of manufacturers in China and Japan. In 2024, these core materials experienced delivery delays of up to twelve weeks as production capacity was redirected toward semiconductor applications. Such disruptions have forced end users to recalibrate experimental timelines, while reagent suppliers have had to manage inventory volatility and cost pass-through pressures, with certain RNA purification reagents seeing price increases of up to five hundred percent during peak demand periods tied to global testing surges.
The second challenge involves an increasingly complex regulatory environment. FDA and EMA guidance documents now emphasize stringent characterization of RNA integrity, purity, and physicochemical properties for therapeutic applications, including the cleanup processes themselves. Simultaneously, the EU Single-Use Plastics Directive requires vendors to transition RNA cleanup columns to recyclable polypropylene, extending product development cycles by up to nine months. These converging requirements elevate compliance costs and slow time-to-market for reformulated products, particularly for companies that must align research-grade offerings with emerging clinical-grade expectations.
PW Consulting
A third, more structural pressure relates to market concentration. The top three firms account for roughly forty-eight percent of revenue, while the top five capture nearly sixty-three percent. This concentration confers scale advantages to incumbent suppliers but also creates dependency risks for laboratories and manufacturers that rely on a limited set of validated consumables. For firms outside the leading tier, breaking into established procurement cycles requires differentiated performance claims, regulatory readiness, or workflow integration that transcends commodity pricing competition.
Key Drivers Shaping Market Trajectory
Several interconnected forces are driving the market toward higher value and more specialized offerings. Understanding these drivers clarifies where investment and product strategy should be directed.
Technological innovation in purification formats continues to reshape competitive positioning. Magnetic bead-based cleanup has gained substantial traction because it aligns naturally with automated liquid handling, reduces hands-on time, and supports scalable processing for high-throughput environments. Silica-based spin columns remain widely used for their reliability and low barrier to adoption, but the incremental advantage increasingly belongs to platforms that can deliver consistent recovery and inhibitor removal across varied input types. Recent product launches illustrate this shift, such as magnetic bead-based total RNA purification kits capable of automated, high-purity extraction in approximately fifteen minutes. These developments signal a market preference for speed, reproducibility, and compatibility with integrated instrumentation rather than standalone consumables alone.
Demand-side expansion from genomics and advanced transcriptomics is another major driver. Next-generation sequencing, in vitro transcription, and RT-PCR/qPCR applications represent the largest end-use categories, each imposing distinct requirements on RNA cleanup. NGS workflows demand high integrity and low contaminant carryover to protect library quality, while in vitro transcription applications require efficient removal of enzymes, nucleotides, and buffer components that can interfere with downstream reactions. The rise of spatial biology has further intensified these requirements. Recent portfolio updates extending RNA purification into spatial biology workflows, combined with collaborative efforts linking RNA purification elements to spatial transcriptomics solutions with major sequencing platforms, demonstrate how cleanup is being embedded into specialized, high-value applications rather than treated as a generic preparatory step.
Regulatory and quality expectations are raising the performance bar. For research-grade use, consistency and lot-to-lot reproducibility matter increasingly as experiments scale. For therapeutic and clinical contexts, regulators are focusing on RNA integrity, purity, and physicochemical characterization throughout the manufacturing chain. This is pushing suppliers to document process controls more rigorously and, in some cases, move toward GMP-compliant raw materials and processes. The constraint is tangible: GMP-compliant raw materials for RNA-related processes face supply limitations that can restrict large-scale therapeutic manufacturing. Companies that can provide well-characterized, compliant inputs while maintaining scalability are positioned to capture premium segments of the market.
Cost structure and sourcing strategy are becoming strategic levers. The concentration of critical raw materials in a small number of geographies, combined with periodic demand spikes, has exposed vulnerability in the supply chain. Some reagent categories have experienced significant price volatility during peak periods, and delivery delays can cascade into research delays and clinical program slippage. In response, leading suppliers and large end users are exploring dual sourcing, inventory buffering, and workflow designs that reduce dependence on single consumable types. At the same time, regulatory mandates for recyclable materials add reformulation costs and extend development timelines. These pressures are compressing margins for undifferentiated products while rewarding suppliers that can balance performance, compliance, and reliable supply.
Competitive Landscape and Leading Strategies
The market features a mix of large, broadly positioned life science companies and specialized suppliers with strong technical reputations. Thermo Fisher Scientific and QIAGEN anchor the upper tier with comprehensive kit portfolios and strong integration into both manual and automated workflows. Thermo Fisher’s offerings span RNA cleanup and concentration for post-enzymatic reactions and in vitro transcription workflows, supported by magnetic bead-based systems designed for high-yield processing. QIAGEN’s RNeasy series, including cleanup kits that enable small elution volumes and inhibitor removal, is well established for total RNA and miRNA applications, with compatibility across manual and automated protocols.
Mid-tier and specialized firms compete on performance specificity, recovery claims, and workflow fit. New England Biolabs offers spin RNA cleanup kits in multiple binding capacities tailored to rapid silica-based cleanup after IVT, labeling, or enzymatic reactions, emphasizing high recovery and purity suitable for NGS and RT-qPCR. Zymo Research provides RNA clean and concentrator kits in multiple formats, including magnetic bead versions, targeting rapid cleanup, concentration, and inhibitor removal from diverse inputs. Norgen Biotek uses silicon carbide technology for phenol-free isolation and cleanup across RNA sizes, with options for high-throughput and cell-free RNA applications. Promega, Omega Bio-tek, Agilent, Roche, Merck KGaA, Takara Bio, and Bio-Rad each contribute differentiated positions, from automated system support and integrated nucleic acid purification to workflow-specific reagents tied to NGS and spatial transcriptomics.
Leading companies are pursuing three strategic directions. First, automation and throughput . Magnetic bead systems and kit formats that integrate with liquid handlers reduce variability and labor, which is increasingly valuable in screening, clinical labs, and process development environments. Second, workflow integration . Suppliers are aligning cleanup products with adjacent steps such as in vitro transcription, library preparation, and spatial biology, making the cleanup step part of a coherent solution rather than an isolated purchase. Recent collaboration and portfolio moves that connect RNA purification to spatial transcriptomics workflows illustrate this integration mindset. Third, regulatory readiness and material consistency . As therapeutic and diagnostic applications grow, suppliers that can provide documented purity, integrity, and process controls gain advantage in higher-stakes procurement decisions.
Cleaning Indicator Market
The competitive landscape is evolving through a combination of consolidation pressure and segmentation. Large incumbents benefit from broad distribution, established relationships, and the ability to bundle cleanup products with instrumentation and reagents. Specialized players can compete by targeting high-recovery claims, niche input types, or specific workflow constraints such as extremely low elution volumes or inhibitor-rich samples. Market entry is possible but challenging because validation cycles in laboratory and clinical settings are long, and switching costs rise when cleanup performance is linked to downstream assay reliability. Over time, expect further consolidation among mid-tier suppliers, alongside continued differentiation by application-specific performance and automation compatibility.
Future Trends and Commercial Implications
Several trends are likely to define the market over the next three to five years.
Automation-compatible, high-recovery formats will become the default expectation for many end users. Magnetic bead-based approaches and kit designs that minimize hands-on time, standardize elution volumes, and integrate with robotic workflows will see continued adoption, particularly in high-throughput genomics and diagnostics. Commercial opportunity lies in pairing consumables with instrument compatibility, application-specific protocols, and validated performance claims that reduce user optimization time.
Application specialization will deepen. As spatial transcriptomics, advanced in vitro transcription, and NGS-based workflows expand, cleanup requirements will diverge by application. Suppliers that tailor binding capacity, inhibitor removal, and recovery profiles to specific downstream processes can command stronger positioning than those offering generic solutions. This creates room for targeted product development and partnership strategies that embed cleanup into broader workflow ecosystems.
Regulatory and sustainability requirements will reshape product roadmaps. Stricter RNA characterization expectations for therapeutic use and directives pushing recyclable materials will extend development cycles and increase compliance costs. Firms that proactively invest in reformulated consumables, well-characterized raw materials, and documentation suitable for clinical and GMP-adjacent contexts will be better placed to participate in higher-value segments. The risk is that these same requirements can slow innovation pace and raise barriers for smaller players, potentially accelerating concentration among suppliers with stronger regulatory and manufacturing capabilities.
Underlying uncertainties include raw material availability, geopolitical sourcing risks, and the pace at which therapeutic RNA programs scale their manufacturing needs. Price volatility in key reagents and periodic supply constraints can disrupt both research timelines and commercialization schedules. Companies should therefore weigh performance advantages against supply resilience and compliance readiness when evaluating long-term positioning.
Oligonucleotide Purification Market
Actionable Guidance for Decision Makers
Strategic responses should be tailored to each stakeholder’s role in the value chain.
- For manufacturers and suppliers: Prioritize automation-compatible formats and application-specific performance claims, while investing in regulatory documentation and sustainable material transitions. Diversify sourcing for critical components such as silica membranes and magnetic beads to reduce exposure to delivery delays and price spikes. Where feasible, embed cleanup products into broader workflow solutions to increase switching costs and reinforce value beyond unit pricing.
- For investors: Focus on companies with differentiated purification technologies, credible recovery and purity data, and the operational capacity to support automation and compliance demands. Evaluate exposure to raw material concentration risk and assess whether portfolio integration, partnerships, or scale advantages provide durable moats in a market where validation cycles are long and procurement is sticky.
- For procurement and laboratory leaders: Treat RNA cleanup as a workflow-critical input rather than a commodity. Build evaluation criteria around recovery consistency, inhibitor removal, elution volume control, and compatibility with automation or downstream applications. Strengthen supply continuity through dual sourcing, safety stock for critical consumables, and supplier qualification that accounts for regulatory trajectory and material sustainability requirements.
The strategic stakes in this market are rising as cleanup moves closer to high-value applications and more stringent quality expectations. Detailed segment-level data, supplier benchmarking, and tailored scenario analysis can sharpen planning and reduce execution risk. For teams seeking deeper granularity on regional dynamics, methodology splits, application-specific demand patterns, and competitive positioning, the full PW Consulting report provides a comprehensive foundation for decision-making and customized recommendations.
For detailed analysis of this topic, please visit the official page: Worldwide RNA Cleanup Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Worldwide Lung Cancer Test Kit Market: 8.2% CAGR and 2026 Growth Drivers
By pmarketresearch, 2026-09-18
Global Lung Cancer Test Kit Market: Strategic Trends and Commercial Opportunities Through 2032
Market Overview: Navigating Growth Amid Structural Challenges
The global lung cancer diagnostic testing market has demonstrated sustained expansion, valued at approximately $2.15 billion in 2025 and projected to reach $3.73 billion by 2032, reflecting a compound annual growth rate of 8.2 percent. This trajectory underscores a sector transitioning from established diagnostic paradigms toward increasingly sophisticated, molecular-driven testing frameworks. Historical performance from 2020 through 2025 reveals consistent upward momentum, with revenues climbing from $1.45 billion to the current valuation, driven by rising incidence rates, expanded screening eligibility, and the proliferation of targeted therapy pipelines. The forecast horizon through 2032 suggests that this growth will not merely continue but accelerate as diagnostic workflows become more integrated with clinical decision-making pathways.
Despite the favorable macroeconomic indicators, the industry confronts several structural inflection points that will define competitive positioning in the coming years. First, the regulatory landscape remains fragmented across jurisdictions, creating uneven market access for innovative assays. While certain companion diagnostics have secured formal clearance in major markets, others operate within laboratory-developed test frameworks that face increasing scrutiny regarding standardization and reimbursement alignment. This duality creates a bifurcated commercial environment where speed-to-market advantages must be carefully balanced against long-term regulatory sustainability.
Second, the market exhibits moderate concentration dynamics, with the top three participants collectively commanding roughly 48 percent of total revenue and the top five firms controlling approximately 62 percent. This structure provides scale advantages to established players in manufacturing, distribution, and clinical validation, yet simultaneously leaves substantial whitespace for specialized innovators who can address unmet needs in early detection, minimal residual disease monitoring, or niche molecular subsets. The concentration pattern suggests that consolidation will likely continue, but targeted acquisitions of clinically differentiated technologies may prove more valuable than broad portfolio expansion.
Worldwide In Vitro Lung Model Market
Third, reimbursement frameworks are evolving but remain inconsistent, particularly for non-invasive or multi-analyte testing approaches that fall outside traditional coding structures. While certain screening programs have established coverage pathways, the translation of diagnostic innovation into sustainable commercial adoption depends heavily on demonstrating clinical utility that aligns with payer expectations. Organizations that proactively engage with health economics evidence generation and real-world data collection will be better positioned to navigate this complexity.
Key Drivers Reshaping the Competitive Landscape
Technological Innovation and the Shift Toward Multi-Analyte Profiling
The most pronounced driver of market evolution is the rapid advancement in molecular diagnostics, which has transitioned from single-gene mutation detection to comprehensive genomic profiling and multi-modal testing strategies. Next-generation sequencing platforms now enable simultaneous analysis of multiple actionable variants, reducing turnaround times and improving the probability of identifying targetable alterations in non-small cell lung cancer patients. This technological maturation is not merely an incremental improvement; it fundamentally alters the clinical value proposition of testing by expanding the addressable patient population and supporting sequential therapy selection as resistance mechanisms emerge.
Recent regulatory milestones illustrate how innovation translates into commercial viability. The approval of next-generation sequencing-based companion diagnostics for specific epidermal growth factor receptor exon 20 insertion mutations demonstrates how assay development increasingly aligns with precision oncology drug pipelines. Similarly, artificial intelligence-enhanced computational pathology tools have received breakthrough device designations, signaling a broader industry shift toward digital and algorithmic augmentation of traditional tissue-based diagnostics. These developments suggest that future competitive advantage will depend less on proprietary single-test formats and more on integrated diagnostic ecosystems that combine molecular, immunohistochemical, and imaging-based insights.
Regulatory Evolution and Companion Diagnostic Integration
Regulatory frameworks are increasingly converging around the principle that diagnostic tests must be developed in tandem with therapeutic candidates, particularly in oncology where biomarker-driven patient stratification directly influences treatment efficacy. Multiple next-generation sequencing and polymerase chain reaction-based assays have received formal clearance or approval as companion diagnostics with specific claims tied to targeted therapy indications. This regulatory normalization reduces uncertainty for manufacturers and healthcare providers, but it also raises the barrier to entry for novel formats that lack established clinical validation pathways.
At the same time, laboratory-developed tests continue to play a critical role in filling gaps where commercial assays have not yet secured formal clearance. Tests utilizing flow cytometry-based sputum analysis or DNA methylation detection from non-invasive sample types illustrate how innovators are pursuing alternative biological matrices to address early detection and high-risk population screening. The coexistence of cleared companion diagnostics and laboratory-developed offerings creates a dynamic where reimbursement strategy, clinical evidence standards, and laboratory accreditation requirements become decisive commercial factors rather than secondary considerations.
Demand-Side Shifts Driven by Screening Expansion and Precision Medicine Adoption
Demand dynamics are being reshaped by two interrelated forces: expanded eligibility for lung cancer screening and the growing expectation that diagnostic testing should inform personalized treatment pathways. Low-dose computed tomography screening programs have established coverage for eligible beneficiaries within specified age and smoking history parameters, supported by specific procedural coding for both the imaging scan and the accompanying shared decision-making consultation. This structured reimbursement environment encourages broader screening uptake, which in turn generates downstream demand for confirmatory and molecular diagnostic testing when suspicious findings are identified.
PW Consulting
Beyond screening, the clinical momentum behind precision oncology continues to drive demand for comprehensive biomarker assessment at the time of diagnosis and throughout the treatment continuum. Oncology practices increasingly expect testing solutions that can detect not only established mutations but also emerging resistance alterations and co-occurring genomic events that may influence therapeutic sequencing. This expectation places pressure on manufacturers to deliver assays with broad analytical ranges, robust performance across varied specimen types, and compatibility with existing laboratory workflows. End users ranging from large hospital systems to specialized diagnostic laboratories are prioritizing solutions that minimize sample consumption, reduce hands-on time, and provide clear interpretive reporting that supports clinical actionability.
Circulating Tumor Cells Market
Supply Chain Dynamics and the Pursuit of Cost-Effective Scalability
Cost structures and supply chain resilience have emerged as increasingly important considerations, particularly as testing volumes expand and laboratories seek to manage per-test economics without compromising analytical quality. The shift toward automated sample preparation, standardized reagent formats, and integrated instrumentation reduces variability and labor intensity, but it also requires upfront capital investment and vendor lock-in considerations. Organizations that can offer scalable platforms with flexible throughput options will find stronger adoption in settings where testing demand fluctuates across regions or clinical programs.
Additionally, the geographic distribution of manufacturing and distribution capabilities influences market access, regulatory compliance, and time-to-result performance. Companies with established global operations benefit from diversified supply networks and deeper relationships with centralized testing facilities, while regional players may gain advantage by tailoring solutions to local regulatory requirements, sample logistics, and reimbursement environments. The interplay between centralized high-complexity testing and decentralized point-of-care or regional laboratory models will continue to shape how testing capacity is deployed and how commercial value is captured.
Competitive Dynamics and Strategic Positioning
The competitive environment reflects a blend of large diversified diagnostics organizations, focused molecular testing specialists, and emerging entrants pursuing novel detection modalities. Leading firms have secured positions by aligning their assay portfolios with high-prevalence biomarker targets and by securing regulatory clearances that facilitate integration into standard oncology workflows. For example, established manufacturers offer companion diagnostic assays for epidermal growth factor receptor mutation testing and programmed death-ligand 1 immunohistochemistry, both of which remain foundational to non-small cell lung cancer patient stratification. These products benefit from extensive clinical validation datasets, established ordering patterns, and integration with broader instrumentation ecosystems.
Other major participants have emphasized comprehensive genomic profiling through tissue and liquid biopsy formats, positioning their offerings as tools for broad biomarker discovery rather than single-target detection. This strategy supports clinical scenarios where multiple therapeutic options may be relevant or where tissue availability is limited. By expanding claims across several targeted therapies, these comprehensive tests seek to become default testing options at diagnosis, creating stickiness through breadth of coverage and compatibility with evolving treatment guidelines.
Smaller and mid-sized companies are pursuing differentiation through specialized technologies or alternative sample types. Next-generation sequencing kit developers are focusing on streamlined workflows and targeted panels that balance breadth with cost efficiency. Flow cytometry-based sputum tests and DNA methylation assays derived from urine or blood represent efforts to capture early detection opportunities and to serve populations where invasive sampling is less feasible. While some of these approaches operate within laboratory-developed test frameworks rather than cleared companion diagnostic pathways, they reflect a broader industry recognition that early detection and minimal residual disease monitoring represent substantial unmet needs.
Strategic positioning among leading organizations tends to cluster around three models. The first emphasizes platform breadth and regulatory clearance volume, leveraging scale to maintain visibility across multiple biomarker domains. The second focuses on deep clinical evidence generation and guideline alignment, ensuring that specific assays are embedded in recommended testing algorithms. The third pursues technological differentiation through artificial intelligence integration, novel sample types, or workflow automation that reduces laboratory burden. Each model carries distinct risk-reward profiles: platform breadth supports cross-selling and resilience but may dilute focus; evidence-driven positioning builds clinical credibility but requires sustained investment; technological differentiation can create temporary monopolies but faces rapid replication risk.
Market evolution is likely to feature continued consolidation among scaled players seeking to acquire differentiated technologies, alongside selective partnerships between assay developers and pharmaceutical companies to co-develop companion diagnostics alongside new therapeutic candidates. Geographic expansion will remain uneven, with regions that have established screening infrastructure and reimbursement clarity attracting more rapid adoption. New entrants will need to demonstrate not only analytical performance but also clear pathways to reimbursement, laboratory adoption, and clinical guideline inclusion to achieve commercial traction.
Future Outlook: Key Trends and Strategic Implications
Over the next three to five years, several trends will likely define the market trajectory. First, multi-analyte and multi-modal testing will become increasingly standard, as clinicians seek consolidated insights that combine genomic, proteomic, and imaging-derived data. This convergence will pressure manufacturers to develop interoperable reporting formats and to demonstrate that integrated testing improves decision-making efficiency or patient outcomes compared with sequential single-test approaches. Organizations that invest early in data integration frameworks and interpretive software may capture disproportionate value as laboratories consolidate testing workflows.
Second, artificial intelligence and computational pathology will move from regulatory novelty to operational expectation, particularly in screening triage and tissue analysis. AI-assisted interpretation tools have already received notable regulatory designations, and their adoption will likely accelerate as laboratories face workforce constraints and rising sample volumes. The commercial opportunity lies not only in the software itself but in the broader ecosystem of training, validation, and quality assurance services that accompany deployment. Companies that can provide end-to-end implementation support, including local adaptation and performance monitoring, will differentiate beyond pure algorithm accuracy.
Third, non-invasive and liquid-based testing formats will continue to gain relevance, especially for early detection, treatment monitoring, and scenarios where tissue procurement is challenging. While cleared companion diagnostics will remain essential for therapy selection, the growth of laboratory-developed and minimally invasive options reflects demand for broader access and repeated sampling capabilities. The strategic risk involves variable reimbursement coverage and the need to generate robust clinical utility evidence that satisfies both payer and guideline-setting bodies. Firms that can bridge the gap between innovative sample types and established evidentiary standards will be best positioned to convert technological promise into sustainable revenue.
Potential uncertainties include regulatory shifts affecting laboratory-developed test oversight, changes in screening eligibility or reimbursement policies, and the pace at which novel biomarkers translate into routine clinical practice. Competitive intensity may also compress margins as platforms mature and differentiation narrows. These risks do not diminish the overall growth outlook but emphasize the importance of strategic agility and evidence-driven commercial planning.
Actionable Guidance for Decision Makers
For diagnostic manufacturers, the priority should be to align product development with emerging clinical workflows rather than pursuing isolated technical advances. This means investing in interpretive reporting, workflow integration, and evidence generation that supports both regulatory clearance and payer acceptance. Partnerships with academic centers and community oncology networks can accelerate real-world data collection and strengthen guideline inclusion prospects. Companies should also evaluate whether their portfolio strategy favors breadth across biomarkers or depth in specific high-value niches, recognizing that the optimal choice depends on manufacturing capabilities, regulatory expertise, and target end-user profiles.
For investors, due diligence should extend beyond assay performance claims to include reimbursement pathway viability, laboratory adoption economics, and the sustainability of competitive moats. Technologies with clear companion diagnostic alignment or strong biomarker-therapy linkage typically offer more predictable adoption curves, while early detection and multi-cancer approaches may offer higher upside but require longer evidence-building horizons. Evaluating management teams on their ability to navigate regulatory transitions and to build commercial infrastructure in key regions can provide early signals of execution risk or advantage.
For procurement leaders and laboratory operators, sourcing decisions should weigh total cost of ownership against clinical utility and future-proofing potential. Platforms that can accommodate evolving biomarker panels, integrate with existing information systems, and support both high-complexity and decentralized testing models will reduce the risk of premature obsolescence. Establishing performance monitoring protocols and participating in multi-site validation studies can also strengthen negotiating positions and ensure that purchased solutions remain aligned with changing clinical guidelines.
The complexity of this market underscores the value of access to granular segmentation data, regional reimbursement maps, and company-level competitive benchmarking. Detailed research that breaks down technology adoption curves, end-user procurement patterns, and regulatory status tracking can inform more precise entry timing, pricing strategy, and partnership targeting. For organizations seeking to translate these strategic themes into operational decisions, comprehensive market intelligence remains a critical enabler of disciplined execution.
For detailed analysis of this topic, please visit the official page: Worldwide Lung Cancer Test Kit Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Worldwide Infrastructure as a Service Market: The 21% CAGR and Concentration Shift
By pmarketresearch, 2026-09-18
The Infrastructure as a Service Revolution: Navigating Trillion-Dollar Scale and Strategic Complexity
Market Landscape and Core Challenges
The worldwide Infrastructure as a Service (IaaS) market has entered a phase of unprecedented expansion, fundamentally altering how organizations procure and manage computing resources. From a base valuation in the early 2020s, the sector has demonstrated resilience and accelerating growth, driven by the irreplaceable role cloud infrastructure now plays in digital transformation. The trajectory suggests a market moving beyond early adoption curves into a mature, high-velocity phase where scale brings both opportunity and structural friction. Growth rates indicate that the sector is compounding at a pace that outstrips many traditional technology segments, signaling that IaaS is no longer a supporting utility but a primary engine of enterprise value creation.
Despite the broad upward momentum, the industry faces three critical inflection points that will define competitive outcomes over the next several years. First, concentration risk remains pronounced. A small group of hyperscale providers commands a dominant share of global revenue, creating a landscape where customer leverage is asymmetrical and switching costs remain high. This concentration creates vulnerability for enterprises reliant on single-vendor strategies, while simultaneously raising antitrust and regulatory scrutiny in multiple jurisdictions. The market structure rewards scale, but it also invites challenges around interoperability and vendor lock-in that are becoming harder for buyers to ignore.
Second, the energy and physical infrastructure bottleneck is transitioning from a background concern to an active constraint on capacity planning. The rapid proliferation of AI-driven workloads has pushed data center power demand into new territory, straining regional grids and altering the economics of site selection. Where cloud expansion was once limited primarily by capital and fiber availability, it is now increasingly bound by electrical capacity, cooling technology, and local permitting timelines. For providers, this means that growth trajectories must be recalibrated against grid reality. For enterprises, it introduces volatility in availability and long-term pricing assumptions that rarely appear in standard procurement models.
Worldwide WiFi as a Service Market
Third, the regulatory environment is fragmenting in ways that complicate global deployment strategies. Data sovereignty requirements, cybersecurity mandates, and contractual fairness regulations are no longer confined to specific sectors or geographies. They are becoming baseline expectations for any organization operating across borders. Compliance is shifting from a legal checkbox to an architectural consideration, influencing how workloads are distributed, how data is stored, and how providers are evaluated. The market is adapting, but the pace of regulatory change continues to outpace the standardization of cloud governance practices across many enterprise portfolios.
Key Drivers Shaping Market Dynamics
The momentum in IaaS is being propelled by a convergence of technological, regulatory, and structural forces that reinforce one another. Understanding these drivers is essential for any organization planning multi-year infrastructure roadmaps, as each factor carries distinct implications for sourcing strategy, risk management, and innovation velocity.
Technological Innovation and AI-Optimized Infrastructure
The most transformative driver is the integration of advanced artificial intelligence capabilities directly into infrastructure offerings. Cloud providers are no longer simply offering raw compute, storage, and networking in isolation. They are designing optimized stacks that reduce the friction between infrastructure provisioning and AI workload execution. This includes purpose-built acceleration architectures, high-bandwidth interconnect fabrics, and managed orchestration layers that simplify deployment of training and inference pipelines. The result is a market where infrastructure differentiation is increasingly defined by how efficiently a platform can support machine learning lifecycles, not just by aggregate capacity.
This shift has practical consequences for procurement and architecture decisions. Workloads that previously required significant customization on general-purpose infrastructure can now be deployed on platforms with built-in optimization for specific AI patterns. At the same time, the growing share of inference workloads relative to training is reshaping demand profiles. Inference tends to be more distributed, latency-sensitive, and cost-sensitive, which encourages providers to invest in edge-adjacent capacity and more granular pricing mechanisms. Organizations that treat IaaS as a static commodity risk overlooking these architectural shifts and paying a premium for misaligned resource allocation.
Regulatory and Policy Evolution
Policy frameworks are becoming a central determinant of cloud strategy rather than a peripheral compliance concern. In multiple regions, regulators are acting on the premise that cloud infrastructure is critical economic infrastructure and must be governed accordingly. New rules are targeting contractual flexibility, data portability, cybersecurity responsibility, and transparency in service relationships. These measures are designed to reduce switching friction and increase accountability, but they also raise the operational bar for both providers and enterprise buyers.
For multinational organizations, this regulatory fragmentation introduces complexity in workload placement and vendor evaluation. Data residency expectations, sector-specific security obligations, and emerging contractual fairness requirements mean that a single global architecture rarely satisfies all constraints without deliberate design. Providers that can demonstrate localized compliance capabilities, clear data handling policies, and auditable governance structures are gaining an advantage in regulated sectors. The regulatory trend is not simply a constraint; it is also a filter that rewards providers with mature governance postures and penalizes those that rely on ambiguous terms or opaque data practices.
Enterprise Demand Shifts and Operational Priorities
On the demand side, enterprises are moving from experimentation to operational dependence. Cloud infrastructure now underpins core business processes across industries, and the question for many organizations is no longer whether to use IaaS but how to optimize its use at scale. This maturation is changing buying behavior. Procurement teams are increasingly focused on total cost of ownership rather than headline pricing, factoring in network egress, storage tiering, support models, and the hidden costs of integration and governance.
There is also a growing appetite for hybrid and multi-environment strategies, driven by the need to balance performance, sovereignty, and resilience. Organizations want the elasticity of public IaaS without sacrificing control over sensitive workloads or critical data flows. This is encouraging providers to invest in hybrid connectivity, consistent management planes, and interoperability features that reduce the operational divide between environments. At the same time, demand is becoming more segmented. Large enterprises with complex regulatory footprints have different priorities than startups optimizing for speed and simplicity, and the most successful providers are building distinct value propositions for each segment rather than relying on one-size-fits-all messaging.
Supply-Side Pressures and Cost Structure Evolution
The supply side of IaaS is undergoing a structural recalibration as physical constraints and input costs reshape expansion economics. Energy intensity is one of the most visible pressure points. As demand concentrates in power-heavy workloads, providers must secure long-term energy access, invest in efficiency improvements, and navigate regional grid limitations. These factors influence not only where new capacity can be added but also the cost trajectory of existing facilities. In markets where data center growth contributes materially to local electricity demand, pricing dynamics and community pushback can slow deployment timelines and raise operating expenses.
The implication is that IaaS cost structures are becoming more regionally differentiated. Providers with advantaged energy access, efficient cooling designs, and strong site selection capabilities can sustain more favorable economics, while capacity in constrained regions may carry higher premiums. This differentiation is beginning to surface in enterprise planning, where latency, compliance, and energy-related cost risk are weighed alongside raw performance. Over time, the market is likely to reward providers that can integrate energy strategy into their infrastructure roadmap as deliberately as they integrate compute and storage innovation.
Competitive Landscape and Emerging Strategic Postures
The competitive environment in IaaS is defined by a tension between scale dominance and targeted differentiation. A handful of hyperscale platforms continue to set the pace on global reach, service breadth, and investment capacity. Their advantage lies in the ability to amortize infrastructure costs across enormous workloads, sustain aggressive R&D programs, and offer ecosystems that extend well beyond raw infrastructure. For many enterprises, these platforms remain the default starting point because of their maturity, integrated tooling, and broad partner networks.
Yet scale alone is no longer a complete answer to every buyer need. Competitive pressure is increasing from multiple directions. Enterprise-focused providers are carving out positions around specialized workloads, particularly those requiring high-performance database execution, mission-critical reliability, or stringent regulatory alignment. Their strategy often centers on predictable performance, transparent pricing, and deep integration with existing enterprise software stacks. By emphasizing use cases where general-purpose hyperscale offerings may be less efficient, these players are building credible alternatives for specific procurement decisions.
Regional and sovereignty-oriented providers are also gaining relevance. In markets where data locality, regulatory alignment, and customer trust are paramount, providers that can demonstrate local governance, predictable compliance posture, and clear data handling practices are winning consideration even when global incumbents offer lower headline pricing. This is not simply a political preference; it reflects operational reality. Organizations facing audits, cross-border restrictions, or sector-specific security obligations often prioritize verifiable control over marginal cost savings. The emergence of strong regional players therefore adds genuine choice and reduces the effective lock-in risk that once characterized the market.
Developer-centric and managed service providers illustrate another dimension of competition. Some platforms focus on simplicity, rapid deployment, and predictable developer experience, targeting smaller enterprises and fast-moving product teams. Others operate as managed intermediaries, helping customers navigate multi-platform environments, optimize operations, and reduce the internal burden of infrastructure management. These models do not replace hyperscale infrastructure; they layer value on top of it. Their growth signals that many organizations are willing to pay for expertise, simplification, and operational relief, especially when internal cloud maturity is still maturing.
The competitive trajectory appears to be moving toward a more layered market. A small group of providers will continue to dominate aggregate share, but meaningful differentiation is increasingly occurring at the edges: in AI-optimized stacks, in regulated-industry credibility, in regional sovereignty positioning, and in managed operating models. Market consolidation is likely to continue in areas where scale economics are decisive, but fragmentation will persist where specialized trust, performance, or operational needs create room for distinct value propositions. For buyers, the practical implication is that sourcing decisions should be workload-specific and strategy-aligned rather than driven by a single provider relationship.
PW Consulting
Future Trends and Commercial Implications
Looking ahead, three trends are likely to shape the IaaS market over the next several years, and each carries direct commercial implications.
Worldwide IT Infrastructure Outsourcing Service Market
The first is the deepening entanglement of AI workloads with infrastructure economics. As inference becomes a larger share of demand and AI adoption spreads beyond experimental teams into production operations, providers will continue to refine platforms that make AI deployment more efficient and predictable. Enterprises that align their infrastructure strategy with these optimized stacks can reduce implementation friction and improve unit economics for intelligent applications. The risk is that organizations chase AI capability without a clear workload strategy, leading to fragmented spend and underutilized capacity. The opportunity belongs to those who map AI demand to specific infrastructure patterns and select platforms accordingly.
The second trend is the institutionalization of compliance and sovereignty as architectural requirements. Regulatory expectations will likely continue to expand in scope and enforcement rigor, especially where critical infrastructure, personal data, and cross-border transfers intersect. This will favor providers that can offer clear data residency options, auditable governance, and consistent policy enforcement across regions. For enterprises, the strategic lesson is that compliance must be designed into the cloud architecture early, not retrofitted after deployment. Organizations that build governance into their sourcing model will move faster and with less rework as regulatory pressure intensifies.
The third trend is the growing importance of energy-aware infrastructure planning. Power availability, efficiency, and cost will increasingly influence where workloads run and how providers price capacity over time. Enterprises with large, predictable footprints should anticipate greater regional variation in availability and cost, and plan accordingly. This may mean diversifying deployment footprints, factoring energy risk into long-term agreements, or selecting providers with demonstrable efficiency and site-strategy discipline. The uncertainty here is meaningful: grid constraints, local policy responses, and energy price volatility can change the economics of a region faster than contract cycles anticipate.
Strategic Recommendations for Decision Makers
For enterprises, investors, and procurement leaders, the central task is to treat IaaS as a strategic variable rather than a background utility. The following actions can help translate market dynamics into measured advantage.
- Align infrastructure sourcing with workload profiles. Not every workload benefits from the same platform. Map compute, storage, and networking needs against performance, compliance, and cost requirements, and evaluate providers on the basis of specific use cases rather than overall brand scale.
- Build multi-vendor and hybrid literacy internally. Dependence on a single provider creates speed in the short term but fragility over time. Developing architecture, governance, and operational skills across environments reduces lock-in risk and improves negotiating leverage.
- Integrate compliance, energy risk, and total cost into procurement models. Pricing alone is insufficient for long-term decisions. Include data residency requirements, security obligations, egress behavior, support economics, and energy-related availability risk in sourcing evaluations to avoid hidden downside.
The pace of change in IaaS means that organizations with current, granular intelligence have a real advantage in timing, negotiation, and architecture design. Detailed segmentation, regional cost dynamics, provider-specific positioning, and scenario analysis can materially improve strategic choices. For decision makers who need a more complete picture of where value is concentrating and where risk is accumulating, the full PW Consulting research report provides expanded data, deeper segmentation, and tailored guidance for specific operating contexts.
For detailed analysis of this topic, please visit the official page: Worldwide Infrastructure as a Service Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
In-Car Infotainment Market: The 10.21% CAGR Shift Reshaping Global Competition
By pmarketresearch, 2026-09-18
Navigating the Global In-Car Infotainment Market: Strategic Trends and Commercial Opportunities (2025–2032)
Market Reality and Core Challenges
The worldwide in-car infotainment sector has transitioned from a niche convenience feature into a central pillar of automotive value creation. Market valuation expanded from approximately 21.45 billion USD in 2020 to 33.62 billion USD in 2025, reflecting sustained demand for connected, software-defined cabins. The growth trajectory remains robust, with a compound annual growth rate of 10.21 percent projected across the 2026 to 2032 forecast window. By 2032, the market is expected to surpass 66 billion USD. This expansion is driven by the convergence of consumer expectations for seamless digital experiences and OEMs' strategic push to monetize connected services over the vehicle lifecycle.
Despite this momentum, the industry stands at a critical inflection point. First, software complexity is outpacing hardware delivery cycles. Modern digital cockpits require continuous over-the-air updates, integration of third-party applications, and real-time data synchronization across domains. The shift from static, hardware-bound systems to cloud-connected software architectures introduces new validation burdens, cybersecurity requirements, and lifecycle management costs that traditional automotive suppliers are still adapting to. Second, data privacy and regulatory scrutiny are fundamentally reshaping how infotainment platforms collect, process, and monetize user information. Vehicle operators and technology providers can no longer treat cabin data as an open pipeline for feature personalization or subscription upselling without explicit consent mechanisms and transparent data governance. Third, the supply chain for advanced connectivity components remains constrained by cost volatility and infrastructure dependencies. Sourcing automotive-grade communication modules and ensuring reliable network coverage for real-time services requires coordinated investment across semiconductor suppliers, OEMs, and telecom infrastructure providers.
Worldwide Car Audio Head Units Market
For decision-makers, the immediate implication is clear. Infotainment is no longer a component purchase decision; it is a platform strategy decision. Companies that approach cabin technology as a static specification will face margin compression and slower feature adoption, while those that design for software lifecycle flexibility, regulatory compliance, and multi-vendor interoperability will capture the majority of incremental value.
Key Growth Drivers Reshaping the Sector
Technology Innovation and Architectural Shifts
The most consequential driver of market expansion is the migration toward centralized, high-performance computing architectures that separate application layers from underlying hardware. This approach enables OEMs to deploy new infotainment features, voice assistants, and context-aware services without requiring full hardware replacements. The industry is witnessing software extensions and AI-ready platforms designed to retrofit advanced cockpit functions onto existing vehicle systems. At the same time, operating system partnerships are reducing integration friction. Collaborations between chipset providers and software ecosystems are streamlining Android-based update cycles and enabling AI-powered mobility features directly within infotainment environments. These developments shorten time-to-market for new cabin experiences and lower the technical barrier for tier-one suppliers to deliver differentiated user interfaces. The practical takeaway is that hardware specifications alone no longer define competitive advantage. The ability to layer new software capabilities onto established hardware bases, while maintaining stability and security, is becoming a primary differentiator.
Regulatory Environment and Data Governance
Policy dynamics are actively restructuring how infotainment systems handle location data, driver behavior telemetry, and personalized services. Regulatory actions in 2026 have established stronger boundaries around vehicle data disclosure and consent. Settlements and enforcement patterns now require clearer user consent for data collection, restrictions on sharing behavioral and geolocation information with third-party consumer reporting entities, and greater transparency around subscription-linked data usage. Privacy regulation across multiple jurisdictions is accelerating, with state-level rules and aggressive oversight extending into telematics, connected navigation, and personalized cabin experiences. Simultaneously, spectrum and connectivity policy updates are expanding the backbone that supports vehicle-to-network services, indirectly strengthening the reliability of streaming, real-time map updates, and cloud-based infotainment features. For OEMs and technology providers, compliance is no longer a legal checkbox; it is a product design constraint. Systems must be architected with granular consent flows, data minimization principles, and auditable data handling from inception rather than retrofitted after launch.
Demand-Side Shifts in Consumer and Fleet Behavior
End-user expectations are pulling the market toward richer, more integrated cabin experiences. Drivers increasingly treat the vehicle interior as an extension of their digital ecosystem, expecting familiar application experiences, voice-controlled interaction, seamless smartphone integration, and context-aware display behavior. At the same time, fleet operators and commercial vehicle buyers are prioritizing connected telematics, route intelligence, and cabin interfaces that support driver productivity and safety. The commercial demand for connected infotainment is not purely consumer-facing. Fleet managers are recognizing that unified cockpit platforms can reduce downtime, support diagnostic feedback loops, and improve operator satisfaction. This dual demand structure broadens the addressable market beyond passenger vehicles and encourages suppliers to design modular platforms that can scale across segments. The strategic implication is that infotainment differentiation will increasingly be measured by user retention, service adoption, and integration depth rather than screen size or audio fidelity alone.
Supply Chain and Cost Structure Evolution
Cost architecture is being redefined by the pricing and integration of advanced connectivity components. Automotive-grade 5G modules for connected infotainment and telematics control units sit within a meaningful cost range, and fully integrated 5G-enabled units vary substantially depending on feature depth and integration complexity. Roadside infrastructure for connected vehicle ecosystems also carries deployment costs that influence total system economics. These cost dynamics create a strategic tradeoff. Manufacturers must balance the value of richer connectivity against per-unit bill-of-materials pressure and infrastructure readiness in target markets. The market response has been a gradual move toward scalable hardware tiers, selective adoption of high-bandwidth features in premium segments, and platform designs that can accommodate mid-tier connectivity without fragmenting software development. For procurement and engineering leaders, the priority is to avoid over-specifying connectivity across the entire lineup while preserving the architectural flexibility to upscale features where network coverage and consumer willingness to pay justify the investment.
Competitive Landscape and Leading Strategies
The competitive field is shaped by large multinational suppliers and technology integrators, each pursuing distinct strategic positions. Harman International, operating under Samsung, has built a strong footprint in premium connected infotainment, digital cockpit platforms, Android Automotive integration, and branded audio systems. Its value proposition centers on combining consumer-electronics sensibility with automotive-grade reliability, allowing OEMs to deliver familiar, high-quality cabin experiences. Robert Bosch GmbH competes through integrated cockpit solutions that merge navigation, connectivity, voice control, driver assistance, and AI-enabled cockpit functions. Bosch's strength lies in systems-level integration, which reduces interface fragmentation and supports unified development across driving and cabin domains. Continental AG focuses on smart vehicle architectures, digital cockpit platforms, connectivity frameworks, and supporting features for autonomous functions and biometric interaction. Its positioning emphasizes scalable architecture that can evolve with software-defined vehicle strategies. Denso Corporation maintains a strong presence through infotainment and telematics solutions oriented around user experience, safety, intelligent interfaces, and broad OEM supply relationships. Its advantage is rooted in deep automotive supply integration and a focus on dependable, safety-aligned cabin systems.
A second layer of competitors brings specialized capabilities and regional strength. Panasonic Automotive Systems delivers infotainment hardware, displays, and integration expertise with strong OEM presence. Pioneer Corporation maintains a dual-track strategy spanning modular head units, navigation, advanced displays, and aftermarket solutions alongside OEM offerings. Visteon Corporation concentrates on digital cockpit electronics, infotainment platforms, and connected vehicle technologies, positioning itself as a focused cockpit specialist. Aptiv PLC emphasizes smart vehicle architectures and connectivity platforms designed to enable digital cockpits and autonomous-adjacent features. Alpine Electronics and JVCKENWOOD Corporation contribute strong human-machine interface, display, audio, and head-unit expertise across OEM and aftermarket channels. LG Electronics adds display and connectivity-oriented vehicle component solutions, while Mitsubishi Electric supports global OEM integration with electronics and infotainment systems. Garmin continues to compete in navigation-centered infotainment experiences. Hyundai Mobis leverages its position as a major Korean OEM supplier to deliver integrated infotainment and vehicle electronics. FORVIA extends its reach through cabin systems that incorporate infotainment integration and interior electronics.
Recent market activity underscores how competition is shifting from discrete product launches to architecture-level alliances and platform continuity. In early 2026, Bosch introduced an AI extension platform that allows advanced cockpit functions to be added to existing vehicle systems without hardware changes, highlighting a strategic bet on software-driven upgradeability. Around the same period, chipset and software collaborators expanded a long-standing partnership to simplify Android updates and enable AI-powered mobility features, reducing integration friction for connected cabin platforms. OEM-level commitments are also reshaping the supply chain. A major European automaker signed a long-term intent to adopt next-generation digital chassis solutions for infotainment and connectivity within a software-defined architecture, signaling a move toward sustained, high-performance cabin computing beginning in the latter half of the decade. Separately, a leading Asian automaker announced enhanced audio-multimedia systems with integrated 5G connectivity rolling out across 2026 model lines, reflecting the broader push to embed stronger network capability directly into consumer-facing cabin products.
The competitive landscape is evolving along three axes. First, integration is intensifying as OEMs prefer fewer, more capable platform partners that can deliver hardware, software frameworks, and connectivity support within coordinated development cycles. Second, specialization persists in areas such as digital audio, display technology, aftermarket flexibility, and navigation-centric experiences, where focused players maintain differentiation through user interface quality and brand familiarity. Third, new entry pressure is rising from software ecosystems, semiconductor companies, and connectivity-focused players who influence cockpit value creation without necessarily manufacturing complete cabin units. The result is a hybrid structure: consolidated platform partnerships at the architecture level, alongside specialized differentiation in interface design, audio, navigation, and region-specific deployment.
Forward Outlook and Strategic Implications
Over the next three to five years, the in-car infotainment market will be shaped by the maturing interplay of software-defined platforms, regulated data ecosystems, and incremental connectivity expansion. The first major trend is the normalization of upgradeable cockpit software. As AI extension pathways, streamlined update frameworks, and centralized compute architectures become more common, vehicles will increasingly decouple feature delivery from hardware refresh cycles. This trend creates commercial opportunities in subscription-adjacent services, personalization engines, voice and context-aware interfaces, and post-sale feature enablement, while demanding disciplined lifecycle management and cybersecurity practices. The second trend is the institutionalization of consent-driven data architectures. Privacy expectations and enforcement patterns will push manufacturers to build transparent data flows, granular user controls, and segregated data handling for personalized infotainment, telematics, and subscription features. Companies that embed trust and compliance into cabin design will reduce regulatory risk and strengthen consumer willingness to adopt connected services. The third trend is selective connectivity escalation rather than uniform premium connectivity across all models. As module costs, integration complexity, and infrastructure readiness vary by region, manufacturers will likely adopt tiered connectivity strategies that reserve higher-bandwidth capabilities for segments where coverage, pricing power, and service demand justify the investment.
PW Consulting
These trends open clear commercial opportunities, but they carry uncertainty. Software-driven upgradeability can create recurring value, yet it also raises expectations for continuous performance, long-term support, and defect management. Privacy regulation may stabilize consumer trust, but it can also constrain data usage models that some service monetization strategies depend on. Connectivity investment can differentiate premium offerings, but uneven network deployment and infrastructure cost may slow feature adoption in certain geographies. The businesses that navigate these conditions successfully will be those that treat infotainment as a long-horizon platform portfolio rather than a one-time hardware procurement decision.
Car Entertainment System Market
Strategic Guidance for Decision-Makers
Manufacturers and platform developers should prioritize architectural flexibility. Designing cockpit systems that support incremental software enhancement, secure update pipelines, and modular connectivity tiers will preserve optionality as features, regulations, and consumer expectations evolve. Investments should be directed toward platforms that can scale across vehicle segments while maintaining consistent interface and service quality, rather than fragmenting development across overly custom cabin architectures. Investors should evaluate exposure to recurring software value, data-governed service models, and alliances that reduce integration risk. The most resilient positions are likely to be held by suppliers and technology partners that combine platform continuity, clear consent architecture, and strong OEM deployment relationships, since these attributes support long-term monetization without relying solely on hardware volume. Procurement and supply chain leaders should balance connectivity ambition with cost realism. Security of supply for critical communication components, transparent pricing structures, and alignment between feature specifications and actual network readiness will matter as much as performance claims. Selecting partners that can accommodate tiered deployment and regional variation will reduce exposure to over-specification and cost volatility.
For all three audiences, the capacity to act on granular, forward-looking market intelligence will determine execution quality. Strategic choices in cockpit architecture, data governance, and supplier partnerships are most effective when supported by detailed segmentation data, competitive benchmarking, and scenario-based guidance. A comprehensive research report can provide the specific breakdowns, regional dynamics, and company-level comparisons needed to translate these market-wide insights into precise, actionable plans.
For detailed analysis of this topic, please visit the official page: Worldwide In-Car Infotainment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Worldwide Naval Vessel MRO Market: 4.84% CAGR and the Strategic Shifts Reshaping 2032
By pmarketresearch, 2026-09-18
Global Naval Vessel MRO Market: Strategic Trends and Commercial Opportunities (2026–2032)
Market Overview and Core Challenges
The worldwide market for naval vessel maintenance, repair, and overhaul (MRO) is navigating a period of steady structural expansion. Total market revenue closed 2025 at approximately USD 64.1 billion, building on a consistent upward trajectory from the early 2020s. Forecasts indicate the sector will reach roughly USD 89.3 billion by 2032, reflecting a compound annual growth rate of 4.84 percent. This growth is not merely cyclical; it reflects a fundamental shift in how navies and defense ministries approach fleet sustainment, driven by aging platforms, extended service life expectations, and the increasing technical complexity of modern warships.
Despite the favorable top-line outlook, the industry faces several structural friction points that will define competitive dynamics over the next five years. The first is capacity saturation at advanced repair facilities. Extended maintenance cycles, overlapping refit schedules, and the complexity of nuclear and highly integrated combat systems have created bottlenecks at flagship shipyard locations. When dry dock slots are fully committed, turnaround times lengthen, forcing navies to weigh trade-offs between operational readiness, cost overruns, and mission scheduling delays.
A second challenge centers on labor availability and cost. Skilled trades, welding certification, specialized engineering talent, and experienced production supervisors remain in short supply across major naval MRO hubs. Because shipyard labor accounts for a substantial share of military vessel repair costs, wage inflation and workforce constraints directly compress margins for contractors and elevate total ownership costs for operators. This pressure is particularly acute in regions where defense and commercial shipbuilding compete for the same skilled labor pool.
The third challenge is regulatory and geopolitical in nature. Domestic procurement rules and naval basing policies restrict where certain vessels can undergo major overhaul or depot-level maintenance, limiting the geographic flexibility of fleet sustainment programs. At the same time, allied navies are seeking to expand maintenance capacity in strategically important regions while balancing security-of-supply concerns. Companies that can navigate these localization requirements while maintaining technical throughput will be better positioned to capture long-cycle contracts.
Together, these constraints are reshaping how the market absorbs demand. Growth is real, but it is uneven across services, vessel categories, and regions. Operators and contractors alike must manage throughput, workforce, and compliance as tightly as they manage technical execution.
Key Drivers of Market Change
Several interlocking forces are pushing the naval MRO sector beyond incremental growth toward a more restructured competitive environment. Understanding these drivers helps explain where margin pools are forming and why certain service lines are outperforming others.
Technology Innovation and Platform Complexity
Modern naval vessels are increasingly defined by integrated combat systems, advanced propulsion suites, and digital architecture that must be maintained throughout long service lives. The proliferation of networking, sensor fusion, radar upgrades, and combat management software means that maintenance is no longer limited to hull, mechanical, and electrical work. It now spans electronics refresh, software sustainment, and signal-processing hardware. As systems become more interdependent, MRO providers with strong integration and lifecycle engineering capabilities gain an advantage in executing modernization and upgrade programs alongside routine operational maintenance.
Propulsion-system MRO is another area where technical intensity is rising. Gas turbines, integrated electric propulsion components, and subsystem Supports require specialized testing, overhaul, and through-life support capabilities. Suppliers that can manage engine overhaul cycles and maintain performance guarantees are capturing a larger share of high-value work, particularly where propulsion accounts for a significant portion of total maintenance budgets.
Policy, Budget Priorities, and Regulatory Constraints
Government procurement rules and defense budget allocation patterns are shaping the shape of demand. Regulatory frameworks in leading naval nations continue to prioritize domestic or allied shipyard capacity for certain overhaul, repair, and maintenance activities. Where such constraints apply, they influence which yards can access high-value program work and how quickly capacity can be expanded. At the same time, defense spending has increasingly emphasized sustainment and modernization for existing fleets rather than solely new construction. Budget allocations for naval maintenance have placed substantial weight on engine and dry-dock MRO activities, reflecting the operational priority of keeping propulsion and hull readiness at high levels. This spending behavior reinforces demand for deep technical overhaul capacity, not just light-touch maintenance.
Demand-Side Shifts and Fleet Sustainment Strategies
Navies are extending the useful life of platforms to bridge gaps between new-build deliveries and evolving mission requirements. That decision changes the MRO demand profile. Older vessels require more frequent refits, system upgrades, and reliability-focused overhauls. At the same time, allied forces are adjusting force posture in key maritime regions, which increases utilization and places additional stress on hulls, propulsion, and supporting systems. The result is a higher cadence of maintenance events across surface combatants, submarines, and support vessels, especially where fleets are operating in demanding environmental or operational conditions.
A notable dynamic is the opening of allied maintenance capacity in strategically significant theaters. In recent cycles, major South Korean shipyards have secured multiple U.S. Navy MRO contracts for logistics support and dry-cargo vessels, expanding available maintenance throughput for forward-deployed fleet sustainment. These awards illustrate how allied yards can supplement domestic capacity for certain vessel classes, particularly auxiliary and support platforms, while also signaling the strategic importance of Indo-Pacific maintenance availability.
Military Helicopter MRO Market
Supply Chain and Cost Structure Pressures
Input cost inflation is reshaping MRO economics. Naval-grade steel plate prices in Northeast Asia have trended higher in recent months, driven partly by concurrent demand from ship repair and construction activity. While material cost is only one component of total repair spend, it interacts with labor, tooling, and schedule risk to influence bid competitiveness and contract profitability. In parallel, supply chain complexity for specialized components—engine modules, combat system elements, sensors—can create lead-time uncertainty, especially when multiple programs are competing for the same subsystem supply. Providers that maintain buffer capacity, long-term supplier relationships, and in-house fabrication capabilities can manage cost volatility more effectively than those dependent on spot-market procurement.
These drivers point to a market where technical depth, operational flexibility, and localized capacity are increasingly valuable. The winners are likely to be those who can combine throughput, compliance, and lifecycle engineering while managing labor and input-cost pressures.
Competitive Landscape and Leading Strategies
The global naval MRO market is moderately concentrated, with a small group of large primes and specialized shipbuilders holding meaningful shares across hull repair, depot-level overhaul, and modernization services. Concentration is not uniform, however. Leadership varies by geography, vessel class, and service type, with different firms competing on integration, shipyard infrastructure, propulsion expertise, or electronics and combat-system sustainment.
American firms continue to anchor a significant portion of U.S. Navy MRO activity. Huntington Ingalls Industries maintains a central position through Newport News Shipbuilding for nuclear-powered carrier refueling and complex overhaul, as well as submarine work, while Ingalls Shipbuilding supports surface combatant maintenance. General Dynamics, through NASSCO and Electric Boat, executes repair, overhaul, and maintenance across U.S. auxiliary, support, and submarine fleets at multiple domestic ports. These players benefit from deep institutional relationships, existing dry-dock infrastructure, and close alignment with naval sustainment requirements. Their strategic differentiation often lies in the ability to handle the most technically demanding overhauls while managing lifecycle complexity.
Aircraft Engine MRO Market
European and allied capabilities add breadth and geographic diversification. BAE Systems provides surface ship, submarine, and combat-system MRO across the UK, U.S., and Australia, combining dry-dock repair with system upgrades. Naval Group focuses on French and export fleets with through-life support, refits, and modernization programs for submarines and surface ships. Fincantieri leverages a broad European shipyard network for military and coast guard repair and overhaul, while Damen operates a global network of repair yards serving naval and patrol vessel MRO. Rolls-Royce targets naval propulsion and power systems, including engine overhaul and through-life support for marine gas turbines and integrated systems. Thales concentrates on electronics, sensors, and combat management system sustainment. Each of these players competes not just on repair execution but on the ability to sustain mission-critical capabilities over time.
A second layer of competitors focuses on platform-specific or region-specific specialization. Babcock delivers complex through-life support for Royal Navy surface ships and submarines. Lockheed Martin brings systems integration, combat-system upgrades, and Aegis-related sustainment. Austal supports aluminum-hulled patrol boats and littoral combat ship MRO in Australia and the U.S. Navantia offers frigate and submarine sustainment for Spanish and export fleets. ThyssenKrupp Marine Systems emphasizes submarine MRO and surface ship repair for German and international customers. Kongsberg Maritime focuses on sensors, weapons control, and integrated maritime technology. HD Hyundai Heavy Industries has stepped into U.S. Navy logistics vessel MRO at Korean yards, and Larsen & Toubro supports Indian Navy ships and submarines through its shipbuilding and defense divisions. This layered landscape means that competition is often winnable by firms that match the right combination of hull infrastructure, technical specialization, and geographic access.
Recent developments illustrate how the landscape is evolving. HD Hyundai Heavy Industries secured a contract for scheduled maintenance and overhaul of USNS Cesar Chavez, a large logistics support vessel for the U.S. Navy's 7th Fleet, while HJ Shipbuilding & Construction signed a mid-term availability contract for USNS Amelia Earhart at its Yeongdo shipyard, marking its first U.S. Navy MRO work in that location. Separately, Huntington Ingalls Industries completed the acquisition of W International to reinforce the nuclear-powered submarine supply chain and expand MRO capacity at Newport News Shipbuilding. These moves show two parallel strategic paths: expansion of allied maintenance capacity for support and logistics vessels, and consolidation or capability-building for the most technically demanding nuclear and submarine work.
The broader trend is one of selective integration and differentiated expansion. Primes are strengthening supply chains, absorbing specialized providers, or expanding dry-dock and workforce capacity where demand is structurally rising. At the same time, new entrants and regional specialists are competing for segments that are less constrained by domestic shipyard rules, especially auxiliary and support vessel maintenance. Over time, the market is likely to see continued differentiation: leaders will compete on lifecycle integration and high-complexity overhaul, while regional yards will compete on availability, cost, and geographic coverage for specific vessel classes.
Future Trends and Outlook
The next three to five years are likely to be defined by capacity reallocation, service mix shifts, and a growing premium on technical integration. Several trends stand out.
First, allied and partner-shipyard MRO is expected to expand for certain vessel categories, particularly auxiliary, logistics, and support platforms. Navies facing domestic capacity constraints and extended maintenance backlogs are likely to continue seeking capable allied yards for non-nuclear and selected surface vessel work. This trend creates commercial opportunities for shipyards that can demonstrate throughput, compliance, and U.S. or allied certification alignment, but it also carries execution risk if workforce, standards, or logistics synchronization are not carefully managed.
Second, modernization and upgrade activity will increasingly become a strategic growth layer within MRO programs. As fleets age and combat systems evolve, maintenance contracts will more often include sensor refreshes, combat-system updates, propulsion optimization, and reliability-centered retrofits. Providers that can bundle operational maintenance with depot-level overhaul and system modernization will be better positioned to capture full-lifecycle value and reduce program discontinuity.
Third, labor, material, and capacity constraints will continue to pressure cost structures and schedule reliability. Wage inflation for skilled trades, ongoing workforce shortages, and input-cost volatility for naval-grade materials are likely to remain part of the operating environment. This will reward contractors with strong workforce pipelines, in-house fabrication and testing capabilities, and the ability to plan long-cycle maintenance with greater predictability. It also implies that bid strategy and contract design will matter more, especially where performance incentives and throughput commitments are tied to readiness outcomes.
PW Consulting
Potential uncertainties include shifts in defense budget pacing, changes in domestic shipyard policy, and geopolitical friction that could alter fleet deployment patterns or maintenance routing. If utilization patterns change rapidly, maintenance demand could become more volatile, affecting yard planning and supplier commitments. However, the underlying direction—aging fleets, rising technical complexity, and sustained emphasis on sustainment—points to a market where MRO is not a supporting function but a core strategic activity for naval operators and a durable commercial arena for capable providers.
Actionable Guidance for Decision-Makers
For manufacturers and MRO service providers, the priority is to match technical depth with capacity realism. Companies should identify which service lines—operational maintenance, depot-level overhaul, or modernization—offer the clearest path to differentiated margin, then invest in workforce pipelines, dry-dock or test infrastructure, and long-cycle supplier relationships where those assets can be secured. Partnerships with subsystem specialists in propulsion, sensors, and combat systems can extend value capture without requiring full ownership of every capability.
For investors, the most interesting questions revolve around where consolidation and capability-building will translate into durable revenue visibility. Firms with strong positioning in high-complexity nuclear or submarine MRO, integrated combat-system sustainment, or allied-authorization logistics support may offer stronger competitive moats than those competing primarily on generic repair availability. Monitoring contract backlogs, yard expansion announcements, and acquisition activity can provide early signals about which players are gaining throughput advantage.
For procurement and fleet sustainment leaders, the focus should be on balancing domestic and allied capacity strategies while reducing schedule risk. Diversifying maintenance pathways for support and logistics vessels, strengthening lifecycle integration for upgrading platforms, and contracting for workforce and material cost realism can improve readiness outcomes without overcommitting to single-source bottlenecks. In all cases, timely, granular intelligence on regional capacity, service-line demand, and competitor moves is essential for making informed judgments in a market where timing and access increasingly determine outcomes. For teams that need deeper segmentation, regional detail, and scenario-based guidance, the full research report provides the breakdown required to translate these trends into concrete investment and contracting decisions.
For detailed analysis of this topic, please visit the official page: Worldwide Naval Vessel Maintenance, Repair and Overhaul (MRO) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Rocket Propulsion System Market: Why 7.5% CAGR and Commercial Demand Redefine the Industry
By pmarketresearch, 2026-09-18
Strategic Shifts and Commercial Opportunities in the Global Rocket Propulsion System Market
Market Landscape and Core Challenges
The rocket propulsion system market has entered a phase of sustained expansion, driven by an unprecedented intersection of commercial ambition, national security modernization, and technological maturation. Over the past half-decade, the sector has transitioned from a niche defense and research-driven ecosystem into a dynamic commercial infrastructure market. This structural shift reflects renewed confidence in orbital access as a viable economic platform rather than an exploratory luxury. The industry now operates against a backdrop where recurring launch cadence, reusable architectures, and diversified mission profiles are fundamentally reshaping procurement cycles, validation timelines, and supplier ecosystems.
At its core, the market is navigating a period of transition where legacy production paradigms are colliding with new performance requirements. Propulsion systems are no longer evaluated solely on peak thrust or reliability thresholds; they are assessed against operational economics, reusability potential, supply chain resilience, and lifecycle serviceability. This evolution has created pressure across the value chain, forcing manufacturers to balance high engineering standards with cost discipline, while operators demand faster integration timelines without compromising certification readiness. The resulting tension defines the current market environment and sets the stage for strategic decision-making.
Three critical challenges currently shape the industry trajectory. First, the certification and qualification bottleneck remains a persistent drag on launch cadence. Regulatory frameworks require rigorous propulsion system validation before commercial orbital operations, creating extended development windows that can erode first-mover advantages and delay revenue realization. Propulsion architectures that push material or combustion boundaries must navigate overlapping safety, environmental, and flight-worthy testing requirements, compounding cost and schedule risk.
Rocket Engine Market
Second, supply chain vulnerability continues to constrain design flexibility and pricing stability. High-performance propulsion components depend on specialized materials, precision metallurgy, and tightly controlled manufacturing processes that are not easily replicated across geographies. This concentration creates exposure to raw material fluctuations, labor constraints, and geopolitical friction, especially as programs scale from prototype to serial production.
Third, the competitive landscape is widening while procurement models are fragmenting. Buyers increasingly seek customized propulsion solutions tailored to specific mission classes rather than standardized offerings. This demand diversification makes it harder for suppliers to amortize development costs across broad customer bases, raising the stakes for platform strategy and partnership structures. The market is therefore moving toward an environment where scale alone is insufficient; differentiation must be rooted in engineering agility, integration capability, and long-term service economics.
Core Drivers Shaping Market Momentum
Technological innovation remains the most visible catalyst in the propulsion sector, but the nature of the innovation has shifted from performance maximization to system-level efficiency. Reusability, combustion optimization, and advanced manufacturing are now intertwined in a single design philosophy. Additive manufacturing, for example, has enabled engineers to reduce part count, accelerate iteration cycles, and incorporate geometries that improve cooling and combustion stability. The practical impact is not simply higher thrust; it is faster engine development, more flexible design modification, and greater resilience in production scaling. Companies pursuing reusable launch architectures are particularly dependent on propulsion systems that can withstand repeated thermal cycling, rapid refurbishment, and higher flight frequency without degrading performance margins.
A second major driver is the reconfiguration of the policy and export control environment. Propulsion technologies remain tightly governed under national security frameworks, with export licensing regimes affecting cross-border collaboration, component sourcing, and market access. These controls are not static; they evolve alongside geopolitical priorities and commercial space ambitions. As a result, manufacturers and launch operators must align development roadmaps with regulatory expectations, often favoring domestic supply chains and partner ecosystems that reduce exposure to licensing delays. This dynamic is steering investment toward homegrown alternatives and encouraging regional capability-building, especially when reliance on foreign-supplied propulsion components introduces strategic risk.
The third driver lies in demand-side transformation. Commercial markets are expanding the definition of viable payloads and orbital destinations, which in turn changes propulsion requirements. Low Earth orbit activity has grown in intensity, fueling demand for rapid deployment, constellation servicing, and high-cadence launch support. At the same time, payload complexity and mission diversity are pushing propulsion design teams to accommodate wider performance envelopes, from small-lift responsiveness to heavy-lift endurance. The commercial side of the market is not merely adding volume; it is adding variety, and that variety places new pressure on propulsion suppliers to modularize engineering, streamline qualification pathways, and offer repeatable integration models.
The fourth driver is the changing cost and supply structure surrounding propulsion programs. Fuel and oxidizer inputs remain an important variable, but more significant is the broader cost architecture of production and test operations. Stable fundamentals for industrial consumables reduce one layer of variability, yet the real cost pressure is concentrated upstream in precision components, specialized testing, and talent-intensive manufacturing. Firms that can shorten development cycles, reduce hardware complexity, and streamline qualification testing gain a structural advantage because their per-unit economics improve faster as flight rates rise. In this sense, cost competitiveness is increasingly a function of process maturity and integration efficiency rather than raw material pricing alone.
These drivers converge into a market in which technological capability and procurement strategy are deeply linked. Recent program milestones illustrate this dynamic in practice. The successful introduction of major commercial launch systems powered by next-generation engine architectures demonstrates how new propulsion families can unlock operational flexibility for heavy-lift and medium-lift missions. Engine qualification tests and static-fire achievements signal that performance targets are being validated at a pace that supports faster program progression. At the same time, contract awards tied to flagship exploration and national launch programs reinforce the role of propulsion as a long-cycle strategic asset, where sustained production continuity matters as much as peak technical performance. Together, these developments show that propulsion advancement is not only about engineering milestones; it is about establishing repeatable, certifiable systems that can support sustained operational demand.
Competitive Positioning and Evolving Market Structure
The competitive field is defined by a mix of established aerospace suppliers, vertically integrated launch providers, and newer technology-focused entrants. Legacy players bring deep experience in cryogenic and solid propulsion, long-standing qualification records, and institutional relationships with major launch programs. Their advantage lies in capability maturity, proven flight heritage, and the ability to support complex national and defense requirements. For high-assurance missions, this reliability remains a decisive factor, particularly where propulsion systems must satisfy stringent safety, performance, and lifecycle expectations over extended program lifetimes.
Worldwide UAV Propulsion System Market
At the same time, new market leadership is being shaped by companies that treat propulsion as an integrated part of the broader launch system rather than a standalone component. Vertically integrated providers often design engines to match specific vehicle architectures, enabling tighter control over vehicle performance, recovery strategy, and production cadence. This close coupling can reduce integration risk and accelerate iteration, but it also concentrates engineering responsibility and raises the bar for certification readiness. In practice, the most differentiated players are those that can pair aggressive performance goals with disciplined manufacturing, testing, and refurbishment plans.
Several firms are building differentiation around advanced manufacturing and engine architecture innovation. Additive techniques, compact pump-fed designs, and alternative fuel considerations are being used to improve manufacturability, reduce system complexity, and support reuse. Where this strategy succeeds, it lowers the barrier to rapid engine iteration and creates platforms that can be scaled across multiple vehicle classes. Where it is pursued without sufficient validation discipline, however, it increases the risk of qualification delays and flight anomalies. The market is therefore rewarding organizations that can demonstrate not just novel designs, but also repeatable test outcomes and practical serviceability.
The competitive landscape is also being influenced by geographic and programmatic diversification. European and Asian suppliers continue to play important roles in national launch systems and specialized propulsion components, reinforcing regional autonomy and supply diversity. Their strategies increasingly emphasize independent launch capability, specialized solid and liquid propulsion expertise, and partnership models that broaden access to international programs. Meanwhile, newer entrants often compete by targeting underserved performance segments, focusing on responsiveness, or developing propulsion solutions optimized for specific reuse profiles and mission types.
Market structure appears to be evolving along multiple paths rather than a single consolidation curve. In some areas, consolidation and partnership are becoming more likely as development costs, qualification requirements, and flight-rate expectations rise. In other areas, fragmentation persists as operators seek propulsion tailored to specific mission classes and price-performance profiles. The result is a market where incumbents must continually defend platform relevance while challengers must prove that they can scale from prototype success to sustained production and certification compliance. Strategic positioning is therefore less about raw brand presence and more about engineering roadmaps, manufacturing scalability, partnership leverage, and the ability to meet regulatory expectations without losing time-to-market momentum.
PW Consulting
Forward Outlook: Trends and Strategic Implications
Over the next three to five years, propulsion markets will likely be shaped by three reinforcing trends. The first is the further normalization of reusability as a design baseline rather than a special-case feature. As flight rates increase and refurbishment processes mature, propulsion systems will be judged more heavily on lifecycle durability, turnaround efficiency, and cumulative operational cost. This will favor architectures that can balance high performance with practical maintainability, and it will intensify scrutiny of thermal management, turbomachinery reliability, and engine health monitoring.
The second trend is the continued fragmentation and specialization of propulsion demand. Rather than converging on a single dominant solution, the market is likely to support a broader range of engine classes aligned with different lift categories, mission orbits, and client priorities. That implies opportunities for suppliers that can offer modular design approaches, shorter integration cycles, and clear qualification pathways. It also means greater competition within each niche, rewarding companies that can differentiate through process efficiency, testing discipline, and customer-specific integration support.
The third trend is the growing importance of supply chain and regulatory resilience as strategic assets. Firms that can secure critical components, maintain domestic production continuity, and navigate export control requirements with minimal friction will have a meaningful advantage, especially when programs depend on sustained multi-year delivery schedules. At the same time, regulatory and certification processes may continue to act as pacing factors, meaning that market momentum will not always translate directly into immediate launch cadence. The practical implication is that commercial opportunity will accrue to organizations that manage both engineering ambition and compliance realism in parallel.
These trends create openings for propulsion suppliers, launch operators, and investors, but they also carry uncertainty. Technical breakthroughs may accelerate, or they may encounter certification and yield challenges that delay scaling. Demand growth can be strong yet uneven, with some mission segments expanding faster than others. And competitive intensity may pressure margins even as volumes rise. Successful positioning will depend on anticipating which segments will demand scale, which will reward specialization, and which will be constrained by regulatory or supply-side friction.
Strategic Recommendations for Decision-Makers
For propulsion manufacturers and subsystem developers, the priority should be to align engineering roadmaps with lifecycle economics rather than focusing exclusively on peak performance. Investing in manufacturability, test efficiency, refurbishment design, and qualification readiness can create more durable competitive advantage than pursuing isolated technical records. Partnerships that reduce integration risk and stabilize production continuity will also matter as programs move from demonstration to recurring flight.
For investors, the most valuable diligence questions center on scalability and compliance realism. Technical demonstrations are necessary but not sufficient; the commercial case depends on whether an engine architecture can be qualified efficiently, produced repeatedly, and supported through a high operational tempo. Capital allocation should favor organizations with credible manufacturing plans, disciplined testing pipelines, and strategies that reduce exposure to export control or component scarcity risks.
For procurement teams and launch operators, the strategic focus should be on balancing supplier maturity with program agility. Standardized propulsion can speed integration, but mission diversity increasingly rewards suppliers that can tailor solutions without adding excessive overhead. Evaluating vendors through the lens of lifecycle support, refurbishment capability, and regulatory readiness may yield better long-term outcomes than selecting solely on initial cost or headline performance metrics.
Given the pace of change across engine architectures, certification pathways, and program-specific demand, access to current segment-level intelligence is essential for avoiding strategic blind spots. More detailed breakdowns on propulsion types, regional dynamics, end-user demand, orbit-specific requirements, and company-specific development trajectories are available in the full research report, which provides the deeper data and segmentation needed for planning, sourcing, and investment decisions.
For detailed analysis of this topic, please visit the official page: Worldwide Rocket Propulsion System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com