

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Worldwide Naval Vessel MRO Market: 4.84% CAGR and the Strategic Shifts Reshaping 2032

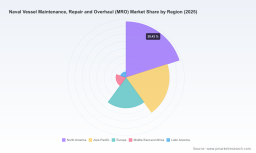
Global Naval Vessel MRO Market: Strategic Trends and Commercial Opportunities (2026–2032)
Market Overview and Core Challenges
The worldwide market for naval vessel maintenance, repair, and overhaul (MRO) is navigating a period of steady structural expansion. Total market revenue closed 2025 at approximately USD 64.1 billion, building on a consistent upward trajectory from the early 2020s. Forecasts indicate the sector will reach roughly USD 89.3 billion by 2032, reflecting a compound annual growth rate of 4.84 percent. This growth is not merely cyclical; it reflects a fundamental shift in how navies and defense ministries approach fleet sustainment, driven by aging platforms, extended service life expectations, and the increasing technical complexity of modern warships.
Despite the favorable top-line outlook, the industry faces several structural friction points that will define competitive dynamics over the next five years. The first is capacity saturation at advanced repair facilities. Extended maintenance cycles, overlapping refit schedules, and the complexity of nuclear and highly integrated combat systems have created bottlenecks at flagship shipyard locations. When dry dock slots are fully committed, turnaround times lengthen, forcing navies to weigh trade-offs between operational readiness, cost overruns, and mission scheduling delays.
A second challenge centers on labor availability and cost. Skilled trades, welding certification, specialized engineering talent, and experienced production supervisors remain in short supply across major naval MRO hubs. Because shipyard labor accounts for a substantial share of military vessel repair costs, wage inflation and workforce constraints directly compress margins for contractors and elevate total ownership costs for operators. This pressure is particularly acute in regions where defense and commercial shipbuilding compete for the same skilled labor pool.
The third challenge is regulatory and geopolitical in nature. Domestic procurement rules and naval basing policies restrict where certain vessels can undergo major overhaul or depot-level maintenance, limiting the geographic flexibility of fleet sustainment programs. At the same time, allied navies are seeking to expand maintenance capacity in strategically important regions while balancing security-of-supply concerns. Companies that can navigate these localization requirements while maintaining technical throughput will be better positioned to capture long-cycle contracts.
Together, these constraints are reshaping how the market absorbs demand. Growth is real, but it is uneven across services, vessel categories, and regions. Operators and contractors alike must manage throughput, workforce, and compliance as tightly as they manage technical execution.
Key Drivers of Market Change
Several interlocking forces are pushing the naval MRO sector beyond incremental growth toward a more restructured competitive environment. Understanding these drivers helps explain where margin pools are forming and why certain service lines are outperforming others.
Technology Innovation and Platform Complexity
Modern naval vessels are increasingly defined by integrated combat systems, advanced propulsion suites, and digital architecture that must be maintained throughout long service lives. The proliferation of networking, sensor fusion, radar upgrades, and combat management software means that maintenance is no longer limited to hull, mechanical, and electrical work. It now spans electronics refresh, software sustainment, and signal-processing hardware. As systems become more interdependent, MRO providers with strong integration and lifecycle engineering capabilities gain an advantage in executing modernization and upgrade programs alongside routine operational maintenance.
Propulsion-system MRO is another area where technical intensity is rising. Gas turbines, integrated electric propulsion components, and subsystem Supports require specialized testing, overhaul, and through-life support capabilities. Suppliers that can manage engine overhaul cycles and maintain performance guarantees are capturing a larger share of high-value work, particularly where propulsion accounts for a significant portion of total maintenance budgets.
Policy, Budget Priorities, and Regulatory Constraints
Government procurement rules and defense budget allocation patterns are shaping the shape of demand. Regulatory frameworks in leading naval nations continue to prioritize domestic or allied shipyard capacity for certain overhaul, repair, and maintenance activities. Where such constraints apply, they influence which yards can access high-value program work and how quickly capacity can be expanded. At the same time, defense spending has increasingly emphasized sustainment and modernization for existing fleets rather than solely new construction. Budget allocations for naval maintenance have placed substantial weight on engine and dry-dock MRO activities, reflecting the operational priority of keeping propulsion and hull readiness at high levels. This spending behavior reinforces demand for deep technical overhaul capacity, not just light-touch maintenance.
Demand-Side Shifts and Fleet Sustainment Strategies
Navies are extending the useful life of platforms to bridge gaps between new-build deliveries and evolving mission requirements. That decision changes the MRO demand profile. Older vessels require more frequent refits, system upgrades, and reliability-focused overhauls. At the same time, allied forces are adjusting force posture in key maritime regions, which increases utilization and places additional stress on hulls, propulsion, and supporting systems. The result is a higher cadence of maintenance events across surface combatants, submarines, and support vessels, especially where fleets are operating in demanding environmental or operational conditions.
A notable dynamic is the opening of allied maintenance capacity in strategically significant theaters. In recent cycles, major South Korean shipyards have secured multiple U.S. Navy MRO contracts for logistics support and dry-cargo vessels, expanding available maintenance throughput for forward-deployed fleet sustainment. These awards illustrate how allied yards can supplement domestic capacity for certain vessel classes, particularly auxiliary and support platforms, while also signaling the strategic importance of Indo-Pacific maintenance availability.
Military Helicopter MRO Market
Supply Chain and Cost Structure Pressures
Input cost inflation is reshaping MRO economics. Naval-grade steel plate prices in Northeast Asia have trended higher in recent months, driven partly by concurrent demand from ship repair and construction activity. While material cost is only one component of total repair spend, it interacts with labor, tooling, and schedule risk to influence bid competitiveness and contract profitability. In parallel, supply chain complexity for specialized components—engine modules, combat system elements, sensors—can create lead-time uncertainty, especially when multiple programs are competing for the same subsystem supply. Providers that maintain buffer capacity, long-term supplier relationships, and in-house fabrication capabilities can manage cost volatility more effectively than those dependent on spot-market procurement.
These drivers point to a market where technical depth, operational flexibility, and localized capacity are increasingly valuable. The winners are likely to be those who can combine throughput, compliance, and lifecycle engineering while managing labor and input-cost pressures.
Competitive Landscape and Leading Strategies
The global naval MRO market is moderately concentrated, with a small group of large primes and specialized shipbuilders holding meaningful shares across hull repair, depot-level overhaul, and modernization services. Concentration is not uniform, however. Leadership varies by geography, vessel class, and service type, with different firms competing on integration, shipyard infrastructure, propulsion expertise, or electronics and combat-system sustainment.
American firms continue to anchor a significant portion of U.S. Navy MRO activity. Huntington Ingalls Industries maintains a central position through Newport News Shipbuilding for nuclear-powered carrier refueling and complex overhaul, as well as submarine work, while Ingalls Shipbuilding supports surface combatant maintenance. General Dynamics, through NASSCO and Electric Boat, executes repair, overhaul, and maintenance across U.S. auxiliary, support, and submarine fleets at multiple domestic ports. These players benefit from deep institutional relationships, existing dry-dock infrastructure, and close alignment with naval sustainment requirements. Their strategic differentiation often lies in the ability to handle the most technically demanding overhauls while managing lifecycle complexity.
Aircraft Engine MRO Market
European and allied capabilities add breadth and geographic diversification. BAE Systems provides surface ship, submarine, and combat-system MRO across the UK, U.S., and Australia, combining dry-dock repair with system upgrades. Naval Group focuses on French and export fleets with through-life support, refits, and modernization programs for submarines and surface ships. Fincantieri leverages a broad European shipyard network for military and coast guard repair and overhaul, while Damen operates a global network of repair yards serving naval and patrol vessel MRO. Rolls-Royce targets naval propulsion and power systems, including engine overhaul and through-life support for marine gas turbines and integrated systems. Thales concentrates on electronics, sensors, and combat management system sustainment. Each of these players competes not just on repair execution but on the ability to sustain mission-critical capabilities over time.
A second layer of competitors focuses on platform-specific or region-specific specialization. Babcock delivers complex through-life support for Royal Navy surface ships and submarines. Lockheed Martin brings systems integration, combat-system upgrades, and Aegis-related sustainment. Austal supports aluminum-hulled patrol boats and littoral combat ship MRO in Australia and the U.S. Navantia offers frigate and submarine sustainment for Spanish and export fleets. ThyssenKrupp Marine Systems emphasizes submarine MRO and surface ship repair for German and international customers. Kongsberg Maritime focuses on sensors, weapons control, and integrated maritime technology. HD Hyundai Heavy Industries has stepped into U.S. Navy logistics vessel MRO at Korean yards, and Larsen & Toubro supports Indian Navy ships and submarines through its shipbuilding and defense divisions. This layered landscape means that competition is often winnable by firms that match the right combination of hull infrastructure, technical specialization, and geographic access.
Recent developments illustrate how the landscape is evolving. HD Hyundai Heavy Industries secured a contract for scheduled maintenance and overhaul of USNS Cesar Chavez, a large logistics support vessel for the U.S. Navy's 7th Fleet, while HJ Shipbuilding & Construction signed a mid-term availability contract for USNS Amelia Earhart at its Yeongdo shipyard, marking its first U.S. Navy MRO work in that location. Separately, Huntington Ingalls Industries completed the acquisition of W International to reinforce the nuclear-powered submarine supply chain and expand MRO capacity at Newport News Shipbuilding. These moves show two parallel strategic paths: expansion of allied maintenance capacity for support and logistics vessels, and consolidation or capability-building for the most technically demanding nuclear and submarine work.
The broader trend is one of selective integration and differentiated expansion. Primes are strengthening supply chains, absorbing specialized providers, or expanding dry-dock and workforce capacity where demand is structurally rising. At the same time, new entrants and regional specialists are competing for segments that are less constrained by domestic shipyard rules, especially auxiliary and support vessel maintenance. Over time, the market is likely to see continued differentiation: leaders will compete on lifecycle integration and high-complexity overhaul, while regional yards will compete on availability, cost, and geographic coverage for specific vessel classes.
Future Trends and Outlook
The next three to five years are likely to be defined by capacity reallocation, service mix shifts, and a growing premium on technical integration. Several trends stand out.
First, allied and partner-shipyard MRO is expected to expand for certain vessel categories, particularly auxiliary, logistics, and support platforms. Navies facing domestic capacity constraints and extended maintenance backlogs are likely to continue seeking capable allied yards for non-nuclear and selected surface vessel work. This trend creates commercial opportunities for shipyards that can demonstrate throughput, compliance, and U.S. or allied certification alignment, but it also carries execution risk if workforce, standards, or logistics synchronization are not carefully managed.
Second, modernization and upgrade activity will increasingly become a strategic growth layer within MRO programs. As fleets age and combat systems evolve, maintenance contracts will more often include sensor refreshes, combat-system updates, propulsion optimization, and reliability-centered retrofits. Providers that can bundle operational maintenance with depot-level overhaul and system modernization will be better positioned to capture full-lifecycle value and reduce program discontinuity.
Third, labor, material, and capacity constraints will continue to pressure cost structures and schedule reliability. Wage inflation for skilled trades, ongoing workforce shortages, and input-cost volatility for naval-grade materials are likely to remain part of the operating environment. This will reward contractors with strong workforce pipelines, in-house fabrication and testing capabilities, and the ability to plan long-cycle maintenance with greater predictability. It also implies that bid strategy and contract design will matter more, especially where performance incentives and throughput commitments are tied to readiness outcomes.
PW Consulting
Potential uncertainties include shifts in defense budget pacing, changes in domestic shipyard policy, and geopolitical friction that could alter fleet deployment patterns or maintenance routing. If utilization patterns change rapidly, maintenance demand could become more volatile, affecting yard planning and supplier commitments. However, the underlying direction—aging fleets, rising technical complexity, and sustained emphasis on sustainment—points to a market where MRO is not a supporting function but a core strategic activity for naval operators and a durable commercial arena for capable providers.
Actionable Guidance for Decision-Makers
For manufacturers and MRO service providers, the priority is to match technical depth with capacity realism. Companies should identify which service lines—operational maintenance, depot-level overhaul, or modernization—offer the clearest path to differentiated margin, then invest in workforce pipelines, dry-dock or test infrastructure, and long-cycle supplier relationships where those assets can be secured. Partnerships with subsystem specialists in propulsion, sensors, and combat systems can extend value capture without requiring full ownership of every capability.
For investors, the most interesting questions revolve around where consolidation and capability-building will translate into durable revenue visibility. Firms with strong positioning in high-complexity nuclear or submarine MRO, integrated combat-system sustainment, or allied-authorization logistics support may offer stronger competitive moats than those competing primarily on generic repair availability. Monitoring contract backlogs, yard expansion announcements, and acquisition activity can provide early signals about which players are gaining throughput advantage.
For procurement and fleet sustainment leaders, the focus should be on balancing domestic and allied capacity strategies while reducing schedule risk. Diversifying maintenance pathways for support and logistics vessels, strengthening lifecycle integration for upgrading platforms, and contracting for workforce and material cost realism can improve readiness outcomes without overcommitting to single-source bottlenecks. In all cases, timely, granular intelligence on regional capacity, service-line demand, and competitor moves is essential for making informed judgments in a market where timing and access increasingly determine outcomes. For teams that need deeper segmentation, regional detail, and scenario-based guidance, the full research report provides the breakdown required to translate these trends into concrete investment and contracting decisions.
For detailed analysis of this topic, please visit the official page: Worldwide Naval Vessel Maintenance, Repair and Overhaul (MRO) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com