

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Worldwide Submersible Market Surpasses $285M: The 8.74% CAGR Playbook

Navigating the Strategic Currents: Commercial Submersible Market Trends and Opportunities Through 2032
Market Status and Core Challenges
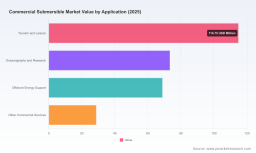
The global commercial submersible market has demonstrated robust momentum over the past five years, evolving from a mature industrial segment into a dynamic growth arena. Valued at approximately $182.15 million in 2020, the market expanded steadily to reach $285.5 million by 2025, reflecting a compound annual growth rate of 8.74 percent projected through the 2032 forecast period. This trajectory signals more than incremental improvement; it indicates a structural shift where submersible technology is becoming integral to broader commercial and industrial workflows. The projected valuation ceiling of over $513 million by 2032 underscores the accelerating adoption across diverse operational environments.
Despite this positive momentum, the industry stands at a critical inflection point defined by three interconnected challenges. First, the regulatory landscape is tightening globally, forcing manufacturers to reconcile performance demands with increasingly stringent efficiency standards. The drive toward sustainability is no longer optional but a licensing requirement for market access in key regions. Second, supply chain volatility continues to pressure cost structures, particularly regarding raw material pricing and availability. Fluctuations in steel markets directly impact production economics, creating margin compression risks for companies unable to optimize procurement or redesign for material efficiency. Third, the market is experiencing a divergence in application requirements, where the needs of heavy industrial operations increasingly conflict with the precision and reliability demands of municipal and commercial infrastructure. Manufacturers must decide whether to specialize deeply or maintain broad portfolios capable of addressing conflicting specifications.
Underwater Pelletizer Market
Key Drivers of Market Change
Technological Innovation and Performance Breakthroughs
Technological advancement remains the primary catalyst propelling market expansion. The industry is witnessing a transition from conventional mechanical designs to engineered systems that prioritize energy efficiency, material durability, and operational intelligence. Recent product introductions highlight this shift toward purpose-built submersible solutions. KSB SE & Co. KGaA expanded its portfolio with the CORAChrom stainless-steel range engineered for deep borehole and demanding freshwater and saline environments. This launch targets irrigation, dewatering, construction, mining, and commercial building sectors, addressing the need for corrosion-resistant performance in harsh conditions. Later in the same year, the company introduced submersible motor pumps featuring axial propellers, demonstrating continued investment in hydrodynamic optimization for enhanced efficiency.
Similarly, Franklin Electric advanced its position through targeted product development. The launch of the Pioneer Pump Minetuff series in early 2025 focused on abrasive material handling with durable construction and adjustable hydraulics. This was followed by an expansion of the FPS Wastewater Pumps lineup, adding sump, effluent, and grinder models designed for commercial applications with improved solids-handling capabilities. These developments reflect a broader industry pattern where manufacturers are engineering products for specific operational pain points rather than offering generic solutions. The emphasis on anti-clogging hydraulics, explosion-proof options, and variable operating conditions indicates that customers increasingly demand reliability under extreme or unpredictable conditions.
Regulatory and Policy Environment
Regulatory frameworks are reshaping competitive dynamics by establishing minimum performance thresholds that all market participants must meet. The EU Ecodesign Regulation establishes efficiency benchmarks for water pumps, requiring a Minimum Efficiency Index value at or above 0.4, with ongoing reviews exploring expansion to wastewater and industrial submersible pumps. This regulatory trajectory pushes manufacturers to prioritize motor efficiency and hydraulic optimization during the design phase rather than treating efficiency as an afterthought. In the United States, energy conservation standards and test procedures emphasize wire-to-water efficiency for submersible motor-driven pumps, covering hydraulic performance, hydrostatic, mechanical, and electrical acceptance tests. Compliance with these standards is becoming a baseline requirement for commercial procurement, particularly in government and municipal contracts where regulatory adherence is mandatory.
Beyond efficiency mandates, policy-driven infrastructure investment is creating sustained demand. Increasing infrastructure investments and urbanization are driving demand for submersible pumps in wastewater management and groundwater extraction across commercial sectors. Government spending on water infrastructure, flood mitigation, and urban development projects generates recurring procurement cycles that favor established suppliers with proven compliance records. However, regulatory fragmentation across regions also creates complexity, as manufacturers must navigate differing standards when serving global markets.
Demand-Side Shifts and Application Diversification
Customer behavior and application requirements are evolving in ways that expand the addressable market while raising performance expectations. The growing emphasis on sustainable water management and resilient infrastructure is pushing end users to adopt submersible solutions that offer longer service life, lower total cost of ownership, and reduced environmental impact. In commercial and industrial settings, operators are prioritizing systems that minimize downtime and maintenance intervention, recognizing that operational continuity directly impacts revenue and compliance. This shift favors suppliers who can provide integrated solutions combining durable materials, efficient motors, and application-specific hydraulic designs.
Material composition trends also reflect changing demand patterns. Cast iron accounts for approximately 41 percent of submersible pump material usage in industrial and municipal applications due to its durability and cost-effectiveness, while stainless steel holds a 34 percent share driven by corrosion resistance. This material distribution indicates that customers are making deliberate trade-offs between initial cost and long-term performance based on their operating environment. As applications extend into more corrosive or abrasive conditions, the demand for advanced materials is likely to grow, pushing manufacturers to expand their material engineering capabilities.
Supply Chain and Cost Structure Dynamics
Cost structures remain a critical factor influencing market competitiveness. Input material pricing, particularly steel, directly affects manufacturing economics and final product pricing. US steel prices are expected to range between $931 and $1,100 per ton by the second quarter of 2026, influenced by tariffs and infrastructure demand. This pricing environment creates both challenges and opportunities. Manufacturers with diversified sourcing strategies, vertical integration, or material optimization expertise can mitigate cost pressures and maintain margin stability. Conversely, companies reliant on single-source procurement or lacking engineering flexibility may face significant margin erosion. The dynamic also encourages innovation in material substitution and design efficiency, as reducing material intensity without compromising performance becomes a competitive differentiator.
Competitive Landscape and Leading Strategies
The market exhibits moderate concentration, with the top three firms capturing approximately 45.5 percent of revenue and the top five firms accounting for 62.3 percent. This concentration indicates a landscape where established players hold significant market share but leave substantial room for specialized competitors and regional specialists. The competitive environment is characterized by a mix of global technology leaders, regional manufacturers with strong cost positions, and niche providers focused on specific applications or material specialties.
Xylem Inc., headquartered in Washington, DC with major operations in Rye Brook, NY, offers a broad portfolio of submersible pumps including the Flygt brand for wastewater, drainage, and industrial and commercial applications. The company's strategic emphasis on solids-handling and energy-efficient designs positions it as a solutions provider for complex wastewater and drainage challenges. Grundfos Holding A/S, based in Bjerringbro, Denmark, provides submersible pumps for commercial wastewater, drainage, and rainwater systems in buildings. Its focus on reliability, high efficiency, and sustainability solutions aligns with regulatory trends and the growing demand for environmentally responsible infrastructure equipment. Sulzer AG, operating from Winterthur, Switzerland, supplies submersible pumps as part of broader fluid engineering solutions for wastewater, industrial processes, and water treatment applications, leveraging its engineering heritage to serve customers requiring integrated system performance.
European manufacturers continue to demonstrate strong product innovation and engineering specialization. KSB SE & Co. KGaA, headquartered in Frankenthal, Germany, manufactures submersible pumps including the CORAChrom stainless-steel range for borehole, dewatering, irrigation, and industrial applications in demanding freshwater and saline environments. The company's recent launches, including axial propeller motor pumps, highlight a strategy centered on continuous hydraulic and material innovation. This approach allows KSB to command premium positioning in applications where performance and durability justify higher initial investment.
North American suppliers are emphasizing application-specific durability and system integration. Franklin Electric Co., Inc., based in Fort Wayne, Indiana, specializes in submersible motors, pumps, and systems including the Pioneer Pump Minetuff series for dewatering and FPS wastewater pumps for sump, effluent, and grinder applications in commercial and industrial settings. The company's recent expansion of its wastewater pump lineup demonstrates a focus on capturing demand from municipal and commercial infrastructure projects that require reliable solids handling and flexible configuration options.
Japanese manufacturers maintain a strong presence through robust design philosophies and global distribution networks. Tsurumi Pump, headquartered in Osaka, Japan with global subsidiaries, produces durable cast-iron submersible pumps for wastewater, dewatering, and sewage, including the AVANT line with anti-clogging hydraulics and explosion-proof options for commercial and industrial use. The company showcased these products at major industry events, reinforcing its commitment to visibility and customer engagement in key markets. Ebara Corporation, based in Tokyo, Japan, offers submersible pumps for water supply, wastewater, and industrial applications with robust designs tailored for global commercial markets, emphasizing reliability and broad applicability.
Specialized industrial suppliers serve demanding segments where abrasive handling and harsh environment performance are critical. Flowserve Corporation, headquartered in Irving, Texas, provides submersible pumps for industrial, oil and gas, and chemical process applications with a focus on reliability in harsh commercial environments. Weir Group PLC, based in Glasgow, Scotland, supplies heavy-duty submersible slurry pumps such as the WARMAN SHW-XTR series for mining and industrial abrasive applications, targeting sectors where conventional pump designs fail under extreme wear conditions. Taian OCEAN Pump Co., Ltd., operating from Taian, Shandong, China, manufactures submersible slurry and sand pumps such as the ZJQ series for industrial, mining, and dredging commercial uses, exporting to over 60 countries. This company represents the growing influence of cost-competitive manufacturers expanding their global footprint through export-oriented strategies.
The competitive landscape is evolving through a combination of consolidation and differentiation. Larger players are acquiring or developing specialized technologies to broaden their application coverage and strengthen their position in high-value segments. At the same time, regional and application-focused manufacturers are carving out sustainable niches by offering tailored solutions, responsive service, and competitive pricing. New entrants face significant barriers related to engineering expertise, regulatory compliance, and established distribution networks, but opportunities exist in underserved regions or specialized applications where incumbent coverage is limited. The trend points toward a market where success depends on balancing scale advantages with the agility to address specific customer requirements.
Future Trends and Predictions
Looking ahead to the 2027 through 2030 period, several interconnected trends will shape the commercial submersible market and create distinct business opportunities. The first major trend is the acceleration of efficiency-driven product evolution. As regulatory standards broaden and customer total cost of ownership calculations become more sophisticated, manufacturers that lead in motor efficiency, hydraulic optimization, and material durability will capture premium market segments. Companies investing in advanced materials, corrosion-resistant alloys, and smart monitoring capabilities will be well positioned to serve applications where downtime costs and environmental compliance are critical. The opportunity lies in developing integrated solutions that combine high efficiency with long service life, reducing lifecycle costs for end users while differentiating from commoditized alternatives.
The second trend is the geographic expansion of demand driven by infrastructure development and urbanization in emerging markets. Regions experiencing rapid industrial growth, water scarcity challenges, and investment in wastewater management will generate sustained procurement activity. Manufacturers that establish local service presence, adapt products to regional operating conditions, and navigate local regulatory requirements will benefit from this expansion. The opportunity extends beyond equipment sales to include maintenance contracts, system upgrades, and performance-based service models that generate recurring revenue and deepen customer relationships. However, competition in these markets will intensify as both global players and regional manufacturers pursue growth, requiring clear value propositions and operational excellence.
The third trend involves the increasing importance of supply chain resilience and cost management as strategic capabilities. With input material prices subject to volatility from tariffs, infrastructure demand, and geopolitical factors, manufacturers must develop flexible sourcing strategies, invest in material efficiency, and explore alternative materials where performance allows. The ability to maintain stable pricing while preserving quality will become a competitive advantage, particularly in price-sensitive commercial segments. At the same time, customers will increasingly value suppliers who can provide transparency, reliable delivery, and risk mitigation support. Companies that integrate supply chain agility with engineering innovation will be better equipped to navigate cost pressures while meeting evolving customer expectations.
Potential risks include regulatory fragmentation that increases compliance complexity, sudden shifts in raw material availability that disrupt production planning, and economic downturns that delay infrastructure investment cycles. Manufacturers and investors should monitor policy developments, material market indicators, and regional infrastructure spending patterns to anticipate changes and adjust strategies proactively.
Commercial Small Batteries Market
Strategic Recommendations for Decision Makers
For manufacturers, the priority should be deepening application-specific engineering capabilities while maintaining cost discipline. Investing in advanced materials, efficiency optimization, and modular design architectures enables companies to serve demanding segments without sacrificing margin stability. Building robust service and support networks, particularly in growth regions, strengthens customer retention and creates opportunities for value-added offerings beyond equipment sales.
For investors, the market presents opportunities in companies with strong technology differentiation, regulatory compliance records, and exposure to infrastructure-driven demand cycles. Evaluating suppliers based on their ability to manage cost volatility, expand into high-growth applications, and maintain competitive positioning in concentrated segments will help identify resilient investment targets. Monitoring recent product launches, trade show presence, and material innovation pipelines provides early signals of competitive momentum.
PW Consulting
For procurement and operations leaders, selecting submersible solutions requires balancing initial cost with lifecycle performance, regulatory compliance, and supplier reliability. Prioritizing manufacturers with proven efficiency credentials, durable material specifications, and responsive service capabilities reduces operational risk and supports long-term cost management. Engaging with suppliers that offer application engineering support and transparent total cost of ownership analysis leads to better procurement decisions aligned with operational goals.
Detailed segmentation data, regional breakdowns, competitive benchmarking, and customized strategic assessments provide the depth required for precise decision making. Accessing comprehensive market intelligence enables stakeholders to validate assumptions, identify underserved segments, and develop targeted strategies that align with evolving market dynamics.
For detailed analysis of this topic, please visit the official page: Worldwide Commercial Submersible Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com