

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Automotive Connectivity Control Unit Platform Market: Why 15.62% CAGR Redefines Future Competition

The Connected Cabin Takes Command: Strategic Shifts in the Global Automotive Connectivity Control Unit Platform Market
Market Snapshot: Growth Trajectory and Structural Tension
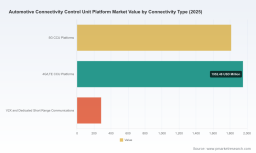
The global automotive connectivity control unit (CCU) platform market has entered a phase of rapid expansion, driven by the critical need to keep vehicles continuously linked to cloud services, telematics infrastructure, and external networks. The sector has grown substantially over the past five years and is projected to maintain a robust annual growth rate through the early 2030s. Valued at roughly 1.8 billion USD in 2020, the market surpassed 4 billion USD by 2025 and is on track to exceed 11 billion USD by 2032. This sustained trajectory reflects a structural shift rather than a temporary surge: automakers are embedding connectivity as a foundational layer of vehicle architecture, moving from isolated infotainment modules to centralized compute platforms that handle data routing, over-the-air updates, and cloud synchronization across the entire vehicle fleet.
This growth, however, operates within a landscape defined by logistical and technological friction. Manufacturers are navigating a period where vehicle intelligence is no longer optional, yet the physical and regulatory constraints of deployment create a pronounced tension between ambition and execution. Several structural challenges are defining the current inflection point.
First, semiconductor reliability remains a persistent vulnerability. Continental automotive controllers and connectivity modules depend on highly specialized chips that are subject to geopolitical and manufacturing disruptions. When key suppliers face interruptions, the ripple effect delays platform launches, disrupts production schedules, and forces engineering teams to redesign around alternative components without compromising performance. The automotive supply chain for electronic control units has proven highly sensitive to single points of failure, and connectivity platforms sit at the center of this dependency. The continued reliance on multi-thousand-chip architectures means that even targeted shortages can bottleneck vehicle assembly lines and delay software-integrated feature rollouts.
Second, the industry is wrestling with architecture consolidation. Traditional centralized domain controllers are giving way to integrated one-board, one-chip computing units that house multiple functions in a single physical envelope. While this shift reduces size and weight, improves thermal management, and simplifies wiring complexity, it introduces new validation and supply demands. Engineers must prove that consolidated platforms meet safety, security, and performance standards across multiple domains simultaneously, and suppliers must rethink validation cycles, testing protocols, and certification pathways. The engineering effort to merge connectivity, compute, and control functions onto unified hardware is substantial and changes the economics of platform development.
Third, the global regulatory mosaic around digital keys, V2X communication, and cybersecurity is still maturing. Organizations pushing for unified standards are advancing the conversation, but compliance remains fragmented across regions. Manufacturers deploying connectivity platforms must balance the pressure to introduce features quickly with the need to satisfy differing certification regimes, data governance expectations, and interoperability requirements. Platforms that work seamlessly in one market can face architectural or certification hurdles in another, making global scalability a material execution challenge.
These factors collectively shape a market that is expanding rapidly but demanding more sophisticated execution. The winning platforms will be those that can deliver connectivity capacity, secure data handling, and architecture flexibility without becoming choke points in the broader vehicle development and supply chain.
Key Drivers of Change: Technology, Policy, Demand, and Supply Dynamics
The expansion of the CCU platform market is propelled by a convergence of forces that are reshaping how vehicles are designed, validated, and monetized after sale. The most influential driver is the evolution of hardware and software architecture toward integrated connectivity-centric compute. The industry is shifting toward one board and one chip solutions that consolidate connectivity, domain control, and data processing into a single platform. This consolidation compresses the physical footprint of central computing units, reduces weight and wiring complexity, and streamlines thermal and power management. For automakers, the operational benefit is clear: fewer discrete modules mean simpler integration, faster development cycles, and more efficient update delivery. Connectivity platforms embedded in centralized architectures also become the strategic hub for over-the-air updates, fleet telemetry, and cloud-based service layers, turning connectivity into a platform for long-term vehicle value rather than a standalone feature.
Policy and standardization activity is the second major driver. Governments and industry bodies are moving toward unified frameworks for digital keys, vehicle-to-everything communication, and connected service interoperability. These efforts are reducing uncertainty for manufacturers who need to deploy features across multiple markets without rebuilding connectivity architectures for each regulatory environment. As standards around secure access, authentication, and external communication gain traction, platforms that can align with global certification pathways gain a distinct advantage. At the same time, regulatory attention to cybersecurity and data handling is raising the bar for connectivity modules, pushing manufacturers to design security and data governance into the platform layer rather than layering it on after the fact. This shift makes secure, standards-aligned connectivity hardware and software a market prerequisite rather than a differentiator.
Consumer and enterprise demand is reshaping the value proposition of connected platforms from both ends of the vehicle lifecycle. On the consumer side, expectations for seamless connectivity, remote diagnostics, subscription-based services, and intelligent digital access are accelerating. Digital key adoption, telematics-enabled features, and cloud-managed vehicle services are moving from niche offerings to mainstream expectations. On the enterprise side, fleet operators and mobility providers are demanding telemetry, asset tracking, remote diagnostics, and centralized management capabilities that scale across large vehicle populations. These use cases push connectivity control units beyond passenger convenience toward fleet intelligence, predictive maintenance, and operational optimization. As vehicles become data-generating assets, the connectivity layer becomes the interface between the vehicle and the services that extract value from that data.
Supply chain structure and cost dynamics are also acting as a catalyst for platform strategy. The average vehicle relies on over a thousand semiconductor components, and the connectivity stack sits at the intersection of this dependency. Manufacturers are actively rethinking how connectivity modules are sourced, integrated, and validated to reduce exposure to single-supplier risk and component volatility. This has encouraged a wave of platform thinking that prioritizes modularity, standardized interfaces, and forward-compatible architectures that can accommodate evolving chip roadmaps without full redesigns. Cost structures are further influenced by the move toward integrated compute, which can reduce bill-of-materials complexity when executed well, but demands careful engineering to avoid performance or security trade-offs. The net effect is that connectivity platforms are no longer evaluated solely on bandwidth or communication protocol support; they are increasingly assessed on their ability to anchor broader vehicle architecture, withstand supply disruption, and support long-term service monetization.
Competitive Landscape and Strategic Positioning
The competitive environment is defined by a mix of established tier-one suppliers, technology-rich electronics manufacturers, and software-focused entrants that are expanding their footprint in centralized connectivity architectures. A handful of global players collectively hold the largest share of platform revenue, while a broader group of specialists competes on regional expertise, software integration, and domain-specific capabilities. The market is neither fully consolidated nor fragmented; it is evolving toward a structure where scale in hardware integration matters, but differentiation increasingly comes from how connectivity platforms interface with software, cloud services, and vehicle architectures.
A core group of established players is positioning connectivity control as the bridge between hardware and cloud-connected vehicle services. Leading global tier-one suppliers are offering connectivity hubs and control units that serve as central hardware for vehicle-to-cloud communication, data collection, OTA management, and third-party application integration. These platforms are designed to operate across passenger and commercial vehicles, and they increasingly embed 5G and V2X capabilities to support smart connectivity and software-defined vehicle architectures. Their strengths lie in broad engineering scale, established supplier relationships, and deep integration experience across vehicle domains. For automakers, these platforms reduce integration risk because they come from suppliers with proven automotive validation pipelines and broad service portfolios. The trade-off is that differentiation often comes from integration depth and reliability rather than sweeping architectural innovation, which places pressure on these players to keep pace with more aggressive consolidation trends.
Electronics and software-oriented manufacturers are pursuing a different strategic angle. Some are building connectivity solutions that combine telematics control with infotainment, cloud connectivity, and emerging communication modalities such as satellite support. Others are focusing on advanced 5G-based telematics and AI-enabled connectivity features for premium and luxury vehicles. A distinct segment of players is concentrating on safe, secure connectivity hardware and software stacks optimized for intelligent mobile computing platforms, emphasizing platform security and integration of connectivity control with broader vehicle operating environments. These entrants are often faster to adapt to emerging communication capabilities because their roadmaps are tightly coupled to software and connectivity innovation rather than traditional hardware cycles. Their strategic advantage is the ability to create platforms that feel modern and software-forward, appealing to automakers pursuing aggressive digital transformation and next-generation user experiences.
PW Consulting
The recent developments in the market illustrate how quickly these strategic positions are being tested. Technology unveilings at major events have highlighted next-generation connectivity platforms that compress functionality into tighter hardware footprints and emphasize advanced communication support. Partnerships are increasingly combining connectivity hardware with external technology partners to extend capability, particularly around non-terrestrial network support and cloud-connected telematics. Meanwhile, automakers are pushing centralization further by unveiling centralized compute platforms that consolidate connectivity functions alongside high-performance processing for electric and conventional vehicles. These moves signal that connectivity hardware is moving closer to the center of vehicle compute strategy, not just sitting alongside it. Standard-setting bodies are also actively advancing unified frameworks for digital keys, fleet management use cases, and broader connectivity interoperability, which is gradually reducing the fragmentation risk that has historically complicated global platform deployment.
The market is evolving along two simultaneous vectors. Integration is accelerating at the hardware level, as consolidation reduces size, weight, and complexity while increasing the strategic importance of the central connectivity compute node. At the same time, differentiation is widening in the software and services layer, where the ability to manage updates, telemetry, security, and third-party applications determines commercial value over the vehicle lifecycle. New entrants with strong software and connectivity expertise are gaining traction in premium and tech-forward segments, while established players are leaning on scale, integration breadth, and supplier relationships to defend their position. The most probable outcome is continued enterprise-level consolidation among platform suppliers, paired with a rich ecosystem of software, cloud, and service innovation layered on top of the core connectivity hardware.
Forward Outlook: Three Shifts That Will Define the Next Three to Five Years
The next few years will likely be shaped by three overlapping trends that turn connectivity platforms from communication components into core elements of vehicle value architecture. The first is the deepening integration of connectivity into centralized and zonal compute platforms. As automakers move toward unified compute environments, connectivity control units will increasingly sit at the center of vehicle data flow, OTA governance, and cloud-facing services. This will expand the role of connectivity hardware from enabling communication to enabling fleet intelligence, software monetization, and remote service orchestration. The commercial opportunity lies in platforms that can anchor these functions with reliable performance, strong security, and architecture flexibility that adapts as vehicle compute strategies evolve.
Worldwide Car Audio Head Units Market
The second trend is the widening reach of communication modalities beyond traditional cellular networks. Satellite-enabled telematics and broader communication support are beginning to complement terrestrial networks, especially for areas where continuous connectivity is critical or where network coverage is uneven. This is creating new use cases for fleet tracking, remote diagnostics, and service continuity, and it is pushing connectivity platforms to support a more diverse set of communication pathways. Platforms that can integrate multiple communication options without adding excessive complexity will have a clear advantage. The risk is that expanded communication support increases integration and certification complexity, particularly where standards across communication modalities and regional regulations are still maturing.
The third trend is the shift toward unified standards and secure digital access frameworks that reduce fragmentation and accelerate global deployment. As interoperability expectations grow around digital keys, V2X, and connected service access, platforms aligned with global standards will gain preference because they lower the cost and risk of cross-market rollout. This trend favors suppliers that can demonstrate both technical capability and compliance readiness. The uncertainty remains where regulatory timelines diverge and where cybersecurity expectations continue to evolve. Platforms that lag in security-by-design or lack a clear path to standard alignment will face increasing friction as the market matures and enterprise buyers demand more predictable compliance postures.
Telematics Control Unit (TCU) Market
Together, these trends point to a market where connectivity platforms become strategic assets for long-term vehicle value. The upside is significant: more capable platforms enable richer services, stronger fleet intelligence, and more resilient communication architectures. The risk lies in execution complexity, supply chain sensitivity, and the pace at which standards and security expectations become mandatory rather than aspirational.
Actionable Moves for Decision-Makers
Automakers and vehicle platform architects should treat connectivity control units as central architecture components rather than peripheral modules. Prioritizing integrated compute and connectivity platforms that support consolidated hardware, secure OTA governance, and flexible communication options will reduce long-term integration risk and better position vehicles for service monetization. Building validation and certification roadmaps around emerging unified standards will also shorten the path to global deployment and reduce region-by-region rework. Procurement teams should focus on platform suppliers that demonstrate supply resilience, security-by-design, and a clear path to forward-compatible chip and software roadmaps, since these attributes will determine how well a connectivity platform withstands disruption and scales over the vehicle lifecycle.
Investors and strategy teams should evaluate connectivity platform exposure through the lens of architecture centrality. The most durable commercial value will accrue to platforms that sit at the intersection of communication, software update, telemetry, and secure cloud connectivity, particularly as centralized compute becomes the norm. Companies that can combine hardware integration strength with fast-moving software and connectivity capabilities are well placed to capture value in premium and tech-forward segments, while established players with broad integration footprints remain attractive for scale deployment and standardization alignment. Portfolio decisions should weigh not just current platform capability but also the supplier's ability to adapt to one-board consolidation, multi-modal communication, and unified compliance expectations over the next several years.
The pace of change in connectivity architectures, communication modalities, and standards alignment makes detailed, segment-level intelligence a practical necessity rather than a nice-to-have. Decision-makers who need granular views by platform type, vehicle class, region, supplier positioning, and supply chain exposure will benefit from full research coverage that translates these dynamics into actionable planning data. Comprehensive research can help teams validate assumptions, compare supplier strategies, and map commercial opportunities against the market trajectory and regional nuances that shape deployment decisions.
For detailed analysis of this topic, please visit the official page: Worldwide Automotive Connectivity Control Unit Platform Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com