

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Worldwide Lung Cancer Test Kit Market: 8.2% CAGR and 2026 Growth Drivers

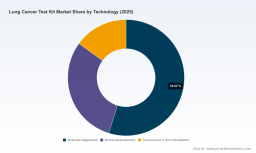
Global Lung Cancer Test Kit Market: Strategic Trends and Commercial Opportunities Through 2032
Market Overview: Navigating Growth Amid Structural Challenges
The global lung cancer diagnostic testing market has demonstrated sustained expansion, valued at approximately $2.15 billion in 2025 and projected to reach $3.73 billion by 2032, reflecting a compound annual growth rate of 8.2 percent. This trajectory underscores a sector transitioning from established diagnostic paradigms toward increasingly sophisticated, molecular-driven testing frameworks. Historical performance from 2020 through 2025 reveals consistent upward momentum, with revenues climbing from $1.45 billion to the current valuation, driven by rising incidence rates, expanded screening eligibility, and the proliferation of targeted therapy pipelines. The forecast horizon through 2032 suggests that this growth will not merely continue but accelerate as diagnostic workflows become more integrated with clinical decision-making pathways.
Despite the favorable macroeconomic indicators, the industry confronts several structural inflection points that will define competitive positioning in the coming years. First, the regulatory landscape remains fragmented across jurisdictions, creating uneven market access for innovative assays. While certain companion diagnostics have secured formal clearance in major markets, others operate within laboratory-developed test frameworks that face increasing scrutiny regarding standardization and reimbursement alignment. This duality creates a bifurcated commercial environment where speed-to-market advantages must be carefully balanced against long-term regulatory sustainability.
Second, the market exhibits moderate concentration dynamics, with the top three participants collectively commanding roughly 48 percent of total revenue and the top five firms controlling approximately 62 percent. This structure provides scale advantages to established players in manufacturing, distribution, and clinical validation, yet simultaneously leaves substantial whitespace for specialized innovators who can address unmet needs in early detection, minimal residual disease monitoring, or niche molecular subsets. The concentration pattern suggests that consolidation will likely continue, but targeted acquisitions of clinically differentiated technologies may prove more valuable than broad portfolio expansion.
Worldwide In Vitro Lung Model Market
Third, reimbursement frameworks are evolving but remain inconsistent, particularly for non-invasive or multi-analyte testing approaches that fall outside traditional coding structures. While certain screening programs have established coverage pathways, the translation of diagnostic innovation into sustainable commercial adoption depends heavily on demonstrating clinical utility that aligns with payer expectations. Organizations that proactively engage with health economics evidence generation and real-world data collection will be better positioned to navigate this complexity.
Key Drivers Reshaping the Competitive Landscape
Technological Innovation and the Shift Toward Multi-Analyte Profiling
The most pronounced driver of market evolution is the rapid advancement in molecular diagnostics, which has transitioned from single-gene mutation detection to comprehensive genomic profiling and multi-modal testing strategies. Next-generation sequencing platforms now enable simultaneous analysis of multiple actionable variants, reducing turnaround times and improving the probability of identifying targetable alterations in non-small cell lung cancer patients. This technological maturation is not merely an incremental improvement; it fundamentally alters the clinical value proposition of testing by expanding the addressable patient population and supporting sequential therapy selection as resistance mechanisms emerge.
Recent regulatory milestones illustrate how innovation translates into commercial viability. The approval of next-generation sequencing-based companion diagnostics for specific epidermal growth factor receptor exon 20 insertion mutations demonstrates how assay development increasingly aligns with precision oncology drug pipelines. Similarly, artificial intelligence-enhanced computational pathology tools have received breakthrough device designations, signaling a broader industry shift toward digital and algorithmic augmentation of traditional tissue-based diagnostics. These developments suggest that future competitive advantage will depend less on proprietary single-test formats and more on integrated diagnostic ecosystems that combine molecular, immunohistochemical, and imaging-based insights.
Regulatory Evolution and Companion Diagnostic Integration
Regulatory frameworks are increasingly converging around the principle that diagnostic tests must be developed in tandem with therapeutic candidates, particularly in oncology where biomarker-driven patient stratification directly influences treatment efficacy. Multiple next-generation sequencing and polymerase chain reaction-based assays have received formal clearance or approval as companion diagnostics with specific claims tied to targeted therapy indications. This regulatory normalization reduces uncertainty for manufacturers and healthcare providers, but it also raises the barrier to entry for novel formats that lack established clinical validation pathways.
At the same time, laboratory-developed tests continue to play a critical role in filling gaps where commercial assays have not yet secured formal clearance. Tests utilizing flow cytometry-based sputum analysis or DNA methylation detection from non-invasive sample types illustrate how innovators are pursuing alternative biological matrices to address early detection and high-risk population screening. The coexistence of cleared companion diagnostics and laboratory-developed offerings creates a dynamic where reimbursement strategy, clinical evidence standards, and laboratory accreditation requirements become decisive commercial factors rather than secondary considerations.
Demand-Side Shifts Driven by Screening Expansion and Precision Medicine Adoption
Demand dynamics are being reshaped by two interrelated forces: expanded eligibility for lung cancer screening and the growing expectation that diagnostic testing should inform personalized treatment pathways. Low-dose computed tomography screening programs have established coverage for eligible beneficiaries within specified age and smoking history parameters, supported by specific procedural coding for both the imaging scan and the accompanying shared decision-making consultation. This structured reimbursement environment encourages broader screening uptake, which in turn generates downstream demand for confirmatory and molecular diagnostic testing when suspicious findings are identified.
PW Consulting
Beyond screening, the clinical momentum behind precision oncology continues to drive demand for comprehensive biomarker assessment at the time of diagnosis and throughout the treatment continuum. Oncology practices increasingly expect testing solutions that can detect not only established mutations but also emerging resistance alterations and co-occurring genomic events that may influence therapeutic sequencing. This expectation places pressure on manufacturers to deliver assays with broad analytical ranges, robust performance across varied specimen types, and compatibility with existing laboratory workflows. End users ranging from large hospital systems to specialized diagnostic laboratories are prioritizing solutions that minimize sample consumption, reduce hands-on time, and provide clear interpretive reporting that supports clinical actionability.
Circulating Tumor Cells Market
Supply Chain Dynamics and the Pursuit of Cost-Effective Scalability
Cost structures and supply chain resilience have emerged as increasingly important considerations, particularly as testing volumes expand and laboratories seek to manage per-test economics without compromising analytical quality. The shift toward automated sample preparation, standardized reagent formats, and integrated instrumentation reduces variability and labor intensity, but it also requires upfront capital investment and vendor lock-in considerations. Organizations that can offer scalable platforms with flexible throughput options will find stronger adoption in settings where testing demand fluctuates across regions or clinical programs.
Additionally, the geographic distribution of manufacturing and distribution capabilities influences market access, regulatory compliance, and time-to-result performance. Companies with established global operations benefit from diversified supply networks and deeper relationships with centralized testing facilities, while regional players may gain advantage by tailoring solutions to local regulatory requirements, sample logistics, and reimbursement environments. The interplay between centralized high-complexity testing and decentralized point-of-care or regional laboratory models will continue to shape how testing capacity is deployed and how commercial value is captured.
Competitive Dynamics and Strategic Positioning
The competitive environment reflects a blend of large diversified diagnostics organizations, focused molecular testing specialists, and emerging entrants pursuing novel detection modalities. Leading firms have secured positions by aligning their assay portfolios with high-prevalence biomarker targets and by securing regulatory clearances that facilitate integration into standard oncology workflows. For example, established manufacturers offer companion diagnostic assays for epidermal growth factor receptor mutation testing and programmed death-ligand 1 immunohistochemistry, both of which remain foundational to non-small cell lung cancer patient stratification. These products benefit from extensive clinical validation datasets, established ordering patterns, and integration with broader instrumentation ecosystems.
Other major participants have emphasized comprehensive genomic profiling through tissue and liquid biopsy formats, positioning their offerings as tools for broad biomarker discovery rather than single-target detection. This strategy supports clinical scenarios where multiple therapeutic options may be relevant or where tissue availability is limited. By expanding claims across several targeted therapies, these comprehensive tests seek to become default testing options at diagnosis, creating stickiness through breadth of coverage and compatibility with evolving treatment guidelines.
Smaller and mid-sized companies are pursuing differentiation through specialized technologies or alternative sample types. Next-generation sequencing kit developers are focusing on streamlined workflows and targeted panels that balance breadth with cost efficiency. Flow cytometry-based sputum tests and DNA methylation assays derived from urine or blood represent efforts to capture early detection opportunities and to serve populations where invasive sampling is less feasible. While some of these approaches operate within laboratory-developed test frameworks rather than cleared companion diagnostic pathways, they reflect a broader industry recognition that early detection and minimal residual disease monitoring represent substantial unmet needs.
Strategic positioning among leading organizations tends to cluster around three models. The first emphasizes platform breadth and regulatory clearance volume, leveraging scale to maintain visibility across multiple biomarker domains. The second focuses on deep clinical evidence generation and guideline alignment, ensuring that specific assays are embedded in recommended testing algorithms. The third pursues technological differentiation through artificial intelligence integration, novel sample types, or workflow automation that reduces laboratory burden. Each model carries distinct risk-reward profiles: platform breadth supports cross-selling and resilience but may dilute focus; evidence-driven positioning builds clinical credibility but requires sustained investment; technological differentiation can create temporary monopolies but faces rapid replication risk.
Market evolution is likely to feature continued consolidation among scaled players seeking to acquire differentiated technologies, alongside selective partnerships between assay developers and pharmaceutical companies to co-develop companion diagnostics alongside new therapeutic candidates. Geographic expansion will remain uneven, with regions that have established screening infrastructure and reimbursement clarity attracting more rapid adoption. New entrants will need to demonstrate not only analytical performance but also clear pathways to reimbursement, laboratory adoption, and clinical guideline inclusion to achieve commercial traction.
Future Outlook: Key Trends and Strategic Implications
Over the next three to five years, several trends will likely define the market trajectory. First, multi-analyte and multi-modal testing will become increasingly standard, as clinicians seek consolidated insights that combine genomic, proteomic, and imaging-derived data. This convergence will pressure manufacturers to develop interoperable reporting formats and to demonstrate that integrated testing improves decision-making efficiency or patient outcomes compared with sequential single-test approaches. Organizations that invest early in data integration frameworks and interpretive software may capture disproportionate value as laboratories consolidate testing workflows.
Second, artificial intelligence and computational pathology will move from regulatory novelty to operational expectation, particularly in screening triage and tissue analysis. AI-assisted interpretation tools have already received notable regulatory designations, and their adoption will likely accelerate as laboratories face workforce constraints and rising sample volumes. The commercial opportunity lies not only in the software itself but in the broader ecosystem of training, validation, and quality assurance services that accompany deployment. Companies that can provide end-to-end implementation support, including local adaptation and performance monitoring, will differentiate beyond pure algorithm accuracy.
Third, non-invasive and liquid-based testing formats will continue to gain relevance, especially for early detection, treatment monitoring, and scenarios where tissue procurement is challenging. While cleared companion diagnostics will remain essential for therapy selection, the growth of laboratory-developed and minimally invasive options reflects demand for broader access and repeated sampling capabilities. The strategic risk involves variable reimbursement coverage and the need to generate robust clinical utility evidence that satisfies both payer and guideline-setting bodies. Firms that can bridge the gap between innovative sample types and established evidentiary standards will be best positioned to convert technological promise into sustainable revenue.
Potential uncertainties include regulatory shifts affecting laboratory-developed test oversight, changes in screening eligibility or reimbursement policies, and the pace at which novel biomarkers translate into routine clinical practice. Competitive intensity may also compress margins as platforms mature and differentiation narrows. These risks do not diminish the overall growth outlook but emphasize the importance of strategic agility and evidence-driven commercial planning.
Actionable Guidance for Decision Makers
For diagnostic manufacturers, the priority should be to align product development with emerging clinical workflows rather than pursuing isolated technical advances. This means investing in interpretive reporting, workflow integration, and evidence generation that supports both regulatory clearance and payer acceptance. Partnerships with academic centers and community oncology networks can accelerate real-world data collection and strengthen guideline inclusion prospects. Companies should also evaluate whether their portfolio strategy favors breadth across biomarkers or depth in specific high-value niches, recognizing that the optimal choice depends on manufacturing capabilities, regulatory expertise, and target end-user profiles.
For investors, due diligence should extend beyond assay performance claims to include reimbursement pathway viability, laboratory adoption economics, and the sustainability of competitive moats. Technologies with clear companion diagnostic alignment or strong biomarker-therapy linkage typically offer more predictable adoption curves, while early detection and multi-cancer approaches may offer higher upside but require longer evidence-building horizons. Evaluating management teams on their ability to navigate regulatory transitions and to build commercial infrastructure in key regions can provide early signals of execution risk or advantage.
For procurement leaders and laboratory operators, sourcing decisions should weigh total cost of ownership against clinical utility and future-proofing potential. Platforms that can accommodate evolving biomarker panels, integrate with existing information systems, and support both high-complexity and decentralized testing models will reduce the risk of premature obsolescence. Establishing performance monitoring protocols and participating in multi-site validation studies can also strengthen negotiating positions and ensure that purchased solutions remain aligned with changing clinical guidelines.
The complexity of this market underscores the value of access to granular segmentation data, regional reimbursement maps, and company-level competitive benchmarking. Detailed research that breaks down technology adoption curves, end-user procurement patterns, and regulatory status tracking can inform more precise entry timing, pricing strategy, and partnership targeting. For organizations seeking to translate these strategic themes into operational decisions, comprehensive market intelligence remains a critical enabler of disciplined execution.
For detailed analysis of this topic, please visit the official page: Worldwide Lung Cancer Test Kit Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com