

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Worldwide RNA Cleanup Market: Why 8.85% CAGR and NGS Demand Redefine Growth

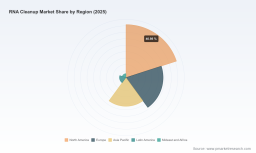
Strategic Trends and Commercial Opportunities in the Global RNA Cleanup Market
Market Landscape and Core Challenges
The worldwide RNA cleanup market has grown substantially over the past five years, expanding from approximately USD 345.5 million in 2020 to USD 525.0 million in 2025. This trajectory reflects a compound annual growth rate of 8.85 percent, with projected revenue reaching USD 950.5 million by 2032. The sustained expansion underscores the critical role of RNA purification and cleanup in contemporary molecular biology, diagnostics, and therapeutic development. As downstream applications grow more demanding in terms of RNA integrity, purity, and throughput, the cleanup step has evolved from a routine laboratory procedure to a strategic component of workflow design.
Two structural challenges currently shape market dynamics. The first centers on supply chain fragility for essential consumables. Silica membranes and magnetic beads, which form the backbone of most commercial cleanup kits, are predominantly sourced from a concentrated set of manufacturers in China and Japan. In 2024, these core materials experienced delivery delays of up to twelve weeks as production capacity was redirected toward semiconductor applications. Such disruptions have forced end users to recalibrate experimental timelines, while reagent suppliers have had to manage inventory volatility and cost pass-through pressures, with certain RNA purification reagents seeing price increases of up to five hundred percent during peak demand periods tied to global testing surges.
The second challenge involves an increasingly complex regulatory environment. FDA and EMA guidance documents now emphasize stringent characterization of RNA integrity, purity, and physicochemical properties for therapeutic applications, including the cleanup processes themselves. Simultaneously, the EU Single-Use Plastics Directive requires vendors to transition RNA cleanup columns to recyclable polypropylene, extending product development cycles by up to nine months. These converging requirements elevate compliance costs and slow time-to-market for reformulated products, particularly for companies that must align research-grade offerings with emerging clinical-grade expectations.
PW Consulting
A third, more structural pressure relates to market concentration. The top three firms account for roughly forty-eight percent of revenue, while the top five capture nearly sixty-three percent. This concentration confers scale advantages to incumbent suppliers but also creates dependency risks for laboratories and manufacturers that rely on a limited set of validated consumables. For firms outside the leading tier, breaking into established procurement cycles requires differentiated performance claims, regulatory readiness, or workflow integration that transcends commodity pricing competition.
Key Drivers Shaping Market Trajectory
Several interconnected forces are driving the market toward higher value and more specialized offerings. Understanding these drivers clarifies where investment and product strategy should be directed.
Technological innovation in purification formats continues to reshape competitive positioning. Magnetic bead-based cleanup has gained substantial traction because it aligns naturally with automated liquid handling, reduces hands-on time, and supports scalable processing for high-throughput environments. Silica-based spin columns remain widely used for their reliability and low barrier to adoption, but the incremental advantage increasingly belongs to platforms that can deliver consistent recovery and inhibitor removal across varied input types. Recent product launches illustrate this shift, such as magnetic bead-based total RNA purification kits capable of automated, high-purity extraction in approximately fifteen minutes. These developments signal a market preference for speed, reproducibility, and compatibility with integrated instrumentation rather than standalone consumables alone.
Demand-side expansion from genomics and advanced transcriptomics is another major driver. Next-generation sequencing, in vitro transcription, and RT-PCR/qPCR applications represent the largest end-use categories, each imposing distinct requirements on RNA cleanup. NGS workflows demand high integrity and low contaminant carryover to protect library quality, while in vitro transcription applications require efficient removal of enzymes, nucleotides, and buffer components that can interfere with downstream reactions. The rise of spatial biology has further intensified these requirements. Recent portfolio updates extending RNA purification into spatial biology workflows, combined with collaborative efforts linking RNA purification elements to spatial transcriptomics solutions with major sequencing platforms, demonstrate how cleanup is being embedded into specialized, high-value applications rather than treated as a generic preparatory step.
Regulatory and quality expectations are raising the performance bar. For research-grade use, consistency and lot-to-lot reproducibility matter increasingly as experiments scale. For therapeutic and clinical contexts, regulators are focusing on RNA integrity, purity, and physicochemical characterization throughout the manufacturing chain. This is pushing suppliers to document process controls more rigorously and, in some cases, move toward GMP-compliant raw materials and processes. The constraint is tangible: GMP-compliant raw materials for RNA-related processes face supply limitations that can restrict large-scale therapeutic manufacturing. Companies that can provide well-characterized, compliant inputs while maintaining scalability are positioned to capture premium segments of the market.
Cost structure and sourcing strategy are becoming strategic levers. The concentration of critical raw materials in a small number of geographies, combined with periodic demand spikes, has exposed vulnerability in the supply chain. Some reagent categories have experienced significant price volatility during peak periods, and delivery delays can cascade into research delays and clinical program slippage. In response, leading suppliers and large end users are exploring dual sourcing, inventory buffering, and workflow designs that reduce dependence on single consumable types. At the same time, regulatory mandates for recyclable materials add reformulation costs and extend development timelines. These pressures are compressing margins for undifferentiated products while rewarding suppliers that can balance performance, compliance, and reliable supply.
Competitive Landscape and Leading Strategies
The market features a mix of large, broadly positioned life science companies and specialized suppliers with strong technical reputations. Thermo Fisher Scientific and QIAGEN anchor the upper tier with comprehensive kit portfolios and strong integration into both manual and automated workflows. Thermo Fisher’s offerings span RNA cleanup and concentration for post-enzymatic reactions and in vitro transcription workflows, supported by magnetic bead-based systems designed for high-yield processing. QIAGEN’s RNeasy series, including cleanup kits that enable small elution volumes and inhibitor removal, is well established for total RNA and miRNA applications, with compatibility across manual and automated protocols.
Mid-tier and specialized firms compete on performance specificity, recovery claims, and workflow fit. New England Biolabs offers spin RNA cleanup kits in multiple binding capacities tailored to rapid silica-based cleanup after IVT, labeling, or enzymatic reactions, emphasizing high recovery and purity suitable for NGS and RT-qPCR. Zymo Research provides RNA clean and concentrator kits in multiple formats, including magnetic bead versions, targeting rapid cleanup, concentration, and inhibitor removal from diverse inputs. Norgen Biotek uses silicon carbide technology for phenol-free isolation and cleanup across RNA sizes, with options for high-throughput and cell-free RNA applications. Promega, Omega Bio-tek, Agilent, Roche, Merck KGaA, Takara Bio, and Bio-Rad each contribute differentiated positions, from automated system support and integrated nucleic acid purification to workflow-specific reagents tied to NGS and spatial transcriptomics.
Leading companies are pursuing three strategic directions. First, automation and throughput . Magnetic bead systems and kit formats that integrate with liquid handlers reduce variability and labor, which is increasingly valuable in screening, clinical labs, and process development environments. Second, workflow integration . Suppliers are aligning cleanup products with adjacent steps such as in vitro transcription, library preparation, and spatial biology, making the cleanup step part of a coherent solution rather than an isolated purchase. Recent collaboration and portfolio moves that connect RNA purification to spatial transcriptomics workflows illustrate this integration mindset. Third, regulatory readiness and material consistency . As therapeutic and diagnostic applications grow, suppliers that can provide documented purity, integrity, and process controls gain advantage in higher-stakes procurement decisions.
Cleaning Indicator Market
The competitive landscape is evolving through a combination of consolidation pressure and segmentation. Large incumbents benefit from broad distribution, established relationships, and the ability to bundle cleanup products with instrumentation and reagents. Specialized players can compete by targeting high-recovery claims, niche input types, or specific workflow constraints such as extremely low elution volumes or inhibitor-rich samples. Market entry is possible but challenging because validation cycles in laboratory and clinical settings are long, and switching costs rise when cleanup performance is linked to downstream assay reliability. Over time, expect further consolidation among mid-tier suppliers, alongside continued differentiation by application-specific performance and automation compatibility.
Future Trends and Commercial Implications
Several trends are likely to define the market over the next three to five years.
Automation-compatible, high-recovery formats will become the default expectation for many end users. Magnetic bead-based approaches and kit designs that minimize hands-on time, standardize elution volumes, and integrate with robotic workflows will see continued adoption, particularly in high-throughput genomics and diagnostics. Commercial opportunity lies in pairing consumables with instrument compatibility, application-specific protocols, and validated performance claims that reduce user optimization time.
Application specialization will deepen. As spatial transcriptomics, advanced in vitro transcription, and NGS-based workflows expand, cleanup requirements will diverge by application. Suppliers that tailor binding capacity, inhibitor removal, and recovery profiles to specific downstream processes can command stronger positioning than those offering generic solutions. This creates room for targeted product development and partnership strategies that embed cleanup into broader workflow ecosystems.
Regulatory and sustainability requirements will reshape product roadmaps. Stricter RNA characterization expectations for therapeutic use and directives pushing recyclable materials will extend development cycles and increase compliance costs. Firms that proactively invest in reformulated consumables, well-characterized raw materials, and documentation suitable for clinical and GMP-adjacent contexts will be better placed to participate in higher-value segments. The risk is that these same requirements can slow innovation pace and raise barriers for smaller players, potentially accelerating concentration among suppliers with stronger regulatory and manufacturing capabilities.
Underlying uncertainties include raw material availability, geopolitical sourcing risks, and the pace at which therapeutic RNA programs scale their manufacturing needs. Price volatility in key reagents and periodic supply constraints can disrupt both research timelines and commercialization schedules. Companies should therefore weigh performance advantages against supply resilience and compliance readiness when evaluating long-term positioning.
Oligonucleotide Purification Market
Actionable Guidance for Decision Makers
Strategic responses should be tailored to each stakeholder’s role in the value chain.
- For manufacturers and suppliers: Prioritize automation-compatible formats and application-specific performance claims, while investing in regulatory documentation and sustainable material transitions. Diversify sourcing for critical components such as silica membranes and magnetic beads to reduce exposure to delivery delays and price spikes. Where feasible, embed cleanup products into broader workflow solutions to increase switching costs and reinforce value beyond unit pricing.
- For investors: Focus on companies with differentiated purification technologies, credible recovery and purity data, and the operational capacity to support automation and compliance demands. Evaluate exposure to raw material concentration risk and assess whether portfolio integration, partnerships, or scale advantages provide durable moats in a market where validation cycles are long and procurement is sticky.
- For procurement and laboratory leaders: Treat RNA cleanup as a workflow-critical input rather than a commodity. Build evaluation criteria around recovery consistency, inhibitor removal, elution volume control, and compatibility with automation or downstream applications. Strengthen supply continuity through dual sourcing, safety stock for critical consumables, and supplier qualification that accounts for regulatory trajectory and material sustainability requirements.
The strategic stakes in this market are rising as cleanup moves closer to high-value applications and more stringent quality expectations. Detailed segment-level data, supplier benchmarking, and tailored scenario analysis can sharpen planning and reduce execution risk. For teams seeking deeper granularity on regional dynamics, methodology splits, application-specific demand patterns, and competitive positioning, the full PW Consulting report provides a comprehensive foundation for decision-making and customized recommendations.
For detailed analysis of this topic, please visit the official page: Worldwide RNA Cleanup Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com