

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Worldwide Infrastructure as a Service Market: The 21% CAGR and Concentration Shift

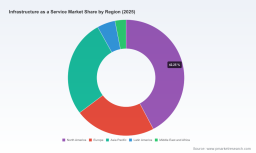
The Infrastructure as a Service Revolution: Navigating Trillion-Dollar Scale and Strategic Complexity
Market Landscape and Core Challenges
The worldwide Infrastructure as a Service (IaaS) market has entered a phase of unprecedented expansion, fundamentally altering how organizations procure and manage computing resources. From a base valuation in the early 2020s, the sector has demonstrated resilience and accelerating growth, driven by the irreplaceable role cloud infrastructure now plays in digital transformation. The trajectory suggests a market moving beyond early adoption curves into a mature, high-velocity phase where scale brings both opportunity and structural friction. Growth rates indicate that the sector is compounding at a pace that outstrips many traditional technology segments, signaling that IaaS is no longer a supporting utility but a primary engine of enterprise value creation.
Despite the broad upward momentum, the industry faces three critical inflection points that will define competitive outcomes over the next several years. First, concentration risk remains pronounced. A small group of hyperscale providers commands a dominant share of global revenue, creating a landscape where customer leverage is asymmetrical and switching costs remain high. This concentration creates vulnerability for enterprises reliant on single-vendor strategies, while simultaneously raising antitrust and regulatory scrutiny in multiple jurisdictions. The market structure rewards scale, but it also invites challenges around interoperability and vendor lock-in that are becoming harder for buyers to ignore.
Second, the energy and physical infrastructure bottleneck is transitioning from a background concern to an active constraint on capacity planning. The rapid proliferation of AI-driven workloads has pushed data center power demand into new territory, straining regional grids and altering the economics of site selection. Where cloud expansion was once limited primarily by capital and fiber availability, it is now increasingly bound by electrical capacity, cooling technology, and local permitting timelines. For providers, this means that growth trajectories must be recalibrated against grid reality. For enterprises, it introduces volatility in availability and long-term pricing assumptions that rarely appear in standard procurement models.
Worldwide WiFi as a Service Market
Third, the regulatory environment is fragmenting in ways that complicate global deployment strategies. Data sovereignty requirements, cybersecurity mandates, and contractual fairness regulations are no longer confined to specific sectors or geographies. They are becoming baseline expectations for any organization operating across borders. Compliance is shifting from a legal checkbox to an architectural consideration, influencing how workloads are distributed, how data is stored, and how providers are evaluated. The market is adapting, but the pace of regulatory change continues to outpace the standardization of cloud governance practices across many enterprise portfolios.
Key Drivers Shaping Market Dynamics
The momentum in IaaS is being propelled by a convergence of technological, regulatory, and structural forces that reinforce one another. Understanding these drivers is essential for any organization planning multi-year infrastructure roadmaps, as each factor carries distinct implications for sourcing strategy, risk management, and innovation velocity.
Technological Innovation and AI-Optimized Infrastructure
The most transformative driver is the integration of advanced artificial intelligence capabilities directly into infrastructure offerings. Cloud providers are no longer simply offering raw compute, storage, and networking in isolation. They are designing optimized stacks that reduce the friction between infrastructure provisioning and AI workload execution. This includes purpose-built acceleration architectures, high-bandwidth interconnect fabrics, and managed orchestration layers that simplify deployment of training and inference pipelines. The result is a market where infrastructure differentiation is increasingly defined by how efficiently a platform can support machine learning lifecycles, not just by aggregate capacity.
This shift has practical consequences for procurement and architecture decisions. Workloads that previously required significant customization on general-purpose infrastructure can now be deployed on platforms with built-in optimization for specific AI patterns. At the same time, the growing share of inference workloads relative to training is reshaping demand profiles. Inference tends to be more distributed, latency-sensitive, and cost-sensitive, which encourages providers to invest in edge-adjacent capacity and more granular pricing mechanisms. Organizations that treat IaaS as a static commodity risk overlooking these architectural shifts and paying a premium for misaligned resource allocation.
Regulatory and Policy Evolution
Policy frameworks are becoming a central determinant of cloud strategy rather than a peripheral compliance concern. In multiple regions, regulators are acting on the premise that cloud infrastructure is critical economic infrastructure and must be governed accordingly. New rules are targeting contractual flexibility, data portability, cybersecurity responsibility, and transparency in service relationships. These measures are designed to reduce switching friction and increase accountability, but they also raise the operational bar for both providers and enterprise buyers.
For multinational organizations, this regulatory fragmentation introduces complexity in workload placement and vendor evaluation. Data residency expectations, sector-specific security obligations, and emerging contractual fairness requirements mean that a single global architecture rarely satisfies all constraints without deliberate design. Providers that can demonstrate localized compliance capabilities, clear data handling policies, and auditable governance structures are gaining an advantage in regulated sectors. The regulatory trend is not simply a constraint; it is also a filter that rewards providers with mature governance postures and penalizes those that rely on ambiguous terms or opaque data practices.
Enterprise Demand Shifts and Operational Priorities
On the demand side, enterprises are moving from experimentation to operational dependence. Cloud infrastructure now underpins core business processes across industries, and the question for many organizations is no longer whether to use IaaS but how to optimize its use at scale. This maturation is changing buying behavior. Procurement teams are increasingly focused on total cost of ownership rather than headline pricing, factoring in network egress, storage tiering, support models, and the hidden costs of integration and governance.
There is also a growing appetite for hybrid and multi-environment strategies, driven by the need to balance performance, sovereignty, and resilience. Organizations want the elasticity of public IaaS without sacrificing control over sensitive workloads or critical data flows. This is encouraging providers to invest in hybrid connectivity, consistent management planes, and interoperability features that reduce the operational divide between environments. At the same time, demand is becoming more segmented. Large enterprises with complex regulatory footprints have different priorities than startups optimizing for speed and simplicity, and the most successful providers are building distinct value propositions for each segment rather than relying on one-size-fits-all messaging.
Supply-Side Pressures and Cost Structure Evolution
The supply side of IaaS is undergoing a structural recalibration as physical constraints and input costs reshape expansion economics. Energy intensity is one of the most visible pressure points. As demand concentrates in power-heavy workloads, providers must secure long-term energy access, invest in efficiency improvements, and navigate regional grid limitations. These factors influence not only where new capacity can be added but also the cost trajectory of existing facilities. In markets where data center growth contributes materially to local electricity demand, pricing dynamics and community pushback can slow deployment timelines and raise operating expenses.
The implication is that IaaS cost structures are becoming more regionally differentiated. Providers with advantaged energy access, efficient cooling designs, and strong site selection capabilities can sustain more favorable economics, while capacity in constrained regions may carry higher premiums. This differentiation is beginning to surface in enterprise planning, where latency, compliance, and energy-related cost risk are weighed alongside raw performance. Over time, the market is likely to reward providers that can integrate energy strategy into their infrastructure roadmap as deliberately as they integrate compute and storage innovation.
Competitive Landscape and Emerging Strategic Postures
The competitive environment in IaaS is defined by a tension between scale dominance and targeted differentiation. A handful of hyperscale platforms continue to set the pace on global reach, service breadth, and investment capacity. Their advantage lies in the ability to amortize infrastructure costs across enormous workloads, sustain aggressive R&D programs, and offer ecosystems that extend well beyond raw infrastructure. For many enterprises, these platforms remain the default starting point because of their maturity, integrated tooling, and broad partner networks.
Yet scale alone is no longer a complete answer to every buyer need. Competitive pressure is increasing from multiple directions. Enterprise-focused providers are carving out positions around specialized workloads, particularly those requiring high-performance database execution, mission-critical reliability, or stringent regulatory alignment. Their strategy often centers on predictable performance, transparent pricing, and deep integration with existing enterprise software stacks. By emphasizing use cases where general-purpose hyperscale offerings may be less efficient, these players are building credible alternatives for specific procurement decisions.
Regional and sovereignty-oriented providers are also gaining relevance. In markets where data locality, regulatory alignment, and customer trust are paramount, providers that can demonstrate local governance, predictable compliance posture, and clear data handling practices are winning consideration even when global incumbents offer lower headline pricing. This is not simply a political preference; it reflects operational reality. Organizations facing audits, cross-border restrictions, or sector-specific security obligations often prioritize verifiable control over marginal cost savings. The emergence of strong regional players therefore adds genuine choice and reduces the effective lock-in risk that once characterized the market.
Developer-centric and managed service providers illustrate another dimension of competition. Some platforms focus on simplicity, rapid deployment, and predictable developer experience, targeting smaller enterprises and fast-moving product teams. Others operate as managed intermediaries, helping customers navigate multi-platform environments, optimize operations, and reduce the internal burden of infrastructure management. These models do not replace hyperscale infrastructure; they layer value on top of it. Their growth signals that many organizations are willing to pay for expertise, simplification, and operational relief, especially when internal cloud maturity is still maturing.
The competitive trajectory appears to be moving toward a more layered market. A small group of providers will continue to dominate aggregate share, but meaningful differentiation is increasingly occurring at the edges: in AI-optimized stacks, in regulated-industry credibility, in regional sovereignty positioning, and in managed operating models. Market consolidation is likely to continue in areas where scale economics are decisive, but fragmentation will persist where specialized trust, performance, or operational needs create room for distinct value propositions. For buyers, the practical implication is that sourcing decisions should be workload-specific and strategy-aligned rather than driven by a single provider relationship.
PW Consulting
Future Trends and Commercial Implications
Looking ahead, three trends are likely to shape the IaaS market over the next several years, and each carries direct commercial implications.
Worldwide IT Infrastructure Outsourcing Service Market
The first is the deepening entanglement of AI workloads with infrastructure economics. As inference becomes a larger share of demand and AI adoption spreads beyond experimental teams into production operations, providers will continue to refine platforms that make AI deployment more efficient and predictable. Enterprises that align their infrastructure strategy with these optimized stacks can reduce implementation friction and improve unit economics for intelligent applications. The risk is that organizations chase AI capability without a clear workload strategy, leading to fragmented spend and underutilized capacity. The opportunity belongs to those who map AI demand to specific infrastructure patterns and select platforms accordingly.
The second trend is the institutionalization of compliance and sovereignty as architectural requirements. Regulatory expectations will likely continue to expand in scope and enforcement rigor, especially where critical infrastructure, personal data, and cross-border transfers intersect. This will favor providers that can offer clear data residency options, auditable governance, and consistent policy enforcement across regions. For enterprises, the strategic lesson is that compliance must be designed into the cloud architecture early, not retrofitted after deployment. Organizations that build governance into their sourcing model will move faster and with less rework as regulatory pressure intensifies.
The third trend is the growing importance of energy-aware infrastructure planning. Power availability, efficiency, and cost will increasingly influence where workloads run and how providers price capacity over time. Enterprises with large, predictable footprints should anticipate greater regional variation in availability and cost, and plan accordingly. This may mean diversifying deployment footprints, factoring energy risk into long-term agreements, or selecting providers with demonstrable efficiency and site-strategy discipline. The uncertainty here is meaningful: grid constraints, local policy responses, and energy price volatility can change the economics of a region faster than contract cycles anticipate.
Strategic Recommendations for Decision Makers
For enterprises, investors, and procurement leaders, the central task is to treat IaaS as a strategic variable rather than a background utility. The following actions can help translate market dynamics into measured advantage.
- Align infrastructure sourcing with workload profiles. Not every workload benefits from the same platform. Map compute, storage, and networking needs against performance, compliance, and cost requirements, and evaluate providers on the basis of specific use cases rather than overall brand scale.
- Build multi-vendor and hybrid literacy internally. Dependence on a single provider creates speed in the short term but fragility over time. Developing architecture, governance, and operational skills across environments reduces lock-in risk and improves negotiating leverage.
- Integrate compliance, energy risk, and total cost into procurement models. Pricing alone is insufficient for long-term decisions. Include data residency requirements, security obligations, egress behavior, support economics, and energy-related availability risk in sourcing evaluations to avoid hidden downside.
The pace of change in IaaS means that organizations with current, granular intelligence have a real advantage in timing, negotiation, and architecture design. Detailed segmentation, regional cost dynamics, provider-specific positioning, and scenario analysis can materially improve strategic choices. For decision makers who need a more complete picture of where value is concentrating and where risk is accumulating, the full PW Consulting research report provides expanded data, deeper segmentation, and tailored guidance for specific operating contexts.
For detailed analysis of this topic, please visit the official page: Worldwide Infrastructure as a Service Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com