

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Category: market research
PW Consulting: LDI Systems Market to Grow at 7.8% CAGR, Reach USD 1,345M by 2032
By pmarketresearch, 2026-07-30
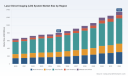
Laser Direct Imaging (LDI) Systems Market — Strategic Outlook for 2026 Decision-Makers
As PW Consulting’s lead industry analyst, I present a concise strategic primer on the Laser Direct Imaging (LDI) systems market intended to shape boardroom decisions in 2026. Our research, anchored on a 2025 base year and a historical review spanning 2020–2025, projects a sustained expansion through the 2026–2032 forecast window at a compound annual growth rate (CAGR) of 7.8%. Measured in Million USD, the market has grown from a base measured in 2020 and, with continued momentum in advanced electronics and specialty applications, is projected to reach north of USD 1.3 billion by the end of the forecast horizon. This briefing highlights the strategic inflection points, competitive dynamics, actionable recommendations, and the practical tools contained in our full report—while deliberately withholding the granular segment-level tables that enterprise teams must access via our research portal.
Laser Direct Imaging (LDI) System Market
Why LDI matters to 2026 strategic plans
- Technology convergence is accelerating. LDI is migrating from a PCB-centric enabler toward a crossroad technology used in advanced packaging, display substrates, and niche high-reliability markets (aerospace, medical). This expands addressable use cases and drives demand for higher precision, throughput, and process automation.
- Capital allocation trade-offs are becoming nuanced. Buyers and equipment OEMs face choices between retrofitting legacy exposure lines with AI-assisted alignment and vision upgrades versus greenfield investment in next-generation multi-beam or LIDE-capable platforms.
- Regulatory and quality requirements are structuring buyer behavior. Certifications and compliance frameworks (FDA 21 CFR Part 11, MDR, AS9100, ISO 13485 and comparable automotive/aerospace standards) materially increase time-to-deploy and create differentiated pricing tiers for compliant systems.
Market dynamics with strategic implications
- Measured growth, predictable runway. Our market model (base year 2025) shows steady expansion through 2032 at ~7.8% CAGR. For decision-makers, that translates into a predictable demand envelope for capacity planning, with particular read-through for capital equipment suppliers and financing arms supporting OEMs and fabs.
- Automation, vision, and AI as table stakes. In recent field deployments, a majority of new LDI installations included vision systems and auto-calibration modules to improve alignment and reduce operator dependence. Similarly, a growing share of platforms launched during 2025 incorporated AI-assisted calibration workflows, producing measurable reductions in alignment deviation. For buyers, prioritizing control software and sensing subsystems will deliver outsized operational value versus equivalent mechanical upgrades.
- Specialty end-markets command premium economics. Aerospace and healthcare customers collectively represent a meaningful premium segment within the LDI market, reflecting higher compliance and traceability requirements. Expect longer procurement cycles, greater service attach rates, and higher lifetime value per machine in these verticals.
- Product differentiation is sharpening. Demand for LIDE technologies (particularly for displays and emerging glass-substrate applications) and for flexible single-beam versus multi-beam architectures is reshaping product roadmaps. Providers that align optical performance with software-driven process control will increasingly capture higher-margin engagements.
Competitive landscape — clarity on who matters
The supplier market is moderately concentrated, with the top-tier players controlling a majority share of global revenue. This concentration creates a competitive environment where technology leadership, installed base services, and certification-compliant capabilities determine market share expansion.
Laser Direct Imaging (LDI) System Market
- Orbotech Ltd. (Israel) — Strengths: multi- and single-beam LDI platforms engineered for high-precision PCB and semiconductor workflows, coupled with integrated defect-detection. Strategic posture: leverage deep inspection and process integration to upsell software and service contracts to Tier-1 electronics manufacturers.
- Screen Holdings Co., Ltd. (South Korea) — Strengths: high-throughput multi-beam systems with advanced alignment and process automation. Strategic posture: double down on volume-driven customers where throughput and alignment accuracy are prioritized; use automation as a moat against lower-cost alternatives.
- Manz AG (Germany) — Strengths: compact, modular LDI systems and semiconductor equipment with a flexibility focus. Strategic posture: following recent divestment decisions in non-core areas, Manz is concentrating R&D and commercial efforts on LDI and advanced packaging, positioning for selective partnerships with systems integrators.
- LPKF Laser & Electronics AG (Germany) — Strengths: single-beam flexibility, LIDE technology for displays and packaging. Recent moves: reported progress in LIDE technology and flagged growing demand for AI-driven use cases and glass substrate processing. Strategic posture: exploit momentum in adjacent display and packaging markets to broaden addressable revenue and promote higher-margin application-specific systems.
- Han’s Laser Technology (China), ORC Manufacturing (Japan), Delphi Laser (China) and regional specialists — Strengths: regional manufacturing scale, cost-competitive systems, and integrated service offerings tailored to local fabs. Strategic posture: serve commoditized segments and fast-follow in select high-growth verticals; attractive partners for channel expansion and aftermarket services.
- Limata GmbH and Miva Technologies GmbH (Germany) — Strengths: energy-efficient platforms and niche substrate expertise (aerospace, medical). Strategic posture: focus on compliance-heavy niches and energy efficiency as decision levers for customers with sustainability targets.
Recent industry developments to watch
- LPKF’s product updates in 2025 and prior market statements highlight an accelerating migration of LDI into glass and AI-assisted use cases—creating adjacent revenue opportunities beyond traditional PCBs.
- Manz’s strategic refocus and selective divestments illustrate how vendors are optimizing portfolios to concentrate on higher-margin, high-growth LDI and semiconductor offerings.
- Across suppliers, there’s an observable shift toward bundling software, calibration services, and extended warranties—turning hardware sales into platform-led recurring revenue models.
What our full report delivers (operationally focused)
This briefing is an executive extract. The full PW Consulting LDI systems market study — structured for commercial teams, product strategists, and private-equity investment committees — includes:
Laser Direct Imaging (LDI) System Market
- A transparent demand model with annual market size by year (2020–2032), scenario sensitivity and downside/upside triggers calibrated to macro-electronics cycles. (Base year: 2025; forecast period: 2026–2032.)
- Supplier scorecards: capability matrices, roadmaps, and aftermarket economics to inform supplier selection and make-versus-buy decisions.
- Go-to-market playbooks for OEMs and channel partners covering pricing, service packaging, and certification pathways for aerospace/medical customers.
- CapEx and ROI calculators tailored to retrofit vs. replacement choices, including throughput and yield uplift assumptions driven by AI-assisted calibration benefits.
- Regulatory and compliance matrix, highlighting required certifications by end-market and implications for time-to-market and installed-base conversions.
- M&A and partnership heat maps that identify tactical consolidation targets and partnership archetypes by capability, geography, and customer adjacency.
Note: to preserve the strategic advantage of our clients, the report’s detailed segment-level tables and supplier-specific revenue splits are available exclusively via the full report portal. This executive extract intentionally omits granular segmentation figures to ensure commercial leverage for subscribers and clients.
Actionable recommendations for 2026 planning cycles
- For OEMs: Allocate R&D budget toward AI-assisted calibration, vision systems, and modular architectures that shorten customization cycles. Prioritize software-driven service bundles to convert one-time sales into recurring revenue.
- For PCB and packaging manufacturers: Run parallel capex pilots that compare retrofit AI-vision kits with new LDI platforms over 12–18 month windows. Build procurement clauses that capture certification deliverables (traceability, audit logs) up-front to avoid costly retrofitting for regulated customers.
- For investors: Seek targets with differentiated software stacks, high service attach rates, and an installed base in regulated end-markets. Be cautious on pure hardware plays without software or service monetization pathways.
- For service providers and system integrators: Develop certification and qualification services for aerospace and medical customers; these services can justify premium pricing and faster payback for customers upgrading equipment.
- For supply chain managers: Secure long-lead optical components and semiconductor laser sources through multi-year contracts or strategic partnerships, as localized supply disruptions can lengthen lead times and increase deployment risk.
Risk scenarios and mitigations
- Regulatory tightening. Mitigation: pre-qualify platforms against relevant standards and maintain an audit-ready documentation process.
- Rapid tech substitution. Mitigation: preserve flexibility by modularizing platforms and maintaining a balanced R&D portfolio across optics, control software, and services.
- Regional competitive pressure from low-cost suppliers. Mitigation: differentiate on service, certification, and integrated inspection capabilities—areas where price competition is less effective.
Conclusion: The LDI systems market presents a predictable growth runway with clear strategic inflection points around automation, AI-driven calibration, and regulatory specialization. In 2026, the companies and investors that translate these structural trends into product roadmaps, service strategies, and disciplined procurement will capture disproportionate value as the market scales toward the forecast horizon.
To access the full dataset, vendor scorecards, segmentation tables, and scenario models that underpin this briefing, please consult the complete PW Consulting LDI Systems Market Report on our research portal. The detailed segment-level analytics and downloadable Excel models are available to subscribers and licensed clients.
For detailed analysis of this topic, please visit the official page: Laser Direct Imaging (LDI) System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
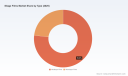
Silage Films Market — Strategic Imperatives for 2026 Decision‑Makers
As the global agricultural value chain navigates tighter environmental regulation, material-cost volatility and evolving on‑farm preservation practices, silage films have moved from a tactical procurement item to a strategic lever for feed quality, waste reduction and ESG compliance. PW Consulting’s latest Silage Films Market study (base year 2025) synthesizes five years of historical dynamics and a forward-looking forecast across 2026–2032 to deliver the actionable intelligence executives need to set winning 2026 priorities.
Silage Films Market
Executive snapshot: what this research enables
-
Clarity on market scale and trajectory: the silage films market has expanded steadily in the first half of the decade and is modelled to continue growing at a mid-single-digit compound annual growth rate through the forecast horizon. This projection frames realistic demand scenarios for procurement, production planning and investment gating decisions.
Silage Films Market -
Competitive positioning for buyers and suppliers: our study decodes the strategic moves of global incumbents and agile challengers — from product innovation to channel plays — enabling procurement teams to evaluate total cost of ownership rather than price per roll.
Silage Films Market -
Regulatory and standards impact: the analysis translates forthcoming standards and regionally accelerating plastic‑use policies into quantified implications for product specification, cost curves and substitution pathways.
-
Practical toolset for 2026 execution: templates, scenario models and a procurement playbook included in the report accelerate decision cycles and reduce implementation risk.
Market trajectory and what it means for corporate strategy
Between 2020 and 2025 the market recorded steady expansion as feed preservation practices intensified and multi‑layer film adoption increased. By the base year the market had grown materially compared with the start of the decade; our modelling projects continued growth through 2032 at a compounded annual growth rate of 4.82% for the forecast period 2026–2032, with total market value approaching the mid‑single‑digit million USD range by 2032. For industrial players this pace of growth signals predictable base demand, but the strategic value accrues to those that capture improved margins through product differentiation, waste-reduction features, and integrated service offers (e.g., collection and recycling partnerships).
Three commercial implications stand out:
-
Margin pressure will shift from pure price competition to performance economics. Buyers increasingly measure film value by silage loss reduction, labor savings and end‑of‑life handling costs. Suppliers that can demonstrate lower net cost per tonne of preserved forage will command premium positions.
-
Innovation in layer architecture and barrier technologies is the primary path to differentiation. Recent product introductions show suppliers trading thickness for barrier performance and recyclability features; these trade-offs will determine technical winners as standards and buyer expectations evolve.
-
Supply chain resilience matters. Raw material feedstock and film‑line capacity constraints create timing risk for large contracts. Contract design, inventory strategy and flexible manufacturing footprints will be decisive for both suppliers and large agricultural cooperatives.
Competitive landscape: incumbents, specialisms and strategic moves
The silage films market is neither monopolistic nor atomized — concentration metrics show a market where a handful of global players exert significant influence but meaningful share remains distributed among regional specialists and innovative challengers. This structure creates opportunities for selective consolidation, targeted partnerships and differentiated niche plays.
-
Rani Plast (Finland) — recognized for very wide, high‑performance multi‑layer films tailored to bunker and large bale applications. Their engineering focus and scale in specialized extrusion give them advantage in large‑format contracts.
-
Coveris (Austria) — a premium film producer with a history of innovation in stretch and oxygen‑barrier films; their branded solutions target operators seeking performance assurance and traceability.
-
Berry Global Inc. (United States) — a leading supplier with portfolio breadth, including multi‑layer film systems designed to reduce on‑farm losses through integrated Film&Film combinations and channel reach in major agricultural markets.
-
RKW Group (Germany) — specializes in polyolefin-based films and nets; their strength lies in industrial production consistency and established distribution in European markets.
-
Trioworld (Sweden) — positioned around sustainability claims and alternatives, offering products that emphasize reduced environmental footprint and higher oxygen permeability where appropriate.
-
Polifilm (Germany) — notable for co‑extruded silage films with manufacturing flexibility and product formats designed for grass and maize handling nuances.
-
Lallemand Animal Nutrition (Canada) — an important product innovator in oxygen‑barrier films; their OxyBlock range has reshaped discussions about performance trade‑offs between barrier technology and material usage.
Recent competitive activity underscores the priority suppliers place on barrier technology and multi‑layer architectures. A notable product launch in early 2026 introduced oxygen‑barrier variants that blend EVOH layers with multi‑layer extrusion designs; this demonstrates how performance-led launches can raise the specification floor for premium forage preservation.
Regulatory and standards shift: what to watch and how to respond
Regulation and standards are no longer background noise — they are key decision inputs. The introduction of new certification requirements for thermoplastic silage films has already raised the technical minimums suppliers must meet to compete in several major markets; compliance will influence product roadmaps and capital spend on line upgrades. Meanwhile, an accelerating policy momentum across several jurisdictions signals tighter limits on single‑use plastics and higher expectations for recyclability and take‑back programs.
For corporate decision‑makers, the immediate priorities are clear:
-
Integrate standards and regulatory scenarios into procurement contracts so that specifications can evolve without frequent price renegotiations.
-
Assess capital exposure to retool or qualify suppliers under updated certification regimes and build contingency sourcing options.
-
Develop circularity pilots that reduce end‑of‑life risk exposure and create differentiation—collection logistics and chemical recycling or compound‑recover options are increasingly commercially viable.
What the PW Consulting report packs (practical, executable sections)
This study is designed as an execution toolkit for senior leaders and functional teams. Highlights include:
-
Robust market sizing and demand-driver narrative that links agriculture macrotrends to film consumption dynamics (detailed annual baseline and forecast by global market, with scenario variance and sensitivity to feedstock price paths).
-
Competitive capability matrix and vendor dossiers that map product portfolios, manufacturing footprints, R&D focus and channel strategies for the major players — enabling faster supplier pre‑qualification.
-
Procurement playbook: RFP templates, scoring matrices weighted for performance economics, contract clauses for regulatory compliance and escalation, and inventory hedging strategies.
-
Product economics models: thickness vs. barrier trade‑offs, net cost per tonne preserved forage, and a capex vs. margin ladder for line upgrades to meet higher layer or barrier requirements.
-
Regulatory impact assessment and a policy-to-product roadmap that translates standards into technical requirements and cost implications.
-
M&A and partnership screen: acquisition targets and JV criteria for buyers seeking upstream control or technical capability in barrier technologies and recycling.
-
Implementation case studies and a 100‑day action plan for farm cooperatives, processors and film manufacturers.
How to use this intelligence in 2026 planning cycles
Executives should treat the report as both situational intelligence and an operating playbook. Recommended use cases include:
-
Capital allocation: use the report’s capex sensitivity and demand scenarios to prioritize extrusion-line upgrades, new barrier layer investments or recycling systems.
-
Procurement transformation: adopt the procurement templates and TCO models to transition from price‑only selection to performance‑based contracting.
-
Product strategy: align R&D roadmaps to the technical minimums implied by new standards and to the growing buyer preference for reduced‑loss, lower‑waste solutions.
-
M&A screening: focus on targets that add distinct technical IP (e.g., EVOH barrier integration), regional logistics advantages or circularity competence to accelerate differentiation.
Final note — why this is a “must‑read” before you sign any 2026 contracts
The headline market growth is not the story by itself; the competitive economics of silage films in 2026 will be determined by who can convert barrier performance and circularity into verifiable, farm‑level outcomes. Our study provides the framework and tools to do that conversion — but, in keeping with the “trailer” principle, this public summary intentionally omits the granular segmentation and granular regional breakdowns that buyers and investors need for contract negotiation and investment due diligence.
For the full dataset, supplier scorecards, granular scenario tables and the operational playbooks that support immediate 2026 actions, access the complete PW Consulting Silage Films Market report. The detailed annexes contain the fine‑grained splits, certification‑aligned specifications and supplier benchmarking that will materially shorten your path from insight to implemented advantage.
For detailed analysis of this topic, please visit the official page: Silage Films Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: THz Market to Reach USD 994.54 Million by 2032 at 15.8% CAGR
By pmarketresearch, 2026-07-30
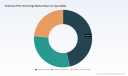
Terahertz (THz) Technology Market: A Strategic Roadmap for 2026 Decision‑Makers
This briefing frames PW Consulting’s latest Terahertz Technology Market research as an operational guide for executive teams planning investments, product roadmaps, and partnerships during 2026. Built on a 2025 base year and a granular forecast window spanning 2026–2032, the study quantifies a fast‑growing industry (CAGR 15.8%) that moved from an early commercial base a few years ago to a near‑billion dollar opportunity by the end of the forecast period. The market rose from roughly USD 205.7 million in 2020 to USD 358.5 million in 2025 and is projected to approach roughly USD 994.5 million by 2032 — framing a multi-fold expansion that materially changes strategic options for incumbents and new entrants alike.
Terahertz (THz) Technology Market
Why this report matters in 2026
- Timing: 2026 is the inflection point when lab‑grade THz capability matures into industrial and regulated applications — battery production inspection, advanced packaging inspection, and public security among them. Early movers who translate lab demonstrations into repeatable factory and clinical deployments will capture disproportionate value.
- Standards and regulatory momentum: New ETSI guidance documents (GR THz 003 and GR THz 004) and continuing IEEE activity are shifting THz from an exploratory physics domain to a standards‑driven engineering discipline. Procurement, certification, and spectrum planning decisions in 2026 must anticipate accelerating regulatory requirements.
- Capital market signals: Public market activity — including the first UK/European THz company listing on Korea’s KOSDAQ in early 2026 — validates exit routes and corporate development strategies, influencing valuation expectations for scale‑up financing and M&A.
- Competitive structure: The sector is moderately concentrated (top‑3 firms represent roughly 35% of measured market activity; top‑5 approximately 42%), leaving meaningful whitespace for differentiated technology and go‑to‑market plays.
What the report delivers (practical content)
- Transparent market sizing and a consistent forecasting methodology (2026–2032), with scenario variants and sensitivity to commercial adoption curves.
- Technology deep dives that explain trade‑offs across imaging, spectroscopy and communication approaches, including component ecosystem maps (sources, detectors, optics, electronics, and software stacks).
- Use‑case ROI toolkits and sample business cases tailored to manufacturing inspection, medical diagnostics, non‑destructive testing (NDT), and security screening.
- Vendor scorecards, procurement checklists and PoC templates designed to reduce trial‑to‑pilot cycle times and de‑risk supplier selection.
- Regulatory and standards tracker aligned to ETSI/IEEE outputs and regional compliance considerations, plus an IP and patent landscape summary to inform licensing and freedom‑to‑operate strategies.
- Corporate development playbooks — M&A screening criteria, partnership archetypes, and valuation benchmarks linked to technology maturity and revenue model.
Market dynamics and growth drivers
The market’s 15.8% CAGR is driven by three converging phenomena: maturing component technology, clarifying regulatory/std frameworks, and increasing commercial utility across high‑value verticals. Component costs and integration complexity continue to fall as silicon‑based detectors, compact THz cameras and fiber‑laser time‑domain solutions reach higher volumes. Standardization work — notably ETSI’s GR THz 003 and GR THz 004, and ongoing IEEE activity — reduces technical and procurement uncertainty, accelerating enterprise adoption.
Terahertz (THz) Technology Market
Commercially, the most visible near‑term traction is in industrial inspection (automotive coatings, battery electrode quality), semiconductor advanced packaging inspection, and targeted medical diagnostics — sectors where non‑ionizing THz imaging or spectroscopy offers unique contrast or throughput advantages. Parallel advances in scanner architectures (both active and passive), detector arrays, and integration with robotics and factory automation are turning lab demonstrations into scalable deployments.
Terahertz (THz) Technology Market
Competitive landscape — who matters and why
- TeraView Limited (Cambridge, UK) — A leader in applied THz imaging and spectroscopy focused on semiconductor packaging inspection, automotive paint/coating analysis, battery electrode production, and pharmaceutical quality control. Recent strategic moves include a KOSDAQ listing (Feb 2026) and partnerships to accelerate entrance into Korean EV battery lines and robotic inspection systems. These signal both capital access and intensified vertical go‑to‑market focus.
- TOPTICA Photonics AG (München, Germany) — Strong in terahertz time‑domain systems for spectroscopy, imaging and metrology. TOPTICA’s emphasis on laser‑source fidelity and metrology positioning makes it attractive for high‑precision lab and industrial customers looking for deterministic performance.
- Menlo Systems GmbH (Martinsried, Germany) — Offers THz time‑domain solutions built on mature fiber‑laser platforms; notable for over 300 systems deployed in field operations. Their installed base and precision orientation position them well for scientific and high‑accuracy industrial users.
- HÜBNER Photonics GmbH (Kassel, Germany) — Provides integrated THz imagers and spectrometers targeting public security and industrial inspection, with active participation in key optics and materials conferences — an indicator of pipeline momentum and research partnerships.
- TeraSense Group Inc. (Moscow, Russia) — Pioneers semiconductor‑based THz cameras, detectors and scanners. Their work on passive body scanners and compact detectors points to lower‑cost, high‑throughput deployments for security and NDT; geopolitical and supply‑chain considerations will inform regional go‑to‑market choices.
- Luna Innovations Incorporated (Roanoke, VA, USA) — Focused on industrial THz sensing (e.g., T‑Gauge solutions) with collaboration footprints in battery and materials inspection. Their industrial monitoring orientation is valuable for process control applications.
- TicWave Solutions GmbH (Germany) — Develops compact silicon‑based THz cameras and real‑time video systems; these product profiles are optimized for security screening and inline inspection integrations where throughput and form factor matter.
Recent developments to watch (early 2026)
- TeraView’s KOSDAQ listing (Feb 2026) — first UK/European THz company to list on that exchange, indicating investor appetite and a potential benchmark for future financings.
- Patent activity: Beijing Research Institute of Telemetry granted an EP patent (Apr 2026) for multimode real‑time THz imaging — a reminder that patent fences are forming around system architectures and real‑time modes.
- Partnerships and product pipelines: TeraView’s collaborations with Axbis and Doolim‑Yaskawa (May 2026) and TeraSense’s development of a passive THz body scanner (May 2026) illustrate the push to industrialize and scale vertically oriented solutions.
- Industry engagement: HÜBNER’s trade show participation and Menlo’s broad installed base underscore the sector’s transition from research showcases to revenue‑generating deployments.
Risk matrix and mitigation strategies
- Technical risk — source power, detector sensitivity and integration complexity: mitigate with modular architecture, hybrid sensor fusion, and staged PoC milestones tied to performance KPIs.
- Regulatory & standards risk — evolving ETSI/IEEE guidance can change product requirements: maintain active standards engagement and build compliance roadmaps into R&D timelines.
- IP & patent risks — growing patent activity may raise licensing needs: invest in targeted freedom‑to‑operate analyses and consider portfolio cross‑licensing as part of partnership negotiations.
- Supply chain & geopolitical risk — specialized components and regional concentration of vendors: diversify suppliers, localize assembly for key markets, and plan component lifecycles in procurement.
- Market adoption risk — proof to scale gap: use staged commercial pilots with measurable ROI thresholds and require supplier‑backed integration commitments.
Actionable priorities for 2026
- For R&D leaders: prioritize product architectures that balance cost, throughput and regulatory compliance; invest in detector arrays and software analytics that reduce per‑scan processing time.
- For product & operations: design modular subsystems to accelerate customization for verticals (battery, semiconductor, pharma) and embed factory automation interfaces early.
- For commercial teams: structure pilots as “value capture” tests — measurable KPIs (yield improvement, inspection speed, false‑alarm reduction) tied to procurement terms; use vendor scorecards from the report to standardize evaluations.
- For corporate development: screen targets by installed base, IP position, and vertical channel access rather than technology alone; public market exits and recent listings create definable valuation comparators.
How to use this report in your 90–180 day plan
- Run three parallel pilots (one each in manufacturing inspection, security screening and clinical diagnostics) using standardized PoC templates from the report; require suppliers to deliver measurable throughput and integration milestones.
- Execute an IP health check and regulatory gap analysis focused on ETSI/IEEE alignment and the recent EP patent landscape; use findings to prioritize licensing or R&D workstreams.
- Initiate supplier risk mitigation: create dual‑sourcing plans for critical detectors/sources and plan for regional assembly to lower geopolitical exposure.
- Set a corporate development cadence: shortlist acquisition or JV targets that close product‑to‑market gaps, and validate value creation via modelled revenue ramps and margin bridges provided in the report.
PW Consulting’s full Terahertz Technology Market report contains the segmented tables, regional and application breakdowns, vendor financial benchmarks, and scorecards necessary to execute the 90–180 day plan described above. This briefing highlights the strategic contours and operational imperatives; the report itself provides the granular datasets, scenario models, and procurement artifacts required to convert 2026’s market momentum into defensible, revenue‑generating programs. For teams evaluating THz investments, the single most valuable next step is to combine the report’s ROI toolkits with a short, funded pilot that explicitly tests commercialization assumptions under a standards‑compliant scope.
For detailed analysis of this topic, please visit the official page: Terahertz (THz) Technology Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Fiber Optics Market to Reach USD 15,227.7M by 2032 at 6.86% CAGR
By pmarketresearch, 2026-07-30
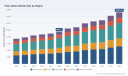
Fiber Optics Market 2026: Strategic Imperatives for Corporate Decision‑Makers
Executive primer — why this study matters in 2026
The fiber optics industry has moved from incremental utility to strategic infrastructure. Our PW Consulting analysis positions the global market as a multi‑billion dollar growth opportunity with a compound annual growth rate (CAGR) of 6.86% through the 2026–2032 forecast window. After steady expansion during 2020–2025, the base‑year market (2025) is reported at USD 9,567.7 Million and is projected to climb meaningfully over the next several years. For executives planning CAPEX, sourcing, R&D, or M&A in 2026, the timing to translate directional trends into concrete decisions is now: the market is large, growing, and being reshaped by concentrated technology demand, supply‑side stressors, and policy action.
Fiber Optics Market
What this report delivers — practical, decision‑grade outputs
- Clear top‑line trajectory and scenario models: Time‑series demand and revenue models covering 2020–2032, with three stress‑tested scenarios that map different AI, broadband, and industrial adoption curves against price and capacity shocks.
- Executive dashboards and playbooks: Actionable dashboards for boardroom briefings and a set of playbooks (sourcing, localization, vertical integration, and strategic partnerships) tailored for OEMs, cable manufacturers, hyperscalers, and telecom operators.
- Vendor and technology scorecards: Standardized criteria to evaluate suppliers across performance (fiber type and loss characteristics), manufacturing footprint, contractual flexibility, and geopolitical risk exposure.
- Supply‑chain risk maps and mitigations: Identification of single‑point dependencies (materials, components, and equipment), lead time scenarios, and practical hedging strategies—spanning contractual levers, inventory policy, and dual‑sourcing templates.
- Capital planning templates: CAPEX/OPEX overlays tied to network architectures (centralized vs. distributed), total cost of ownership (TCO) calculators, and payback analyses for fiber upgrades, replacement cycles, and co‑packaged optics investments.
- Regulatory & funding trackers: A living summary of major public funding programs and regulatory changes that affect deployment economics and procurement rules across major markets.
Core dynamics that should drive your 2026 choices
Several interconnected forces are steering the industry’s commercial logic in 2026. These are not abstract trends—each alters supplier economics, contract design, and technology roadmaps.
Fiber Optics Market
- Demand concentration in AI and hyperscale networking: Rapid densification of data center interconnects and co‑packaged optics initiatives are creating high‑intensity pockets of demand that differ materially from traditional telco and FTTH needs. Buyers must design procurement strategies that reconcile very different lifecycle and performance requirements.
- Policy and public funding acceleration: Large‑scale broadband and infrastructure programs continue to catalyze national deployment initiatives and influence where manufacturers and integrators allocate capacity and capital.
- Raw‑material and supply sensitivities: The upstream supply chain—particularly specialty dopants and preform materials—has become a strategic choke point. Recent months have seen notable price volatility and capacity rebalancing; companies without hedging or validated secondary sources face margin and delivery risks.
- Manufacturing reshoring and capacity expansion: Responding to hyperscaler demand and sovereign supply concerns, significant new capacity is being added in target markets. This alters lead times and cost curves for regional buyers but also intensifies competition for skilled labor and specialized equipment.
- Technology modularization: Multicore fibers, micro‑cables, and connector innovations are shifting cost/performance tradeoffs. Standards and MSAs for multicore designs are forming rapidly—early participation in these industry consortia can shape interoperable ecosystems and create supplier advantage.
Competitive landscape — strategic takes on leading players
The market combines global incumbents with regional specialists. The competitive field is characterized by deep technological capabilities, global manufacturing footprints, and an acceleration of strategic partnerships. Our sector analysis in the report synthesizes public disclosures, product roadmaps, and partnership announcements to produce a comparative, decision‑oriented view.
Fiber Optics Market
- Corning Incorporated: The incumbent technology leader—recognized for scale in single‑mode and advanced multicore solutions—has repositioned manufacturing and supply to serve hyperscale AI customers and is rapidly commercializing higher‑density optics and connector ecosystems. Recent product launches and supply agreements underscore a strategy of integrated system provision for data centers.
- Sumitomo Electric: Focused on ultra‑low‑loss fibers and end‑to‑end interconnect solutions, Sumitomo’s technical leadership in long‑haul and low‑attenuation fibers positions it well for capacity‑intensive network backbones and premium data center links.
- Fujikura: Active in multicore fiber standardization, Fujikura is aligned with AI‑optimized campus architectures and is leveraging consortium activity to accelerate adoption of higher‑density cabling in hyperscale environments.
- Prysmian Group and Nexans: European incumbents with strong systems capability across energy and telecom markets; their strengths lie in project execution for large infrastructure and industrial applications where end‑to‑end delivery and warranty are decision factors.
- Fitel / OFS, Sterlite, YOFC, FiberHome, CommScope, Amphenol: A cohort of specialized manufacturers and connectivity suppliers offering targeted value—whether in specialty fibers, local manufacturing scale, or high‑performance connectors. These players are often preferred by regional operators and system integrators for speed and price competitiveness.
Recent moves that change the strategic calculus
Industry collaboration and vendor commitments in early 2026 have accelerated momentum around multicore fiber standards and high‑density interconnects. Several leading suppliers have announced concerted efforts to standardize multicore architectures and to launch integrated systems aimed at AI campus densities. Such initiatives reduce integration risk for early adopters, but they also shorten windows for differentiation—firms that miss the early standards phase may find themselves dependent on commodity pricing rather than shaping specifications.
Risk scenarios — what to stress test in boardroom planning
The report provides scenario templates; here are the top strategic stress tests executives should run in 2026:
- Demand surge vs. supply constraint: Model the impact of a rapid hyperscaler procurement cycle on your supplier base and internal build schedules. Identify which contracts can scale without renegotiation and where minimum order quantities create risk.
- Material embargo or licensing restrictions: Assess the time‑to‑switch for critical dopants and preform inputs, and the cost of maintaining buffer stocks or alternative process routes.
- Price shock pass‑through: Simulate different pricing regimes for core materials and identify product lines where margins compress first; design pricing clauses and indexation strategies accordingly.
- Standards divergence: Evaluate the commercial impact if competing multicore standards gain asymmetric market acceptance, and map options for alliance, porting, or parallel qualification.
How to convert insight into action in 90–180 days
Based on our advisory engagements, successful companies follow a pragmatic, three‑track approach:
- Immediate (0–90 days): Run supplier risk audits, finalize short‑term hedging for critical inputs, and prioritize qualification of at least one secondary supplier for each high‑risk material or component.
- Medium (90–180 days): Negotiate scalable supply agreements with clear ramp profiles, invest in joint development agreements where standards are forming, and align procurement T&Cs to allow flexibility in volume and delivery.
- Organizationally: Create a cross‑functional fiber strategy cell (procurement, engineering, legal, M&A) to translate scenario outputs into contract templates, R&D priorities, and capital allocation decisions.
Why PW Consulting’s report is different
We combine a bottom‑up, transaction‑grade dataset (serial‑level production and orderbook analysis) with top‑down scenario engineering. The deliverable is designed for decision makers who need both a defensible forecast and an executable playbook: not just “what the market will be,” but “what you should do about it.” The report includes granular supplier scorecards, an operational risk atlas, and downloadable financial models aligned to the 2026 planning calendar.
Next steps — how to capture the intelligence you need
This article is a high‑precision extract. For the full suite—interactive dashboards, supplier matrices, scenario spreadsheets, and procurement playbooks—visit our report landing page. The full report contains the granular segmentation, regional and application dynamics, and vendor detailed profiles that are necessary to operationalize the strategies outlined here.
In a market where technology standards, buyer concentration, and supply fragilities are converging, timely, data‑driven choices will determine who captures value as the industry scales. PW Consulting’s Fiber Optics Market report arms leaders with the models and tools to make those choices with confidence in 2026.
For detailed analysis of this topic, please visit the official page: Fiber Optics Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Veterinary Vaccine Market to Reach USD 313.3M by 2032 at 7.25% CAGR
By pmarketresearch, 2026-07-30
Veterinary Vaccine Market: Strategic Preview for 2026 Decision-Makers
PW Consulting’s Veterinary Vaccine Market study (base year 2025; forecast period 2026–2032) synthesizes five years of historical performance with forward-looking scenario analysis to equip executives with decision-ready insight. The market has expanded materially since 2020 and, based on our modeled base case, is expected to grow at a compound annual growth rate of approximately 7.25% through 2032 — taking the global market from the low hundreds of USD Million in 2025 toward a materially larger opportunity by the end of the forecast horizon. This preview explains why the 2026 planning cycle is a watershed moment for vaccine manufacturers, animal health investors, and strategic partners, and it outlines the specific ways our research converts data into executable strategy.
Veterinary Vaccine Market
Why 2026 Is a Strategic Inflection Point
-
Structural tailwinds and rising addressable demand. Strong historical growth from 2020–2025 has created a higher base and predictable momentum into 2026. That trajectory elevates the value of scale, speed to market, and platform flexibility — especially for firms that can convert R&D into approved, commercially viable biologics faster than competitors.
Veterinary Vaccine Market -
Regulatory posture is tightening and operationally consequential. Regulatory enforcement and licensing processes are becoming more active and transparent; recent guidance reiterates that both establishment and individual product approvals are prerequisites for commercial distribution in the U.S. Compliance timelines and dossier completeness now meaningfully affect go-to-market timing and capital deployment.
Veterinary Vaccine Market -
Supply-chain tensions and input-cost volatility. Proposed tariffs on imported antigen and excipient components introduce a quantifiable risk to unit economics. Our scenario work models material-cost shocks and their downstream impact on pricing, margin compression, and sourcing decisions — making 2026 the year to operationalize hedges and local sourcing strategies.
-
Market structure favors decisive consolidation plays. The sector demonstrates a clear concentration profile among leading incumbents, which creates both entry barriers and strategic acquisition opportunities. Companies that move decisively on bolt-on acquisitions, capacity expansion, or strategic partnerships can unlock disproportionate commercial returns.
What the Full Study Delivers (Practical, Actionable Content)
-
Demand modeling and scenario dashboards — granular, stress-tested projections under alternative macro, regulatory, and input-cost pathways to quantify upside and downside to annual planning.
-
Regulatory playbook — step-by-step guidance for U.S. Veterinary Biologics establishment and product licensure, dossier checklists, recommended timelines, and common pitfalls illuminated by recent agency updates.
-
Manufacturing and capacity decision framework — build vs. outsource analyses, contract manufacturing vendor scorecards, CAPEX phasing templates, and temperature-stability optimization for vaccine supply chains.
-
Commercial go-to-market tactics — pricing strategies under material-cost stress, segmented channel approaches for livestock vs. companion animals (operational playbooks without revealing proprietary volume splits), and field force deployment models optimized for disease burden and veterinary practice economics.
-
M&A and partnership roadmaps — target prioritization criteria, valuation sensitivities, integration checklists, and synergies quantification to support rapid decision-making if M&A windows open in 2026.
-
Investment-grade due diligence packs — financial models, risk heat maps, and a compact list of technical and regulatory red flags for prospective buyers or JV partners.
Competitive Landscape — Strategic Takeaways on the Leading Players
-
Zoetis Inc. — As the global leader in veterinary biologics, Zoetis combines scale manufacturing, an extensive license footprint, and broad commercial reach. For competitors and partners, Zoetis represents both a benchmark for regulatory and supply-chain rigor and a potential consolidation counterparty for bolt-on deals in specialty segments.
-
Boehringer Ingelheim Animal Health — Boehringer’s active product innovation (including a notable vaccine launch in late 2025) demonstrates the commercial payoff of targeted R&D and rapid lifecycle management in swine and livestock portfolios. They remain a go-to comparator for how to fast-track category-defining products while maintaining regulatory compliance.
-
Elanco — Elanco’s dual focus on livestock and companion-animal vaccines positions it to capture cross-segment synergies, but it also faces the operational challenge of optimizing two very different go-to-market motions. Any strategic initiative should evaluate whether to emulate a dual-track commercial model or to specialize.
-
Merck Animal Health (Intervet) — Legacy R&D strength and portfolio breadth give Merck a durable competitive moat. For market entrants, Merck shows that sustained investment in platform technologies and global regulatory expertise yields defensive value that can be monetized through premium pricing and long-term contracts.
-
Ceva, Phibro, HIPRA, Diamond, Vaxxinova, Bimeda — These firms occupy important niches: regional strength, manufacturing specialization, and flexible license positions. They are frequently attractive targets for M&A or alliance strategies, and they often provide the fast-turn capacity or platform IP that larger players need to accelerate time-to-market.
Regulatory and Supply-Chain Dynamics You Must Model in 2026
-
Licensing and enforcement. The U.S. authority requires both establishment and product-specific licenses; the Virus-Serum-Toxin Act remains the regulatory foundation ensuring purity, safety, potency, and efficacy. Monthly notices and product code listings are now more actively published, creating predictable checkpoints that should be embedded into program timelines.
-
Input-cost pressure. Proposed tariffs on imported vaccine components introduce a tangible cost shock scenario. Our baseline financial stress-tests include a tariff-induced input-cost increase range that materially alters margin assumptions and shortens breakeven horizons for greenfield plants.
-
Operational resilience. Cold chain integrity, secondary packaging bottlenecks, and capacity utilization sensitivity are immediate operational levers. Firms that codify contingency vendors and regional buffer stocks in 2026 will outperform on fill-rate and customer retention metrics.
Priority Strategic Moves for 2026
-
Prioritize platform scalability over product exclusivity. Invest in modular manufacturing and cross-product platforms (e.g., vectored and recombinant technologies) that reduce time-to-first-dose across multiple indications.
-
Operationalize regulatory intelligence. Create a standing regulatory squad tasked with monitoring agency notices and fast-tracking dossier completions; align commercial launch calendars with published product code updates to avoid timing mismatches.
-
Hedge supplier exposure. Establish alternative sources for critical antigens and excipients, negotiate long-term contracts with price adjustment clauses, and evaluate near-shoring options to blunt tariff risk.
-
Use M&A to buy capacity and capabilities. Target smaller licensed manufacturers and specialty players that provide immediate production or niche-market access rather than greenfield expansions that have longer lead times.
-
Rework commercial models for differentiated channels. Align field force and digital engagement to the economics of livestock versus companion-animal customers; incorporate relative margin, disease prevalence, and veterinarian purchasing behavior into resource allocation.
How PW Consulting’s Research Enables Faster, Safer Decisions
-
We convert macro and micro data into executable plans: integrated financial models link epidemiology scenarios to revenue, margin, and CAPEX outcomes so leaders can run “what-if” tradeoffs in real time.
-
Our regulatory playbooks and dossier templates reduce approval risk and compress timelines by identifying common agency queries before filings are submitted.
-
Our M&A readiness kit shortens transaction timelines: valuation ranges, integration checklists, and synergy benchmarks are pre-populated to accelerate negotiations and post-close value capture.
Next Steps (and What We Intentionally Omit Here)
This preview intentionally highlights the strategic implications and actionable frameworks you need to navigate 2026. To maintain the “trailer” approach, we have withheld granular regional and application-level revenue splits and detailed per-product forecasts from this article. Those core segmentation tables, competitor product-by-product revenue breakdowns, and downloadable scenario workbooks are available in the full report and interactive dashboard on our repository.
For leadership teams preparing 2026 budgets: treat this year as the point at which investment in regulatory capability, supply-chain resilience, and scalable production platforms either pays off or becomes a permanent competitive disadvantage. PW Consulting’s full Veterinary Vaccine Market report delivers the numbers, timed playbooks, and transaction-ready materials to convert those strategic imperatives into measurable outcomes.
For detailed analysis of this topic, please visit the official page: Veterinary Vaccine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Absolute Rotary Encoders Market Poised for 7.8% CAGR to 2032
By pmarketresearch, 2026-07-30
Absolute Rotary Encoders Market — Strategic Preview for 2026 Decision-Makers
Executive summary
As automation, robotics, and precision motion control accelerate across industries, absolute rotary encoders have moved from a niche sensing component to a strategic enabler of digital operations. PW Consulting’s Absolute Rotary Encoders Market study (base year 2025) synthesizes five years of historical performance and a forward-looking forecast through 2032, integrating technological adoption curves, supply-chain shifts, regulatory headwinds, and competitive positioning. With the market growing at a compound annual growth rate (CAGR) of 7.8% over the forecast horizon, executive teams must translate this macro momentum into product, procurement, and M&A choices in 2026 — quickly and with clarity.
Absolute Rotary Encoders Market
Why this research matters in 2026
- Timing: 2026 is a hinge year for converting pilots into scale. Investments made now in encoder capabilities and supplier relationships determine who secures the next wave of robotic, conveyor, packaging, and semiconductor automation spend.
- Risk management: Supply-side shocks, regulation-driven price adjustments, and accelerated specification expectations (higher resolution, broader environmental tolerances, integrated communications) make forward-looking scenario planning essential to avoid costly redesigns.
- Value capture: Companies that align product roadmaps, go-to-market motions, and strategic partnerships to the demand profile identified in this study will secure disproportionate margin and share gains.
Market trajectory — the macro picture
Our analysis places the global absolute rotary encoder market at a pivotal juncture in 2025 (base year), with clearly visible momentum into the late 2020s and early 2030s. The study quantifies the market’s expansion trajectory and models demand drivers across industrial automation, robotics, and adjacent applications. The projected CAGR of 7.8% reflects structural drivers — rising automation intensity, increased adoption of higher-resolution sensing, and tighter integration with industrial communication protocols — while accounting for cyclical exposure in capital equipment cycles.
Absolute Rotary Encoders Market
Beyond headline growth, the study maps the interplay between unit mix, feature premiuming (e.g., IO-Link, higher-bit resolutions), and pricing pressure. Scenario analysis in the report shows how a mix shift toward premium encoders versus commodity magnetic/inductive units materially alters supplier economics and channel dynamics through 2032.
Absolute Rotary Encoders Market
Key dynamics reshaping the landscape
- Technology convergence: In 2024 and beyond, a meaningful share of new encoder launches exhibited 24-bit resolution and integration of digital communications (including IO-Link). Low-latency designs and extended temperature ranges are becoming table stakes in several verticals.
- Product differentiation: Suppliers are differentiating along sensing modality (optical, magnetic, capacitive), mechanical robustness (IP ratings, stainless-steel casings), and safety certifications — creating distinct value tiers and pathway choices for OEMs and system integrators.
- Regulatory and trade pressures: Import surcharges and region-specific tariffs introduced since mid-2025 have shifted landed cost calculations for EU- and Singapore-origin products. These adjustments amplify the strategic importance of diversified manufacturing footprints and bilateral supplier agreements.
- Supply and materials: Design choices around housings and materials — such as stainless-steel casings used for enhanced vibration and shock protection — have implications for lead time, cost, and aftermarket reliability claims.
- Performance expectations: Reduced latency (sub-100 microseconds), higher-resolution encoders (multi-million position counts), and integrated diagnostics are moving from optional features to procurement prerequisites in several end markets.
Competitive landscape — who matters and why
The encoder market remains moderately concentrated at the top: the combined share of the three largest suppliers and the top five players indicate a market where established brands still govern key OEM relationships and standards conversations. That concentration rewards scale, channel reach, and engineering depth, but it also leaves openings for focused innovators that can deliver step-change performance or tailored solutions for niche applications.
Selected supplier archetypes highlighted in the study:
- Established industrial specialists — companies with deep automation credentials and broad protocol support. These players are winning large, system-level deployments by coupling product breadth with field engineering and service capabilities.
- High-precision innovators — firms that advance sensing physics (capacitive, optical) and offer high-bit resolutions targeted at robotics, semiconductor tooling, and defense applications.
- Ruggedized and hazardous-area providers — suppliers that combine explosion-proof ratings and high IP protection with domain-specific certifications for oil & gas, mining, and chemical sectors.
- Compact and cost-focused vendors — manufacturers delivering small-form-factor encoders optimized for space-constrained automation and embedded motion systems.
The report examines individual company strengths and strategic postures. For example, enterprises offering IO-Link enabled models and robust software diagnostics are increasingly positioned as preferred partners for Industry 4.0 implementations. Manufacturers advancing capacitive and electric-encoder technologies have clear differentiation in precision segments. Meanwhile, firms emphasizing heavy-duty form factors and certification portfolios remain the default choice for harsh-environment installations.
Recent developments and strategic implications
- Trade show and product activity through 2024–2026 demonstrates where R&D and marketing energy is concentrated. New exhibitor showcases and catalog updates signal prioritization of robot- and semiconductor-focused product lines.
- Product launches of compact and high-resolution devices indicate supplier bets on collaborative robotics and miniaturized systems — an area where early partnerships with cobot OEMs can lock in preferred supplier status.
- Catalog refreshes and updated series releases suggest suppliers are refreshing core platforms to support new interface standards and durability expectations.
What the full PW Consulting report delivers (practical modules)
- Market sizing and seven-year forecast (2026–2032) with scenario modeling that isolates demand sensitivity to resolution-premiuming, communication integration, and macro capital expenditure cycles.
- Detailed competitive profiles and capability matrices — not just who the players are, but how they win: channel models, service footprints, IP strength, and feature roadmaps.
- Go-to-market playbooks for OEMs, distributors, and system integrators — including channel segmentation, pricing tactics, and customization levers that protect margin while scaling volume.
- Supply-chain stress-testing and landed-cost models that incorporate recent tariff and surcharge developments, raw-material constraints, and alternative sourcing scenarios.
- Product development and specification toolkit — practical guidance on resolution choices, communication stacks (including IO-Link adoption), environmental sealing, and latency targets mapped to end-market ROI thresholds.
- M&A and partnership shortlist: quantified screening criteria and due-diligence checklists to prioritize inorganic growth or strategic alliances in 2026.
- Field-validated case studies and supplier selection frameworks to accelerate procurement cycles and reduce time-to-production for new encoder integrations.
How executives should use this study in 2026
- Strategic procurement: Reassess supplier portfolios with a two-tier approach — secure long-lead components with diversified sources while negotiating performance-based contracts for premium modules.
- Product roadmap alignment: Prioritize upgrades that unlock the highest willingness-to-pay in target verticals (e.g., higher resolution plus integrated diagnostics for robotics; ruggedization and certifications for industrial processes).
- Channel and revenue playbook: For manufacturers, develop bundled offerings (encoder plus diagnostics software) to migrate customers to subscription-style services and aftermarket revenue.
- M&A and partnership tactics: Use the report’s screening tools to identify bolt-on capabilities (precision sensing, IO-Link stacks, or hazardous-area certification) that accelerate penetration into strategic segments.
- Risk mitigation: Employ the supply-chain models to quantify the impact of regional surcharges and to prioritize local assembly, dual-sourcing, or strategic inventory buffers where justified by margin and uptime risk.
Conclusion — why access the full intelligence
The Absolute Rotary Encoders Market study is structured to move executives from high-level awareness to executable decisions in 90 days. It combines empirical market sizing, robust scenario analysis, supplier intelligence, and actionable playbooks to inform 2026 capital allocation, product development, and M&A. This preview demonstrates the study’s strategic depth without disclosing the granular segmentation data and proprietary forecasts that the full report contains — insights that buyers, OEMs, and investors will need to operationalize the opportunities identified here.
For teams preparing budgets, syndicating supplier strategies, or evaluating acquisition targets in 2026, this research is designed to be the single-source reference that aligns commercial, engineering, and procurement priorities. Visit our report page to obtain the full dataset, interactive models, and the hands-on implementation toolkit that accompany PW Consulting’s Absolute Rotary Encoders Market study.
For detailed analysis of this topic, please visit the official page: Absolute Rotary Encoders Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Probiotic Strains Market Set to Grow at 6.98% CAGR Through 2032
By pmarketresearch, 2026-07-30
Probiotic Strains Market — A Strategic Briefing for 2026 Decision-Makers
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I present a high-level, decision-focused introduction to our new Probiotic Strains Market research. This briefing is designed as a “trailer”: it surfaces the analytical framework, strategic implications, and actionable playbooks that corporate leaders and investors need when setting 2026 priorities, while reserving the full, segment-level intelligence for the complete report.
Probiotic Strains Market
Market snapshot: momentum, scale and concentration
The probiotic strains market has transitioned from a nascent specialty ingredient sector into a structurally growing, commercially strategic category. Using 2025 as the base year, our top-line sizing estimates show the market expanding from approximately USD 163 million in 2020 to about USD 215 million in 2025. Under our base-case forecast this growth continues through 2032 at a compound annual growth rate (CAGR) of roughly 6.98%, reaching an overall market size near USD 345 million by 2032.
Probiotic Strains Market
Two structural features are particularly important for strategy in 2026. First, the market is moderately concentrated: the three largest suppliers together account for a majority share of market revenues, and the five largest suppliers widen that dominance further. Second, growth is neither uniform nor purely volume-driven — it is being re-shaped by regulatory gatekeeping, product-format innovation (e.g., co-fermentation beverage concepts and stabilized shelf-stable formulations), and scaling of contract manufacturing capabilities.
Probiotic Strains Market
Why 2026 is a strategic inflection point
-
Regulatory tightening and market access. New regulatory actions in 2026 — including import and registration requirements introduced by China’s customs authorities and updates to permitted-strain lists for infant nutrition — materially change go-to-market calculations for players seeking or maintaining access to Asia’s largest markets. These developments elevate compliance as a commercial differentiator.
-
Novel strains moving toward mainstream use. High-profile regulatory milestones (for example, notifications or clearances enabling commercial use of newly characterized strains) are lowering the technical and commercial risk of next-generation ingredients. The regulatory acknowledgment of strains sourced from human microbiota and promising candidates such as Akkermansia-related products points to a widening functional and therapeutic frontier.
-
Supply-side expansion and CDMO acceleration. Contract manufacturers are expanding probiotic-dedicated suites and capacity, which improves reliability for brand owners and reduces time-to-market for complex formulations. This capacity ramp enables larger launches but also intensifies competition to secure long-term supply agreements.
-
Commercial innovation beyond pills. Recent product launches leveraging multi-strain co-fermentation and high-activity single-strain formulations demonstrate consumer-ready use cases in dairy, juices, and reduced-sugar formats. These examples signal that formulation innovation, not only strain selection, is a primary value lever.
Competitive landscape — strategic archetypes and implications
Our competitive analysis identifies several archetypes among incumbent and emerging players. Understanding these archetypes helps inform partnership, M&A, and competitive defense strategies.
-
Strain library and IP specialists — firms with large proprietary collections and documented clinical dossiers for targeted indications. These players (exemplified by companies that offer hundreds of unique strains and curated blends) compete on depth of evidence and licensing potential. For corporates seeking differentiation via clinically substantiated claims, these suppliers are critical partners or acquisition candidates.
-
Application-focused formulators — companies that tailor strains for specific food categories (e.g., chilled dairy, plant-based, confectionery or gummies). Their capability lies in co-development with brand owners to meet sensory and shelf-life requirements. For consumer-packaged goods firms, these partners de-risk product development.
-
CDMO and scale manufacturers — contract manufacturers that specialize in live microorganism production, stability, and fill/finish. Recent capacity expansions by leading CDMOs double production throughput in some locales and remove a previous bottleneck for large-volume launches.
-
Specialist genus players — companies focused on specific genera (e.g., Bacillus or Lactobacillus) and applications where those genera offer technical advantages (heat-stability, gastrointestinal survival, oral health). These focused suppliers often excel in niche channels and ingredient cost-efficiency.
Strategically, a typical winning play for 2026 is a hybrid approach: secure a strategic supply anchor with a proven CDMO, license or partner with a strain-IP owner for clinical differentiation, and co-develop an application-formulation with an application specialist. This triple alignment compresses time-to-market while preserving claim defensibility.
Selected recent events shaping 2026 strategy (illustrative)
-
Regulatory: China introduced registration requirements for overseas manufacturers of foods and health foods containing probiotic strains — immediately affecting import-dependent brands and pushing more manufacturers toward onshore registration or local partnerships.
-
Commercial partnerships: Strategic alliances formed in 2026 to co-develop next-generation digestive wellness strains underscore an industry shift toward collaborative R&D and co-ownership models.
-
Product innovation: Market-visible launches of co-fermented beverages and high-activity single-strain drinks indicate rapid maturation of non-pill delivery formats and expanded consumer applications.
-
Capacity expansion: Major contract manufacturers announced dedicated probiotic suites and doubled capacity in strategic markets, materially reducing supply risk for high-volume customers.
Actionable playbook for corporate leaders in 2026
In the current phase, executives should prioritize a small set of high-impact moves that align with their scale and strategic intent.
-
Regulatory-first market entry: For companies targeting China and adjacent markets, make registration pathway mapping and strain permissibility screening the first item in every product development plan. Factor localization timelines into commercial launch calendars.
-
Supply anchoring: Negotiate minimum-volume commitments and dual-sourcing terms with CDMOs to secure continuity of supply, especially where strains require specialized upstream processes. Consider capacity reservation agreements in parallel with technical transfer clauses.
-
Evidence clustering: Invest selectively in randomized controlled trials or real-world evidence for core strain claims that align with your brand’s value proposition (e.g., digestive comfort, immune support, oral health). Clinical evidence remains the strongest barrier to commoditization.
-
Format innovation: Pair strain selection with application R&D: co-fermentation, microencapsulation, and sugar-reduced matrices are pathways to unique sensory and shelf-stability positions that command premium pricing.
-
Portfolio carve-outs for M&A: Identify small-to-mid cap strain owners or regional players with strong regulatory footholds as bolt-on targets. The market concentration metrics imply attractive consolidation opportunities for firms seeking rapid scale.
-
IP and compliance audits: Conduct an IP and regulatory readiness audit before any cross-border launch; the cost of a misstep in registrations or claims can eclipse near-term commercial gains.
Risks, mitigations and near-term stress tests
-
Regulatory volatility: Mitigation — maintain a regulatory monitoring function and an adaptive dossier-management process to rapidly respond to new country-level requirements.
-
Supply chain fragility: Mitigation — diversify by geography and process technology; build inventory buffers for launch-critical SKUs and include technical transfer milestones into supplier contracts.
-
Evidence erosion risk: Mitigation — develop layered evidence strategies (clinical, mechanism, consumer sensory) and align marketing claims tightly to validated endpoints.
-
Commoditization pressure: Mitigation — protect margin via formulation complexity, exclusive strain licenses, or route-to-market control (private label vs. branded partnerships).
What the full PW Consulting report delivers — a practitioner’s toolkit
Our comprehensive research package goes beyond this strategic preview. The full report is operationally focused and designed for immediate use by strategy, R&D, regulatory, supply chain, and M&A teams. Highlights include:
-
Market-sizing methodology and transparent assumptions (historical 2020–2025 validation and 2026–2032 scenarios).
-
Strain-level dossiers and clinical-evidence matrix for commercially relevant strains and emerging candidates.
-
Regulatory tracker and decision tree for priority markets, including registration pathways and claim frameworks.
-
Supplier and CDMO scorecard with capability maps (manufacturing platforms, QC systems, and capacity expansion timelines).
-
Commercial playbooks for five go-to-market archetypes: global brand, regional challenger, ingredient licensor, CDMO partner, and retail private-label operator.
-
M&A screen and target short-list with valuation vectors and integration risk assessments.
-
Operational checklist for commercialization (supply contracts, stability testing, claims substantiation, labeling and customs compliance) tailored to 2026 requirements.
Final perspectives — where value will be created in 2026
Value in the probiotic strains market this year will accrue to organizations that can orchestrate three capacities simultaneously: regulatory navigation, formulation engineering, and evidence generation. Firms that lock in compliant supply, pair differentiated strains with consumer-friendly formats, and back claims with rigorous evidence will capture outsized share as the category scales at nearly 7% CAGR toward 2032. Conversely, commoditized low-evidence suppliers and brands that underinvest in registration will face accelerated margin compression and market access constraints.
This briefing outlines the strategic contours. For granular segment analysis, company-by-company profiles, and the detailed playbooks required to operationalize a 2026 strategy, access our full Probiotic Strains Market report. The full package contains the proprietary data, models, and tactical templates that executive teams need to make risk-calibrated investments and commercial commitments with confidence.
For detailed analysis of this topic, please visit the official page: Probiotic Strains Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Flexographic Printing Plate Market to Reach USD 5,210M by 2025 at 2.3% CAGR
By pmarketresearch, 2026-07-30
Flexographic Printing Plate Market — Strategic Preview for 2026 Decision-Makers
As PW Consulting’s lead industry analyst I present a focused preview of our comprehensive Flexographic Printing Plate Market study. Designed as a strategic “trailer,” this introduction demonstrates the analytic depth and practical value that our full report delivers to executives making pivotal 2026 decisions — while deliberately reserving granular segmentation outputs for the full publication to protect actionable intelligence.
Flexographic Printing Plate Market
Market trajectory: what the numbers tell us
The flexographic printing plate market has demonstrated steady expansion through the first half of the decade. Our topline sizing shows growth from a market base of approximately USD 4,610 million in 2020 to roughly USD 5,210 million in 2025. PW Consulting’s modeling anticipates the market crossing a near-term inflection point in 2026 before continuing to 2032 with a compound annual growth rate (CAGR) of about 2.3% across the forecast window. The 2026 estimate signals renewed demand dynamics as converters adapt to sustainability mandates and modernize production workflows.
Flexographic Printing Plate Market
These aggregate figures mask important structural shifts — notably a concentration profile that favors a small group of vertically integrated suppliers. The market concentration metrics indicate meaningful share held by the top-tier players, creating both stability and barriers for faster-moving challengers. For 2026 strategic plans, executives should interpret the headline growth as an invitation to refine positioning rather than a signal to pursue broad-market expansion without targeted priorities.
Flexographic Printing Plate Market
Why this preview matters for 2026 strategic choices
- Capital allocation under regulatory pressure: Sustainability regulations and packaging waste directives are reshaping capital priorities across converters and plate manufacturers. Investments in cleaner plate processing (e.g., water-washable technologies and solvent-free workflows) are increasingly table stakes for market access, particularly in regulated geographies.
- Technology transition management: The rise of direct imaging, automated plate processing, and press-ready eco-friendly plate workflows creates a bifurcation: adopters capture workflow cost advantages and faster time-to-press; laggards risk margin erosion and lost contracts. 2026 is a pivotal year to decide on phased vs. wholesale technology adoption.
- Supplier strategy and risk mitigation: Concentration among leading suppliers means buyer-supplier relationships, long-term contracts, and co-development agreements will be determinative. Our full report outlines how to balance supplier consolidation benefits with contingency sourcing to protect throughput continuity.
- M&A and partnership levers: Given the moderate CAGR, inorganic growth and capability tuck-ins (imaging, finishing, substrate expertise) are effective ways to outpace market growth. We identify acquisition archetypes likely to deliver immediate EBITDA uplift and strategic differentiation.
Practical intelligence included in the full PW Consulting study
The report is built to be operationally useful to procurement leads, R&D heads, commercial strategists, and private equity sponsors. Highlights you can expect (outlined here at a high level) include:
- Robust market-sizing and forecasting methodology with transparent assumptions and scenario variants for low-, base-, and high-growth paths.
- Demand-driver mapping linking end-market packaging trends, substrate shifts (including recycled and mono-materials), and regulatory catalysts to plate demand profiles.
- Technology and cost-to-serve benchmarks covering photopolymer, rubber, and alternative plate systems, with practical guidance on lifecycle TCO and break-even horizons for automation investments.
- Supply-chain and input-cost analysis highlighting key raw-material sensitivities, logistics bottlenecks, and inventories-to-sales indicators that matter for 2026 planning.
- Commercial playbooks for price negotiation, service-bundling, and converter enablement strategies that protect margins while accelerating uptake of sustainable plate solutions.
- Corporate strategy tools: M&A screening filters, integration checklists, and partnership frameworks that align with the current competitive dynamics.
- Executable risk scenarios tied to regulatory rollouts and substrate adoption curves, coupled with recommended mitigation actions and trigger points for management responses.
Competitive landscape: what the leading players are doing (strategic takeaways)
The competitive architecture is dominated by a cohort of legacy materials manufacturers, imaging systems providers, and specialty rubber and polymer houses. These firms are pursuing complementary strategies — platform optimization, sustainability leadership, and process automation — that define where value will accrue in 2026 and beyond. Below are synthesized strategic profiles of the most consequential participants.
- DuPont (United States) — Market leader in photopolymer plates with digital HD solutions. DuPont’s emphasis on high-resolution digital flexo positions it to capture premium quality-sensitive segments. For buyers, DuPont remains a primary partner for advanced color-critical packaging applications.
- Asahi Kasei (Japan) — A front-runner in water-washable and solvent-free photopolymer plates. Asahi’s demonstrations of gravure-level print on recycled substrates and sustainability certifications align it with converters prioritizing PPWR-compliant production and reduced solvent footprints.
- MacDermid Graphics Solutions (United States) — Offers an integrated digital photopolymer plate ecosystem. Their strategy balances established analog strengths with digital migration paths for converters seeking stepwise modernization.
- Flint Group (Germany) — Comprehensive plate portfolio tailored to packaging converters. Flint’s breadth gives it a competitive edge when clients require single-vendor sourcing of inks, plates, and prepress systems.
- Fujifilm (Japan) — Focused on high-quality Flenex plate technology designed for elevated print performance. Fujifilm targets premium brand-pack applications where visual differentiation justifies investment.
- Esko (Belgium) — Specializes in imaging and plate processing systems; recent showcases emphasize automated water-washable solutions tailored to compliance with emerging packaging-waste regulations. Esko’s systems are critical for converters pursuing automated, compliant workflows.
- Kodak (United States) — Maintains a balanced photopolymer and plate solution set, competing on digital integration and workflow optimization.
- Toyobo (Japan), Harper Corporation (United States), Trelleborg (Sweden) — These firms cover advanced photopolymer and rubber plate niches, serving converters with specific substrate or machine compatibility needs.
Collectively, the top-tier players exhibit a high level of market control, reflecting an oligopolistic tendency that favors scale, integrated solutions, and regulatory-compliant product portfolios. This configuration creates distinct options for market entrants: specialize in niche substrate compatibility or partner with existing platform providers to gain distribution access quickly.
Recent industry dynamics shaping 2026
- Sustainability & compliance: Live demonstrations in 2026 showcased press-ready eco-friendly plates produced via direct imaging dry-film lamination and automated water-washable workflows. These developments reinforce the view that regulatory alignment (including PPWR-related implications) is a non-negotiable requirement for commercial participation in many markets.
- Process automation & digitalization: Exhibitions highlighted automated CI flexographic printing and imaging systems that reduce operator variability and speed make-ready times. Automation is now a primary lever for cost-per-unit reduction.
- Quality convergence: Industry forums reported gravure-level output achievable on flexo with modern plates and process controls — an opportunity for flexo to reclaim share from other printing technologies in several packaging segments.
How executives should apply this intelligence in 2026
- Procurement: Use multi-year rolling contracts with technology clauses that provide upgrade pathways tied to compliance milestones. Price alone will not secure supply; technical compatibility and sustainability credentials will be decisive.
- Operations & CapEx: Prioritize investments that reduce water and solvent use, improve throughput via automation, and enable press-ready plate adoption to cut total lifecycle costs.
- Commercial & R&D: Align product roadmaps to recycled substrate performance and gravure-level quality where brand owners are willing to pay for differentiation.
- M&A & partnerships: Focus on bolt-ons that add imaging or finishing capabilities, or regional distribution assets that accelerate market access without duplicative scale costs.
Final note — what’s withheld here and why
This preview intentionally demonstrates analytic scope and strategic relevance while withholding the granular segmentation tables, region-by-region shares, and specific application split metrics that power deal-level decisions. That level of disaggregated intelligence — including driver-weighted demand curves, modelled price elasticity, and executable channel strategies — is available in the full PW Consulting study and is essential for transaction diligence, procurement renegotiation, and capex justification.
Next steps
For procurement leads, corporate strategists, and PE sponsors planning 2026 actions, the full report offers the quantitative models, sensitivity scenarios, and supplier scorecards required to move from strategy to execution. Contact PW Consulting to access the complete dataset, scenario models, and tailored advisory support for turning the market’s steady growth and structural shifts into defensible competitive advantage.
For detailed analysis of this topic, please visit the official page: Flexographic Printing Plate Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Soliris (Eculizumab) Market to Hit USD 7,200M by 2032 at 5.5% CAGR
By pmarketresearch, 2026-07-30
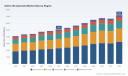
Soliris (Eculizumab) Market — Strategic Outlook for 2026 Decision-Makers
As payers, manufacturers, investors, and specialty pharmacies prepare for a pivotal phase in the complement-inhibition landscape, PW Consulting’s Soliris (eculizumab) Market study offers a focused, action-oriented intelligence package designed to inform 2026 strategy. The market is no longer static: between 2020 and 2025 the global market expanded meaningfully, with the base year (2025) reflecting industry revenues at approximately 5,100 USD Million. Looking forward, our forecast through 2032—built on a 5.5% compound annual growth rate—anticipates further expansion to roughly 7,200 USD Million by the end of the period. These topline dynamics underscore both opportunity and disruption for incumbents and challengers alike.
Soliris (Eculizumab) Market
Why this report matters for 2026 strategic choices
-
Timing is critical. 2026 is a decision inflection point: biosimilar entry, regulatory lifecycle events, and label expansions converge to reshape access, pricing, and channel strategy.
Soliris (Eculizumab) Market -
Focused, executable guidance. The study converts macro trajectories into commercial and clinical playbooks—helping management teams translate growth projections into prioritized investments (clinical, manufacturing, and commercial), risk mitigation, and M&A screening.
Soliris (Eculizumab) Market -
Competition and concentration. The Soliris market remains highly concentrated, with established originator capabilities and a compact set of commercial-scale competitors. Understanding the interplay between originator lifecycle management and biosimilar commercialization is central to 2026 planning.
Data-driven market context (what the numbers tell us)
Our modelling integrates historical performance (2020–2025) with indication-level uptake dynamics, pricing trends, and policy variables to project a steady mid-single-digit CAGR through 2032. The market’s ascent from the 2020 baseline to the 2025 position reflects a combination of label expansions, broader clinical adoption in specialty indications, and durable patient retention in chronic indications. The subsequent forecast to 2032 takes into account known regulatory expiries and biosimilar commercialization activity, resulting in an end-period market value in the vicinity of 7.2 billion USD.
Crucially, the forecast is scenario-driven: conservative, central, and upside cases quantify how variables such as payer reimbursement shifts, biosimilar penetration speed, and incremental approvals impact revenue trajectories. These scenarios are stress-tested against regulatory and supply-side contingencies to give decision-makers practical thresholds for action.
Competitive landscape — concise synthesis
-
Originator leadership: Alexion Pharmaceuticals remains the commercial and clinical anchor for Soliris globally, supported by AstraZeneca’s broader portfolio management and evidence generation capabilities. Recent clinical presentations through early 2026 reinforce the originator’s long-term safety and efficacy narrative across multiple neurology and hematology indications—material when negotiating with payers and specialty pharmacies.
-
Biosimilar entrants: The market has moved from anticipation to execution. A commercial biosimilar to Soliris was launched in the U.S. in 2025 under a strategic partnership model that separates development/manufacturing and U.S. commercialization responsibilities. That partnership structure—and the upstream manufacturing commitments—creates a durable competitor that can scale rapidly if payer coverage dynamics allow.
-
Concentration and deal structures: High concentration means that strategic moves by a small number of players (label changes, REMS adjustments, supply commitments) have outsized market effects. The report examines partnership archetypes, go-to-market agreements, and commercial operating models that have been executed to date and their implications for share reallocation.
Regulatory, access, and payer dynamics shaping 2026
Several regulatory and market-access events compress the decision window in 2026. Notable developments that materially influence strategy include label expansions for pediatric populations, REMS program adjustments tied to new indications, and the timing of exclusivity expiry for specific indications. In parallel, patient-assistance solutions and payer co-pay programs remain central to maintaining therapy continuity in the face of competitive pressure. The report maps these elements into a payer-sensitivity model and a REMS-compliance checklist so teams can anticipate formulary and utilization management responses.
Manufacturing and supply-chain considerations
Manufacturing capacity and contracted supply represent a strategic lever for both originator and biosimilar players. The biosimilar entrant’s vertical split—where one party handles development and manufacture while another focuses on U.S. commercialization—creates both resilience and points of fragility. Our supply-chain risk matrix evaluates lead-time sensitivities, single-source dependencies, and inventory strategies to maintain continuity for chronic patients while enabling competitive launches.
What the full report delivers (operative, non-generic deliverables)
-
Proprietary forecast model (2026–2032) with scenario toggles: users can adjust inputs for biosimilar penetration, pricing erosion, and new-indication uptake to see real-time financial implications.
-
Launch-sequencing playbook: tactical guidance for timing label submissions, REMS modifications, and regional rollouts to optimize uptake and minimize price erosion.
-
Payer and channel playbooks: granular tactics for specialty pharmacy engagement, hospital system negotiations, and co-pay assistance deployment—mapped against payer archetypes.
-
Commercial counterplay options for originators and biosimilars: pricing levers, contracting structures, and patient-support packages designed to preserve margin and share.
-
M&A and partnership screening tool: a structured rubric to evaluate asset-level fit and upside from bolt-on acquisitions or licensing deals within the complement-inhibition therapeutic area.
-
Compliance & REMS operational guide: stepwise protocols for pediatric and new-indication launches, aligned with the most recent regulatory modifications.
-
Manufacturing & supply resilience plan: risk heatmaps and mitigation options for contract-manufacturing relationships, including lead-time buffers and dual-sourcing criteria.
Strategic implications and recommended 2026 actions
-
For originator teams: prioritize evidence generation that supports durable clinical value and cost-effectiveness in negotiated indications. Strengthen patient-assistance and channel partnerships to blunt rapid biosimilar displacement.
-
For biosimilar competitors: focus early on commercial access tactics—payor contracting, specialized distribution, and demonstrable operational reliability of supply—to accelerate adoption in settings where price sensitivity is highest.
-
For payers and health systems: develop differentiated coverage pathways that reward demonstrated clinical and economic value. Scenario planning for multiple biosimilar entrants and staggered exclusivity expiries will reduce disruption to patient care.
-
For investors and M&A teams: use our scenario model to identify risk-adjusted acquisition targets and partnership structures that capture upside from label expansions while hedging biosimilar-driven margin compression.
Evidence base and methodology (concise)
The analysis synthesizes primary and secondary sources, regulatory filings, company disclosures, and proprietary market-access interviews carried out through 2026. Our forecasting approach blends bottom-up indication-level modeling with top-down market-consolidation effects and a Monte Carlo framework for uncertainty on payer responses and biosimilar uptake. The report’s appendices document assumptions and sensitivity ranges so that corporate finance and strategy teams can re-run scenarios under bespoke premises.
What we deliberately withhold in this preview
Consistent with the “trailer” principle, this introduction samples the report’s strategic depth while deliberately omitting detailed regional, type, and application-level breakouts and proprietary revenue shares. Those sub-segment data, including granular market-split figures and client-only micro-models, are included in the full report and our interactive forecast tool. This calibrated discretion ensures that readers get a rigorous strategic orientation here while preserving the full analytical utility for licensed users.
Next steps — how to use this intelligence in Q1–Q3 2026
-
Operationalize scenario testing: load your internal pricing and contract assumptions into our model to quantify three prioritized strategies (protect, compete, partner).
-
Run a payer stress test: use the provided payer-sensitivity matrix to assess margin vulnerability across major health systems and specialty pharmacy channels.
-
Activate an M&A filter: apply our screening rubric to potential targets whose projected contributions under central and upside cases exceed your hurdle rates.
-
Implement a supply resilience pilot: adopt at least two mitigation measures from our manufacturing checklist ahead of anticipated biosimilar volume shifts.
PW Consulting’s Soliris (Eculizumab) Market study is built for executives who must convert a complex, concentrated market into clear, time-sensitive decisions in 2026. For full access to the interactive forecast workbook, granular segmentations, and proprietary company profiles that underpin the recommendations above, please contact PW Consulting or visit our Soliris market page to license the complete report and tools.
For detailed analysis of this topic, please visit the official page: Soliris (Eculizumab) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Glove Box Market Set for 5% CAGR in 2026–2032 Forecast
By pmarketresearch, 2026-07-30
Glove Box Market — 2026 Strategic Primer (PW Consulting)
Executive snapshot
As organizations plan capital and sourcing decisions for 2026, the glove box market presents a measured but strategic growth opportunity. Using 2025 as the base year, PW Consulting’s latest market model estimates the global market at USD 215.0 Million (base year 2025), with the industry expanding through a 2026–2032 forecast window at a compound annual growth rate (CAGR) of approximately 5.0%. By the end of the forecast horizon the market is projected to be materially larger than the 2025 base, reflecting steady demand from specialty applications and increasing investment in controlled-environment manufacturing and laboratory infrastructure.
Glove Box Market
Historical behavior (2020–2025) shows resilience through cyclical pressures and episodic spikes driven by specific end-market investments — a pattern that informs near-term capital allocation. For 2026 decision-makers, this market sits at the intersection of advanced materials, battery production scale-up, pharmaceutical containment requirements, and laboratory modernization, creating multiple entry points for strategic initiatives.
Glove Box Market
Why this report matters for 2026 decisions
- Align capital plans with a market that is growing steadily: the supply-demand balance supports disciplined investment but requires targeted choices on product mix and supplier exposure.
- Understand supplier concentration and bargaining dynamics. The market exhibits a measurable level of concentration among leading suppliers, implying that procurement strategy must account for supplier negotiating leverage, quality continuity, and aftermarket service footprints.
- Factor material-cost sensitivity into sourcing and product design. Recent stainless steel price differentials across regions (for example, notable spreads between Northeast Asia and North America) materially affect unit economics for metal-dominant glove boxes and should be part of 2026 procurement scenarios.
- Prioritize certifications, containment assurance, and integration capabilities when qualifying vendors—particularly for high-compliance industries such as pharmaceuticals and battery materials production where containment and inert atmosphere performance are non-negotiable.
What the PW Consulting Glove Box Market report delivers (practical outputs)
- Transparent market sizing and trend analysis: validated base-year sizing (2025) and a clear, auditable forecast model (2026–2032) tied to application-level demand drivers.
- Demand-driver decomposition: qualitative and quantitative mapping of the end markets (pharmaceuticals, energy storage and battery materials R&D/production, electronics assemblage, and specialty industrial uses) and the operational levers that convert need into procurement.
- Segment-level strategic playbooks: for each product archetype (materials, enclosure construction types, turnkey isolators vs. modular glove boxes) the report provides positioning guidance, pricing archetypes, and buyer selection criteria—kept intentionally high-level here to preserve the premium value of the full dataset.
- Supply-chain and cost-sensitivity analysis: raw material price scenarios, lead-time risk matrices, and recommendations for hedging or local sourcing to reduce exposure to regional stainless steel price shocks.
- Competitive landscape with vendor capability matrices: independent profiles of market participants, product innovations, recent go-to-market moves, and aftermarket/service strength assessments.
- Actionable M&A and partnership screening checklist: prioritized capability sets and financial benchmarks for inorganic growth or strategic alliances, including exit scenarios and integration risk mapping.
- Procurement-ready tools: sample RFP language, technical specification templates, and TCO (total cost of ownership) model templates that can be adopted directly by engineering and sourcing teams in 2026.
Competitive landscape — what to watch in 2026
The vendor field is composed of specialized engineering-centric manufacturers and laboratory-equipment incumbents. Several firms are differentiated by deep domain expertise (e.g., battery production enclosures, vacuum-integrated glove boxes, or cleanroom integration), while others compete on speed-to-deploy and modular productization.
Glove Box Market
- Inert Corporation (US) — Known for custom-built inert atmosphere glove box systems and gas management solutions. Strengths: tailored system integration and gas-handling expertise for high-spec applications.
- Jacomex (France) — Specialist in custom glove box workstations, isolators, and neutral gas purification. Strengths: European engineering pedigree and formal quality management credentials.
- Vacuum Atmospheres Company (US) — Offers both custom and standard inert glove box systems with integrated vacuum deposition capabilities. Strengths: unique value for semiconductor and coating applications where vacuum integration is required.
- Vigor Technologies (USA) Inc — Focused on inert gas enclosures, glove boxes, purification systems and cleanroom equipment for battery and lab applications. Strengths: recent product and trade-show activity demonstrates a clear push into battery materials production scales.
- Labconco Corporation (US) — Laboratory equipment incumbent with Protector Series glove boxes for controlled research environments. Strengths: broad laboratory channel and aftermarket support.
- Coy Laboratory Products (US) — Known for custom glove box design and tailored controlled-environment solutions. Strengths: flexibility and bespoke engineering.
- Terra Universal (US) — Offers prebuilt and custom-manufactured glovebox systems, isolators, and accessories for labs and cleanrooms. Strengths: modularity and cleanroom integration capability.
- Plas-Labs, Inc. (US) — Compact and standard glove boxes for research and industrial applications. Strengths: rapid deployment options for bench-scale needs.
- Cleatech, LLC (US) — Laboratory supply and glove box systems with a focus on component supply and local servicing.
- GS GLOVEBOX Systemtechnik GmbH (Germany) — European supplier of glove box systems and containment solutions with engineering depth for industry-specific use cases.
Recent vendor developments are illustrative of strategic momentum: product launches tailored for battery materials manufacturing, trade show entries focused on energy storage markets, incremental product enhancements to increase shielding and longevity, and the maintenance/extension of quality certifications. These moves indicate vendor efforts to secure larger manufacturing customers and to capture lifecycle revenue through service agreements.
Strategic playbook for 2026
- Procurement hedging: institute a two-tier vendor strategy combining a primary long-term partner (for engineered solutions and lifecycle support) and secondary modular suppliers (for rapid deployment). This balances quality assurance with flexibility.
- Design for cost volatility: where stainless steel dominates a design, build sensitivity into the bill of materials and consider hybrid designs (metal exoskeletons + polymer internal panels) or localized sourcing to reduce input-cost exposure.
- Prioritize certifications and auditability: for regulated buyers, supplier ISO certifications and documented validation procedures are a precondition. Include audit clauses and service-level KPIs in 2026 contracts.
- Service and aftermarket as margin engine: structure contracts to capture post-installation service, calibration, and consumable supply. Vendors with field service networks can command premium pricing; buyers can reduce TCO by negotiating bundled multi-year support.
- Partner for battery-scale opportunities: vendors demonstrating capabilities in inert atmosphere control with vacuum integration or long-duration sealing are strategically positioned for battery material production. Consider co-development agreements or volume-offtake safeguards to secure supply.
- M&A and alliance screening: buy-side candidates should prioritize firms with strong engineering IP, proven manufacturing quality systems, and service networks; sell-side divestitures can extract value where scale advantages are limited.
- Pilot then scale: adopt a staged investment approach—small pilots for process validation followed by phased capital deployment tied to performance gates rather than immediate full-scale rollouts.
Risks and blind spots for 2026 planning
- Raw material volatility: recent regional price spreads for stainless steel highlight the need to model procurement scenarios and consider regional sourcing or inventory strategies.
- Supplier concentration: higher concentration among top vendors raises exposure to supply disruption and pricing pressure—mitigate with contractual protections and alternate sources.
- Regulatory and compliance shifts: evolving containment standards and laboratory regulations can impose retrofit costs; ensure contractual flexibility with vendors for compliance upgrades.
- Technology substitution: alternative enclosure materials or novel inert-handling approaches could alter long-term product economics—monitor early-stage innovations that threaten incumbent technology stacks.
How PW Consulting supports 2026 execution
- Board-level briefings that translate market sizing and forecast scenarios into capital-allocation recommendations and procurement timelines.
- Vendor due diligence and RFP execution support using PW’s procurement-ready templates and technical scoring models.
- Customized TCO and sensitivity analyses that incorporate raw material price scenarios, lead-time risk, and service-cost dynamics to inform contract length and warranty structures.
- M&A target screening and integration playbooks focused on capability scaling and service-network expansion.
- Operational pilots and rollout plans to validate performance in a staged manner before committing full production capital.
Next steps
The Glove Box Market is no longer a niche laboratory purchase: it is a strategic component in the value chains of pharmaceuticals, electronics, and energy storage. For executives preparing 2026 budgets, the right combination of supplier strategy, contract design, and staged deployment can materially improve time-to-market and lifecycle cost outcomes.
PW Consulting’s full report contains the detailed regional and application-level breakouts, segmentation tables, vendor scorecards, and downloadable financial models that underlie the recommendations summarized above. Access the full dataset and decision-support tools on our Glove Box Market report page to convert these strategic themes into executable 2026 plans.
For detailed analysis of this topic, please visit the official page: Glove Box Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com