

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Absolute Rotary Encoders Market Poised for 7.8% CAGR to 2032

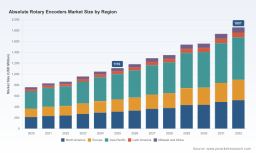
Absolute Rotary Encoders Market — Strategic Preview for 2026 Decision-Makers
Executive summary
As automation, robotics, and precision motion control accelerate across industries, absolute rotary encoders have moved from a niche sensing component to a strategic enabler of digital operations. PW Consulting’s Absolute Rotary Encoders Market study (base year 2025) synthesizes five years of historical performance and a forward-looking forecast through 2032, integrating technological adoption curves, supply-chain shifts, regulatory headwinds, and competitive positioning. With the market growing at a compound annual growth rate (CAGR) of 7.8% over the forecast horizon, executive teams must translate this macro momentum into product, procurement, and M&A choices in 2026 — quickly and with clarity.
Absolute Rotary Encoders Market
Why this research matters in 2026
- Timing: 2026 is a hinge year for converting pilots into scale. Investments made now in encoder capabilities and supplier relationships determine who secures the next wave of robotic, conveyor, packaging, and semiconductor automation spend.
- Risk management: Supply-side shocks, regulation-driven price adjustments, and accelerated specification expectations (higher resolution, broader environmental tolerances, integrated communications) make forward-looking scenario planning essential to avoid costly redesigns.
- Value capture: Companies that align product roadmaps, go-to-market motions, and strategic partnerships to the demand profile identified in this study will secure disproportionate margin and share gains.
Market trajectory — the macro picture
Our analysis places the global absolute rotary encoder market at a pivotal juncture in 2025 (base year), with clearly visible momentum into the late 2020s and early 2030s. The study quantifies the market’s expansion trajectory and models demand drivers across industrial automation, robotics, and adjacent applications. The projected CAGR of 7.8% reflects structural drivers — rising automation intensity, increased adoption of higher-resolution sensing, and tighter integration with industrial communication protocols — while accounting for cyclical exposure in capital equipment cycles.
Absolute Rotary Encoders Market
Beyond headline growth, the study maps the interplay between unit mix, feature premiuming (e.g., IO-Link, higher-bit resolutions), and pricing pressure. Scenario analysis in the report shows how a mix shift toward premium encoders versus commodity magnetic/inductive units materially alters supplier economics and channel dynamics through 2032.
Absolute Rotary Encoders Market
Key dynamics reshaping the landscape
- Technology convergence: In 2024 and beyond, a meaningful share of new encoder launches exhibited 24-bit resolution and integration of digital communications (including IO-Link). Low-latency designs and extended temperature ranges are becoming table stakes in several verticals.
- Product differentiation: Suppliers are differentiating along sensing modality (optical, magnetic, capacitive), mechanical robustness (IP ratings, stainless-steel casings), and safety certifications — creating distinct value tiers and pathway choices for OEMs and system integrators.
- Regulatory and trade pressures: Import surcharges and region-specific tariffs introduced since mid-2025 have shifted landed cost calculations for EU- and Singapore-origin products. These adjustments amplify the strategic importance of diversified manufacturing footprints and bilateral supplier agreements.
- Supply and materials: Design choices around housings and materials — such as stainless-steel casings used for enhanced vibration and shock protection — have implications for lead time, cost, and aftermarket reliability claims.
- Performance expectations: Reduced latency (sub-100 microseconds), higher-resolution encoders (multi-million position counts), and integrated diagnostics are moving from optional features to procurement prerequisites in several end markets.
Competitive landscape — who matters and why
The encoder market remains moderately concentrated at the top: the combined share of the three largest suppliers and the top five players indicate a market where established brands still govern key OEM relationships and standards conversations. That concentration rewards scale, channel reach, and engineering depth, but it also leaves openings for focused innovators that can deliver step-change performance or tailored solutions for niche applications.
Selected supplier archetypes highlighted in the study:
- Established industrial specialists — companies with deep automation credentials and broad protocol support. These players are winning large, system-level deployments by coupling product breadth with field engineering and service capabilities.
- High-precision innovators — firms that advance sensing physics (capacitive, optical) and offer high-bit resolutions targeted at robotics, semiconductor tooling, and defense applications.
- Ruggedized and hazardous-area providers — suppliers that combine explosion-proof ratings and high IP protection with domain-specific certifications for oil & gas, mining, and chemical sectors.
- Compact and cost-focused vendors — manufacturers delivering small-form-factor encoders optimized for space-constrained automation and embedded motion systems.
The report examines individual company strengths and strategic postures. For example, enterprises offering IO-Link enabled models and robust software diagnostics are increasingly positioned as preferred partners for Industry 4.0 implementations. Manufacturers advancing capacitive and electric-encoder technologies have clear differentiation in precision segments. Meanwhile, firms emphasizing heavy-duty form factors and certification portfolios remain the default choice for harsh-environment installations.
Recent developments and strategic implications
- Trade show and product activity through 2024–2026 demonstrates where R&D and marketing energy is concentrated. New exhibitor showcases and catalog updates signal prioritization of robot- and semiconductor-focused product lines.
- Product launches of compact and high-resolution devices indicate supplier bets on collaborative robotics and miniaturized systems — an area where early partnerships with cobot OEMs can lock in preferred supplier status.
- Catalog refreshes and updated series releases suggest suppliers are refreshing core platforms to support new interface standards and durability expectations.
What the full PW Consulting report delivers (practical modules)
- Market sizing and seven-year forecast (2026–2032) with scenario modeling that isolates demand sensitivity to resolution-premiuming, communication integration, and macro capital expenditure cycles.
- Detailed competitive profiles and capability matrices — not just who the players are, but how they win: channel models, service footprints, IP strength, and feature roadmaps.
- Go-to-market playbooks for OEMs, distributors, and system integrators — including channel segmentation, pricing tactics, and customization levers that protect margin while scaling volume.
- Supply-chain stress-testing and landed-cost models that incorporate recent tariff and surcharge developments, raw-material constraints, and alternative sourcing scenarios.
- Product development and specification toolkit — practical guidance on resolution choices, communication stacks (including IO-Link adoption), environmental sealing, and latency targets mapped to end-market ROI thresholds.
- M&A and partnership shortlist: quantified screening criteria and due-diligence checklists to prioritize inorganic growth or strategic alliances in 2026.
- Field-validated case studies and supplier selection frameworks to accelerate procurement cycles and reduce time-to-production for new encoder integrations.
How executives should use this study in 2026
- Strategic procurement: Reassess supplier portfolios with a two-tier approach — secure long-lead components with diversified sources while negotiating performance-based contracts for premium modules.
- Product roadmap alignment: Prioritize upgrades that unlock the highest willingness-to-pay in target verticals (e.g., higher resolution plus integrated diagnostics for robotics; ruggedization and certifications for industrial processes).
- Channel and revenue playbook: For manufacturers, develop bundled offerings (encoder plus diagnostics software) to migrate customers to subscription-style services and aftermarket revenue.
- M&A and partnership tactics: Use the report’s screening tools to identify bolt-on capabilities (precision sensing, IO-Link stacks, or hazardous-area certification) that accelerate penetration into strategic segments.
- Risk mitigation: Employ the supply-chain models to quantify the impact of regional surcharges and to prioritize local assembly, dual-sourcing, or strategic inventory buffers where justified by margin and uptime risk.
Conclusion — why access the full intelligence
The Absolute Rotary Encoders Market study is structured to move executives from high-level awareness to executable decisions in 90 days. It combines empirical market sizing, robust scenario analysis, supplier intelligence, and actionable playbooks to inform 2026 capital allocation, product development, and M&A. This preview demonstrates the study’s strategic depth without disclosing the granular segmentation data and proprietary forecasts that the full report contains — insights that buyers, OEMs, and investors will need to operationalize the opportunities identified here.
For teams preparing budgets, syndicating supplier strategies, or evaluating acquisition targets in 2026, this research is designed to be the single-source reference that aligns commercial, engineering, and procurement priorities. Visit our report page to obtain the full dataset, interactive models, and the hands-on implementation toolkit that accompany PW Consulting’s Absolute Rotary Encoders Market study.
For detailed analysis of this topic, please visit the official page: Absolute Rotary Encoders Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com