

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Glove Box Market Set for 5% CAGR in 2026–2032 Forecast

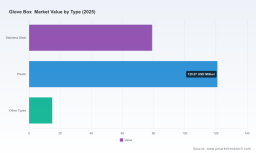
Glove Box Market — 2026 Strategic Primer (PW Consulting)
Executive snapshot
As organizations plan capital and sourcing decisions for 2026, the glove box market presents a measured but strategic growth opportunity. Using 2025 as the base year, PW Consulting’s latest market model estimates the global market at USD 215.0 Million (base year 2025), with the industry expanding through a 2026–2032 forecast window at a compound annual growth rate (CAGR) of approximately 5.0%. By the end of the forecast horizon the market is projected to be materially larger than the 2025 base, reflecting steady demand from specialty applications and increasing investment in controlled-environment manufacturing and laboratory infrastructure.
Glove Box Market
Historical behavior (2020–2025) shows resilience through cyclical pressures and episodic spikes driven by specific end-market investments — a pattern that informs near-term capital allocation. For 2026 decision-makers, this market sits at the intersection of advanced materials, battery production scale-up, pharmaceutical containment requirements, and laboratory modernization, creating multiple entry points for strategic initiatives.
Glove Box Market
Why this report matters for 2026 decisions
- Align capital plans with a market that is growing steadily: the supply-demand balance supports disciplined investment but requires targeted choices on product mix and supplier exposure.
- Understand supplier concentration and bargaining dynamics. The market exhibits a measurable level of concentration among leading suppliers, implying that procurement strategy must account for supplier negotiating leverage, quality continuity, and aftermarket service footprints.
- Factor material-cost sensitivity into sourcing and product design. Recent stainless steel price differentials across regions (for example, notable spreads between Northeast Asia and North America) materially affect unit economics for metal-dominant glove boxes and should be part of 2026 procurement scenarios.
- Prioritize certifications, containment assurance, and integration capabilities when qualifying vendors—particularly for high-compliance industries such as pharmaceuticals and battery materials production where containment and inert atmosphere performance are non-negotiable.
What the PW Consulting Glove Box Market report delivers (practical outputs)
- Transparent market sizing and trend analysis: validated base-year sizing (2025) and a clear, auditable forecast model (2026–2032) tied to application-level demand drivers.
- Demand-driver decomposition: qualitative and quantitative mapping of the end markets (pharmaceuticals, energy storage and battery materials R&D/production, electronics assemblage, and specialty industrial uses) and the operational levers that convert need into procurement.
- Segment-level strategic playbooks: for each product archetype (materials, enclosure construction types, turnkey isolators vs. modular glove boxes) the report provides positioning guidance, pricing archetypes, and buyer selection criteria—kept intentionally high-level here to preserve the premium value of the full dataset.
- Supply-chain and cost-sensitivity analysis: raw material price scenarios, lead-time risk matrices, and recommendations for hedging or local sourcing to reduce exposure to regional stainless steel price shocks.
- Competitive landscape with vendor capability matrices: independent profiles of market participants, product innovations, recent go-to-market moves, and aftermarket/service strength assessments.
- Actionable M&A and partnership screening checklist: prioritized capability sets and financial benchmarks for inorganic growth or strategic alliances, including exit scenarios and integration risk mapping.
- Procurement-ready tools: sample RFP language, technical specification templates, and TCO (total cost of ownership) model templates that can be adopted directly by engineering and sourcing teams in 2026.
Competitive landscape — what to watch in 2026
The vendor field is composed of specialized engineering-centric manufacturers and laboratory-equipment incumbents. Several firms are differentiated by deep domain expertise (e.g., battery production enclosures, vacuum-integrated glove boxes, or cleanroom integration), while others compete on speed-to-deploy and modular productization.
Glove Box Market
- Inert Corporation (US) — Known for custom-built inert atmosphere glove box systems and gas management solutions. Strengths: tailored system integration and gas-handling expertise for high-spec applications.
- Jacomex (France) — Specialist in custom glove box workstations, isolators, and neutral gas purification. Strengths: European engineering pedigree and formal quality management credentials.
- Vacuum Atmospheres Company (US) — Offers both custom and standard inert glove box systems with integrated vacuum deposition capabilities. Strengths: unique value for semiconductor and coating applications where vacuum integration is required.
- Vigor Technologies (USA) Inc — Focused on inert gas enclosures, glove boxes, purification systems and cleanroom equipment for battery and lab applications. Strengths: recent product and trade-show activity demonstrates a clear push into battery materials production scales.
- Labconco Corporation (US) — Laboratory equipment incumbent with Protector Series glove boxes for controlled research environments. Strengths: broad laboratory channel and aftermarket support.
- Coy Laboratory Products (US) — Known for custom glove box design and tailored controlled-environment solutions. Strengths: flexibility and bespoke engineering.
- Terra Universal (US) — Offers prebuilt and custom-manufactured glovebox systems, isolators, and accessories for labs and cleanrooms. Strengths: modularity and cleanroom integration capability.
- Plas-Labs, Inc. (US) — Compact and standard glove boxes for research and industrial applications. Strengths: rapid deployment options for bench-scale needs.
- Cleatech, LLC (US) — Laboratory supply and glove box systems with a focus on component supply and local servicing.
- GS GLOVEBOX Systemtechnik GmbH (Germany) — European supplier of glove box systems and containment solutions with engineering depth for industry-specific use cases.
Recent vendor developments are illustrative of strategic momentum: product launches tailored for battery materials manufacturing, trade show entries focused on energy storage markets, incremental product enhancements to increase shielding and longevity, and the maintenance/extension of quality certifications. These moves indicate vendor efforts to secure larger manufacturing customers and to capture lifecycle revenue through service agreements.
Strategic playbook for 2026
- Procurement hedging: institute a two-tier vendor strategy combining a primary long-term partner (for engineered solutions and lifecycle support) and secondary modular suppliers (for rapid deployment). This balances quality assurance with flexibility.
- Design for cost volatility: where stainless steel dominates a design, build sensitivity into the bill of materials and consider hybrid designs (metal exoskeletons + polymer internal panels) or localized sourcing to reduce input-cost exposure.
- Prioritize certifications and auditability: for regulated buyers, supplier ISO certifications and documented validation procedures are a precondition. Include audit clauses and service-level KPIs in 2026 contracts.
- Service and aftermarket as margin engine: structure contracts to capture post-installation service, calibration, and consumable supply. Vendors with field service networks can command premium pricing; buyers can reduce TCO by negotiating bundled multi-year support.
- Partner for battery-scale opportunities: vendors demonstrating capabilities in inert atmosphere control with vacuum integration or long-duration sealing are strategically positioned for battery material production. Consider co-development agreements or volume-offtake safeguards to secure supply.
- M&A and alliance screening: buy-side candidates should prioritize firms with strong engineering IP, proven manufacturing quality systems, and service networks; sell-side divestitures can extract value where scale advantages are limited.
- Pilot then scale: adopt a staged investment approach—small pilots for process validation followed by phased capital deployment tied to performance gates rather than immediate full-scale rollouts.
Risks and blind spots for 2026 planning
- Raw material volatility: recent regional price spreads for stainless steel highlight the need to model procurement scenarios and consider regional sourcing or inventory strategies.
- Supplier concentration: higher concentration among top vendors raises exposure to supply disruption and pricing pressure—mitigate with contractual protections and alternate sources.
- Regulatory and compliance shifts: evolving containment standards and laboratory regulations can impose retrofit costs; ensure contractual flexibility with vendors for compliance upgrades.
- Technology substitution: alternative enclosure materials or novel inert-handling approaches could alter long-term product economics—monitor early-stage innovations that threaten incumbent technology stacks.
How PW Consulting supports 2026 execution
- Board-level briefings that translate market sizing and forecast scenarios into capital-allocation recommendations and procurement timelines.
- Vendor due diligence and RFP execution support using PW’s procurement-ready templates and technical scoring models.
- Customized TCO and sensitivity analyses that incorporate raw material price scenarios, lead-time risk, and service-cost dynamics to inform contract length and warranty structures.
- M&A target screening and integration playbooks focused on capability scaling and service-network expansion.
- Operational pilots and rollout plans to validate performance in a staged manner before committing full production capital.
Next steps
The Glove Box Market is no longer a niche laboratory purchase: it is a strategic component in the value chains of pharmaceuticals, electronics, and energy storage. For executives preparing 2026 budgets, the right combination of supplier strategy, contract design, and staged deployment can materially improve time-to-market and lifecycle cost outcomes.
PW Consulting’s full report contains the detailed regional and application-level breakouts, segmentation tables, vendor scorecards, and downloadable financial models that underlie the recommendations summarized above. Access the full dataset and decision-support tools on our Glove Box Market report page to convert these strategic themes into executable 2026 plans.
For detailed analysis of this topic, please visit the official page: Glove Box Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com