

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Probiotic Strains Market Set to Grow at 6.98% CAGR Through 2032

Probiotic Strains Market — A Strategic Briefing for 2026 Decision-Makers
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I present a high-level, decision-focused introduction to our new Probiotic Strains Market research. This briefing is designed as a “trailer”: it surfaces the analytical framework, strategic implications, and actionable playbooks that corporate leaders and investors need when setting 2026 priorities, while reserving the full, segment-level intelligence for the complete report.
Probiotic Strains Market
Market snapshot: momentum, scale and concentration
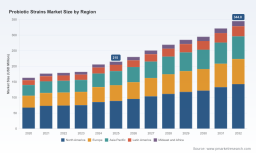
The probiotic strains market has transitioned from a nascent specialty ingredient sector into a structurally growing, commercially strategic category. Using 2025 as the base year, our top-line sizing estimates show the market expanding from approximately USD 163 million in 2020 to about USD 215 million in 2025. Under our base-case forecast this growth continues through 2032 at a compound annual growth rate (CAGR) of roughly 6.98%, reaching an overall market size near USD 345 million by 2032.
Probiotic Strains Market
Two structural features are particularly important for strategy in 2026. First, the market is moderately concentrated: the three largest suppliers together account for a majority share of market revenues, and the five largest suppliers widen that dominance further. Second, growth is neither uniform nor purely volume-driven — it is being re-shaped by regulatory gatekeeping, product-format innovation (e.g., co-fermentation beverage concepts and stabilized shelf-stable formulations), and scaling of contract manufacturing capabilities.
Probiotic Strains Market
Why 2026 is a strategic inflection point
-
Regulatory tightening and market access. New regulatory actions in 2026 — including import and registration requirements introduced by China’s customs authorities and updates to permitted-strain lists for infant nutrition — materially change go-to-market calculations for players seeking or maintaining access to Asia’s largest markets. These developments elevate compliance as a commercial differentiator.
-
Novel strains moving toward mainstream use. High-profile regulatory milestones (for example, notifications or clearances enabling commercial use of newly characterized strains) are lowering the technical and commercial risk of next-generation ingredients. The regulatory acknowledgment of strains sourced from human microbiota and promising candidates such as Akkermansia-related products points to a widening functional and therapeutic frontier.
-
Supply-side expansion and CDMO acceleration. Contract manufacturers are expanding probiotic-dedicated suites and capacity, which improves reliability for brand owners and reduces time-to-market for complex formulations. This capacity ramp enables larger launches but also intensifies competition to secure long-term supply agreements.
-
Commercial innovation beyond pills. Recent product launches leveraging multi-strain co-fermentation and high-activity single-strain formulations demonstrate consumer-ready use cases in dairy, juices, and reduced-sugar formats. These examples signal that formulation innovation, not only strain selection, is a primary value lever.
Competitive landscape — strategic archetypes and implications
Our competitive analysis identifies several archetypes among incumbent and emerging players. Understanding these archetypes helps inform partnership, M&A, and competitive defense strategies.
-
Strain library and IP specialists — firms with large proprietary collections and documented clinical dossiers for targeted indications. These players (exemplified by companies that offer hundreds of unique strains and curated blends) compete on depth of evidence and licensing potential. For corporates seeking differentiation via clinically substantiated claims, these suppliers are critical partners or acquisition candidates.
-
Application-focused formulators — companies that tailor strains for specific food categories (e.g., chilled dairy, plant-based, confectionery or gummies). Their capability lies in co-development with brand owners to meet sensory and shelf-life requirements. For consumer-packaged goods firms, these partners de-risk product development.
-
CDMO and scale manufacturers — contract manufacturers that specialize in live microorganism production, stability, and fill/finish. Recent capacity expansions by leading CDMOs double production throughput in some locales and remove a previous bottleneck for large-volume launches.
-
Specialist genus players — companies focused on specific genera (e.g., Bacillus or Lactobacillus) and applications where those genera offer technical advantages (heat-stability, gastrointestinal survival, oral health). These focused suppliers often excel in niche channels and ingredient cost-efficiency.
Strategically, a typical winning play for 2026 is a hybrid approach: secure a strategic supply anchor with a proven CDMO, license or partner with a strain-IP owner for clinical differentiation, and co-develop an application-formulation with an application specialist. This triple alignment compresses time-to-market while preserving claim defensibility.
Selected recent events shaping 2026 strategy (illustrative)
-
Regulatory: China introduced registration requirements for overseas manufacturers of foods and health foods containing probiotic strains — immediately affecting import-dependent brands and pushing more manufacturers toward onshore registration or local partnerships.
-
Commercial partnerships: Strategic alliances formed in 2026 to co-develop next-generation digestive wellness strains underscore an industry shift toward collaborative R&D and co-ownership models.
-
Product innovation: Market-visible launches of co-fermented beverages and high-activity single-strain drinks indicate rapid maturation of non-pill delivery formats and expanded consumer applications.
-
Capacity expansion: Major contract manufacturers announced dedicated probiotic suites and doubled capacity in strategic markets, materially reducing supply risk for high-volume customers.
Actionable playbook for corporate leaders in 2026
In the current phase, executives should prioritize a small set of high-impact moves that align with their scale and strategic intent.
-
Regulatory-first market entry: For companies targeting China and adjacent markets, make registration pathway mapping and strain permissibility screening the first item in every product development plan. Factor localization timelines into commercial launch calendars.
-
Supply anchoring: Negotiate minimum-volume commitments and dual-sourcing terms with CDMOs to secure continuity of supply, especially where strains require specialized upstream processes. Consider capacity reservation agreements in parallel with technical transfer clauses.
-
Evidence clustering: Invest selectively in randomized controlled trials or real-world evidence for core strain claims that align with your brand’s value proposition (e.g., digestive comfort, immune support, oral health). Clinical evidence remains the strongest barrier to commoditization.
-
Format innovation: Pair strain selection with application R&D: co-fermentation, microencapsulation, and sugar-reduced matrices are pathways to unique sensory and shelf-stability positions that command premium pricing.
-
Portfolio carve-outs for M&A: Identify small-to-mid cap strain owners or regional players with strong regulatory footholds as bolt-on targets. The market concentration metrics imply attractive consolidation opportunities for firms seeking rapid scale.
-
IP and compliance audits: Conduct an IP and regulatory readiness audit before any cross-border launch; the cost of a misstep in registrations or claims can eclipse near-term commercial gains.
Risks, mitigations and near-term stress tests
-
Regulatory volatility: Mitigation — maintain a regulatory monitoring function and an adaptive dossier-management process to rapidly respond to new country-level requirements.
-
Supply chain fragility: Mitigation — diversify by geography and process technology; build inventory buffers for launch-critical SKUs and include technical transfer milestones into supplier contracts.
-
Evidence erosion risk: Mitigation — develop layered evidence strategies (clinical, mechanism, consumer sensory) and align marketing claims tightly to validated endpoints.
-
Commoditization pressure: Mitigation — protect margin via formulation complexity, exclusive strain licenses, or route-to-market control (private label vs. branded partnerships).
What the full PW Consulting report delivers — a practitioner’s toolkit
Our comprehensive research package goes beyond this strategic preview. The full report is operationally focused and designed for immediate use by strategy, R&D, regulatory, supply chain, and M&A teams. Highlights include:
-
Market-sizing methodology and transparent assumptions (historical 2020–2025 validation and 2026–2032 scenarios).
-
Strain-level dossiers and clinical-evidence matrix for commercially relevant strains and emerging candidates.
-
Regulatory tracker and decision tree for priority markets, including registration pathways and claim frameworks.
-
Supplier and CDMO scorecard with capability maps (manufacturing platforms, QC systems, and capacity expansion timelines).
-
Commercial playbooks for five go-to-market archetypes: global brand, regional challenger, ingredient licensor, CDMO partner, and retail private-label operator.
-
M&A screen and target short-list with valuation vectors and integration risk assessments.
-
Operational checklist for commercialization (supply contracts, stability testing, claims substantiation, labeling and customs compliance) tailored to 2026 requirements.
Final perspectives — where value will be created in 2026
Value in the probiotic strains market this year will accrue to organizations that can orchestrate three capacities simultaneously: regulatory navigation, formulation engineering, and evidence generation. Firms that lock in compliant supply, pair differentiated strains with consumer-friendly formats, and back claims with rigorous evidence will capture outsized share as the category scales at nearly 7% CAGR toward 2032. Conversely, commoditized low-evidence suppliers and brands that underinvest in registration will face accelerated margin compression and market access constraints.
This briefing outlines the strategic contours. For granular segment analysis, company-by-company profiles, and the detailed playbooks required to operationalize a 2026 strategy, access our full Probiotic Strains Market report. The full package contains the proprietary data, models, and tactical templates that executive teams need to make risk-calibrated investments and commercial commitments with confidence.
For detailed analysis of this topic, please visit the official page: Probiotic Strains Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com