

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Flexographic Printing Plate Market to Reach USD 5,210M by 2025 at 2.3% CAGR

Flexographic Printing Plate Market — Strategic Preview for 2026 Decision-Makers
As PW Consulting’s lead industry analyst I present a focused preview of our comprehensive Flexographic Printing Plate Market study. Designed as a strategic “trailer,” this introduction demonstrates the analytic depth and practical value that our full report delivers to executives making pivotal 2026 decisions — while deliberately reserving granular segmentation outputs for the full publication to protect actionable intelligence.
Flexographic Printing Plate Market
Market trajectory: what the numbers tell us
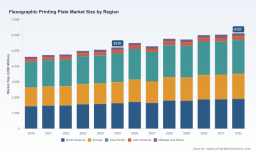
The flexographic printing plate market has demonstrated steady expansion through the first half of the decade. Our topline sizing shows growth from a market base of approximately USD 4,610 million in 2020 to roughly USD 5,210 million in 2025. PW Consulting’s modeling anticipates the market crossing a near-term inflection point in 2026 before continuing to 2032 with a compound annual growth rate (CAGR) of about 2.3% across the forecast window. The 2026 estimate signals renewed demand dynamics as converters adapt to sustainability mandates and modernize production workflows.
Flexographic Printing Plate Market
These aggregate figures mask important structural shifts — notably a concentration profile that favors a small group of vertically integrated suppliers. The market concentration metrics indicate meaningful share held by the top-tier players, creating both stability and barriers for faster-moving challengers. For 2026 strategic plans, executives should interpret the headline growth as an invitation to refine positioning rather than a signal to pursue broad-market expansion without targeted priorities.
Flexographic Printing Plate Market
Why this preview matters for 2026 strategic choices
- Capital allocation under regulatory pressure: Sustainability regulations and packaging waste directives are reshaping capital priorities across converters and plate manufacturers. Investments in cleaner plate processing (e.g., water-washable technologies and solvent-free workflows) are increasingly table stakes for market access, particularly in regulated geographies.
- Technology transition management: The rise of direct imaging, automated plate processing, and press-ready eco-friendly plate workflows creates a bifurcation: adopters capture workflow cost advantages and faster time-to-press; laggards risk margin erosion and lost contracts. 2026 is a pivotal year to decide on phased vs. wholesale technology adoption.
- Supplier strategy and risk mitigation: Concentration among leading suppliers means buyer-supplier relationships, long-term contracts, and co-development agreements will be determinative. Our full report outlines how to balance supplier consolidation benefits with contingency sourcing to protect throughput continuity.
- M&A and partnership levers: Given the moderate CAGR, inorganic growth and capability tuck-ins (imaging, finishing, substrate expertise) are effective ways to outpace market growth. We identify acquisition archetypes likely to deliver immediate EBITDA uplift and strategic differentiation.
Practical intelligence included in the full PW Consulting study
The report is built to be operationally useful to procurement leads, R&D heads, commercial strategists, and private equity sponsors. Highlights you can expect (outlined here at a high level) include:
- Robust market-sizing and forecasting methodology with transparent assumptions and scenario variants for low-, base-, and high-growth paths.
- Demand-driver mapping linking end-market packaging trends, substrate shifts (including recycled and mono-materials), and regulatory catalysts to plate demand profiles.
- Technology and cost-to-serve benchmarks covering photopolymer, rubber, and alternative plate systems, with practical guidance on lifecycle TCO and break-even horizons for automation investments.
- Supply-chain and input-cost analysis highlighting key raw-material sensitivities, logistics bottlenecks, and inventories-to-sales indicators that matter for 2026 planning.
- Commercial playbooks for price negotiation, service-bundling, and converter enablement strategies that protect margins while accelerating uptake of sustainable plate solutions.
- Corporate strategy tools: M&A screening filters, integration checklists, and partnership frameworks that align with the current competitive dynamics.
- Executable risk scenarios tied to regulatory rollouts and substrate adoption curves, coupled with recommended mitigation actions and trigger points for management responses.
Competitive landscape: what the leading players are doing (strategic takeaways)
The competitive architecture is dominated by a cohort of legacy materials manufacturers, imaging systems providers, and specialty rubber and polymer houses. These firms are pursuing complementary strategies — platform optimization, sustainability leadership, and process automation — that define where value will accrue in 2026 and beyond. Below are synthesized strategic profiles of the most consequential participants.
- DuPont (United States) — Market leader in photopolymer plates with digital HD solutions. DuPont’s emphasis on high-resolution digital flexo positions it to capture premium quality-sensitive segments. For buyers, DuPont remains a primary partner for advanced color-critical packaging applications.
- Asahi Kasei (Japan) — A front-runner in water-washable and solvent-free photopolymer plates. Asahi’s demonstrations of gravure-level print on recycled substrates and sustainability certifications align it with converters prioritizing PPWR-compliant production and reduced solvent footprints.
- MacDermid Graphics Solutions (United States) — Offers an integrated digital photopolymer plate ecosystem. Their strategy balances established analog strengths with digital migration paths for converters seeking stepwise modernization.
- Flint Group (Germany) — Comprehensive plate portfolio tailored to packaging converters. Flint’s breadth gives it a competitive edge when clients require single-vendor sourcing of inks, plates, and prepress systems.
- Fujifilm (Japan) — Focused on high-quality Flenex plate technology designed for elevated print performance. Fujifilm targets premium brand-pack applications where visual differentiation justifies investment.
- Esko (Belgium) — Specializes in imaging and plate processing systems; recent showcases emphasize automated water-washable solutions tailored to compliance with emerging packaging-waste regulations. Esko’s systems are critical for converters pursuing automated, compliant workflows.
- Kodak (United States) — Maintains a balanced photopolymer and plate solution set, competing on digital integration and workflow optimization.
- Toyobo (Japan), Harper Corporation (United States), Trelleborg (Sweden) — These firms cover advanced photopolymer and rubber plate niches, serving converters with specific substrate or machine compatibility needs.
Collectively, the top-tier players exhibit a high level of market control, reflecting an oligopolistic tendency that favors scale, integrated solutions, and regulatory-compliant product portfolios. This configuration creates distinct options for market entrants: specialize in niche substrate compatibility or partner with existing platform providers to gain distribution access quickly.
Recent industry dynamics shaping 2026
- Sustainability & compliance: Live demonstrations in 2026 showcased press-ready eco-friendly plates produced via direct imaging dry-film lamination and automated water-washable workflows. These developments reinforce the view that regulatory alignment (including PPWR-related implications) is a non-negotiable requirement for commercial participation in many markets.
- Process automation & digitalization: Exhibitions highlighted automated CI flexographic printing and imaging systems that reduce operator variability and speed make-ready times. Automation is now a primary lever for cost-per-unit reduction.
- Quality convergence: Industry forums reported gravure-level output achievable on flexo with modern plates and process controls — an opportunity for flexo to reclaim share from other printing technologies in several packaging segments.
How executives should apply this intelligence in 2026
- Procurement: Use multi-year rolling contracts with technology clauses that provide upgrade pathways tied to compliance milestones. Price alone will not secure supply; technical compatibility and sustainability credentials will be decisive.
- Operations & CapEx: Prioritize investments that reduce water and solvent use, improve throughput via automation, and enable press-ready plate adoption to cut total lifecycle costs.
- Commercial & R&D: Align product roadmaps to recycled substrate performance and gravure-level quality where brand owners are willing to pay for differentiation.
- M&A & partnerships: Focus on bolt-ons that add imaging or finishing capabilities, or regional distribution assets that accelerate market access without duplicative scale costs.
Final note — what’s withheld here and why
This preview intentionally demonstrates analytic scope and strategic relevance while withholding the granular segmentation tables, region-by-region shares, and specific application split metrics that power deal-level decisions. That level of disaggregated intelligence — including driver-weighted demand curves, modelled price elasticity, and executable channel strategies — is available in the full PW Consulting study and is essential for transaction diligence, procurement renegotiation, and capex justification.
Next steps
For procurement leads, corporate strategists, and PE sponsors planning 2026 actions, the full report offers the quantitative models, sensitivity scenarios, and supplier scorecards required to move from strategy to execution. Contact PW Consulting to access the complete dataset, scenario models, and tailored advisory support for turning the market’s steady growth and structural shifts into defensible competitive advantage.
For detailed analysis of this topic, please visit the official page: Flexographic Printing Plate Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com