

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Category: market research
PW Consulting: Worldwide Narrow-Body Aircraft MRO Market Poised for 5.6% CAGR Through 2032
By pmarketresearch, 2026-08-12
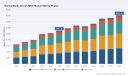
PW Consulting: Strategic Outlook — Worldwide Narrow-Body Aircraft MRO Market (Base Year 2025) — A Decision-Grade Briefing for 2026
PW Consulting today releases an executive briefing accompanying our full market study, Worldwide Narrow Body Aircraft MRO Market. The briefing synthesizes the study’s strategic implications for industry leaders, investors, and operators making binding decisions in 2026. Our analysis shows the global narrow-body MRO market recovering and expanding from a post‑pandemic base — with the market valued at approximately USD 55.2 billion in 2025 and projected to grow at a 5.6% CAGR through the 2026–2032 forecast window, reaching roughly USD 80.9 billion by 2032. This trajectory underscores material opportunity — and material execution risk — for stakeholders across the aftermarket value chain.
Worldwide CRM and Customer Experience Implementation Services Market
Why this report matters now
-
Timing pressure: Fleet deployments and OEM delivery ramps in 2026 force hard capital and capacity decisions today. Facilities, licensed capabilities and long-lead spare contracts require commitments measured in quarters, not months.
Barcode Scanner Batteries Market -
Margin leverage: Rising labor and materials costs compress repair margins unless operations and commercial terms are proactively re‑engineered. Our study quantifies the margin sensitivity to cost inflation in scenarios relevant to narrow‑body platforms.
Disposable Hospital Curtain Market -
Competitive inflection: Market concentration metrics indicate that incumbents retain meaningful share but do not preclude aggressive entrants or capacity-driven regional shifts. The top-three MRO providers account for roughly 31.4% of market throughput, while the top-five represent about 42.9%, creating both competitive clustering and white‑space pockets for specialised plays.
-
Regulatory and certification gatekeepers: Engine platform licensing — notably for the LEAP family — is a determinative capability that reshapes capability economics, shop utilization and OEM/MRO commercial relationships.
What the full report delivers (practical, non‑generic tools)
-
Demand and capacity scenarios: Three operational scenarios (Constrained Supply, Balanced Growth, and Capacity Overflow) model shop utilization by aircraft vintage and engine family through 2032, enabling capital timing and lease-versus‑build arbitration.
-
Executable commercial playbooks: Contract archetypes and negotiation levers for airlines, lessors and independent providers — including guaranteed-availability structures, risk‑sharing frameworks, and inventory consignment clauses tailored to narrow‑body flows.
-
Cost-to-serve matrix and profitability model: A playable spreadsheet model that isolates labor, material, overhead and logistics drivers for narrow‑body shop visits; parametrised for regional wage inflation and material shocks so teams can stress-test pricing.
-
Supply chain resilience toolkit: Risk heatmaps for critical spares, second‑tier suppliers and lead‑time exposure, alongside a prioritised action list for alternative sourcing, strategic stocking and vendor qualification.
-
Workforce and skills roadmap: A three‑phase talent plan to close certified mechanic gaps — recruitment, upskilling partnerships, and productivity levers — with projected ROI under varied wage inflation paths.
-
Deal and M&A screening templates: Quick‑score checklists and valuation sensitivities for bolt‑on acquisitions, capability buys (e.g., engine shop certifications) and JV structures that accelerate market entry.
-
Benchmarking database: Operational and commercial KPIs for leading narrow‑body MRO facilities — utilization, turnaround times, shop‑visit mix and select unit cost indices — structured to support target-setting without disclosing client‑level confidentiality.
Market dynamics shaping 2026 decisions
-
Recurring demand dominance: Narrow‑body fleets remain the engine of global short‑haul travel and therefore of recurring MRO volume. This creates predictable baseline demand but also concentrates exposure to single‑platform shocks and delivery cadence shifts.
-
Labor and material inflation are real and quantifiable: Industry surveys indicate skilled labor shortages persist, with wage inflation near 6.6% in 2024 and projected around 5.7% in 2025; material costs surged about 7.7% in 2024 with a continued elevated trajectory into 2025. These inputs materially affect shop economics and must be incorporated into 2026 contracting and capex plans.
-
Supply chain friction: Parts availability and production delays continue to extend turnaround times and reduce throughput. Our models show that even moderate elongation of critical lead times can reduce effective shop capacity and materially increase working capital needs.
-
Certification as a strategic moat: Specialized licensing and technical capability for prime narrow‑body engine families — notably the LEAP series used on current neo/MAX platforms — are differentiators. Providers that obtain or expand “Premier” capability capture higher‑value shop visits and ancillary revenue.
Competitive landscape: who’s shaping the market
-
Lufthansa Technik — A broad capability set across base and line maintenance, engine overhaul and platform modifications, supported by a global footprint and large dedicated narrow‑body facilities. Their multi‑site capacity and OEM relationships make them the reference integrator for airline and lessor partners.
-
ST Engineering Aerospace — The largest independent airframe MRO by man‑hours, with aggressive capacity expansion in engine MRO. Their recent facility investments are designed to capture incremental CFM56 and LEAP demand in Asia‑Pacific and beyond.
-
AAR Corp. — A North American independent with targeted narrow‑body capabilities and capacity expansion in strategic hubs. Their playbook blends landing‑gear, component and airframe specialization to win regional airline business.
-
Delta TechOps — An airline‑affiliated powerhouse with unique licensed capability for both LEAP variants in North America, giving it a durable competitive advantage for carrier and third‑party shop visits on neo and MAX platforms.
-
SR Technics — Focused engine heavy shop visits and component MRO with recent multi‑year agreements that demonstrate the persistent opportunity in legacy narrow‑body engine support.
-
HAECO, Turkish Technic, Iberia Maintenance, TAP Maintenance & Engineering — Regional leaders with capacity and contract wins that make them pivotal partners for operators in their respective theatres, often leveraging airline affiliations or airport privileges to secure flow‑through business.
Recent commercial moves underscore the market’s directional signals: expanded LEAP capability among airline MROs, multi‑year engine support deals, and greenfield capacity openings targeted at doubling shop throughput for high‑volume narrow‑body engine platforms. These are not isolated events — they are coordinated strategic bets that change the competitive map for serviceables and capacity allocation through 2027.
Strategic imperatives for 2026 (what to do next)
-
Prioritise capability, not just capacity. Where licensing (e.g., LEAP) provides revenue uplift and margin protection, accelerate certification and vendor relationships rather than incremental hangar additions alone.
-
Hedge material risk via dual‑sourcing and targeted inventory. Short-term working capital for key rotables reduces disruption risk and can be priced into service agreements to protect margins.
-
Revisit commercial models: transition from transactional shop‑visits toward outcome‑linked contracts (availability, reliability) to capture higher lifetime value from airline partners.
-
Invest in predictive maintenance and digital workflows to recover turnaround time and improve shop throughput; the ROI is compelling when staged against current wage and material inflation scenarios.
-
Adopt selective partnerships or bolt‑on M&A to access certifications and customer funnels quickly; internal build options are long and capital‑intensive.
-
Embed scenario planning in capital approvals: require stress‑tested utilization curves and sensitivity to 10–20% shifts in lead times and labor cost trajectories.
How PW Consulting supports executable decisions
-
Tailored workshops that run your commercial, operations and finance teams through the report’s scenario models and the provided cost‑to‑serve toolset.
-
Benchmarking and confidential peer comparisons to validate your shop economics against the market without exposing proprietary client data.
-
Deal advisory for JV formations, capacity investments and acquisition screening, using our forecast model to stress test valuations under multiple macro environments.
-
Implementation support for capability upgrades—project scoping for certification pathways, capex phasing, and workforce plans aligned to delivery timelines.
Our study provides both the strategic perspective and the tactical instruments that management teams need to move from analysis to action in 2026. For those who want the complete intelligence — including the full, granular breakdowns by region, activity and aircraft generation, the proprietary scenario files, and the benchmarking datasets referenced here — download the full report or contact PW Consulting for a personalized briefing. The headline numbers and directional drivers presented in this briefing only scratch the surface; the full deliverable is designed for immediate operationalisation.
Contact PW Consulting to schedule a 2026 strategy session and to obtain the comprehensive dataset and model licenses that will allow your team to translate forecast into competitive advantage.
For detailed analysis of this topic, please visit the official page: Worldwide Narrow Body Aircraft MRO Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report: Worldwide Areca Nut Market to Expand at 3.88% CAGR Through 2026–2032
By pmarketresearch, 2026-08-12
Worldwide Areca Nut Market 2026: Strategic Intelligence for Decision-Makers
PW Consulting’s latest Worldwide Areca Nut Market report is released at a pivotal moment for producers, processors, traders and investors. After a period of steady recovery and consolidation, the global areca nut market crossed the USD 1 billion revenue threshold in our base year (2025) and is forecast to climb into the early USD‑1.1 billion range in 2026, expanding at a projected compound annual growth rate (CAGR) of 3.88% through the 2026–2032 forecast window. This release is designed as a practical, executive-grade briefing: it demonstrates the analytical depth that underpins our conclusions while intentionally withholding granular proprietary splits so practitioners are encouraged to consult the full report for the underlying datasets and tactical playbooks.
Worldwide Cloud Management Tools Market
Why 2026 Is a Strategic Inflection Point
- Market Scale and Trajectory: The market’s recovery from the mid‑decade volatility is now measurable and meaningful. Crossing the USD 1 billion mark in 2025 has altered the calculus for mid‑sized processors and exporters—scale economics are becoming decisive in unit-cost competitiveness.
- Concentration and Competitive Dynamics: Market concentration is moderate, with the top three and top five players controlling material shares of global flows. This creates room for regional champions and niche operators to capture value through quality, certification and differentiated service propositions.
- Regulatory and Trade Friction: Heightened regulatory scrutiny in destination markets, trade protection measures in producing countries, and public‑health classifications are converging to make compliance and market access as important as raw production volumes.
What the Report Covers — Practical, Actionable Intelligence
This study is structured for immediate use in 2026 decision cycles. It contains:
Wi-Fi + Bluetooth Combo ICs Market
- Macro and medium‑term demand scenarios, stress‑tested across regulatory shock, input‑cost inflation and substitution risks;
- Supply‑chain mapping from farmgate through processing, trade and logistics nodes, highlighting bottlenecks and cost pools that determine competitive margin;
- Operational playbooks covering mechanization opportunities, post‑harvest loss reduction, and optoelectronic sorting and hygienic packaging upgrades that demonstrably improve export eligibility;
- Regulatory risk framework and mitigations—covering import controls, food‑safety alerts, labelling and municipal restrictions—aligned with likely enforcement trajectories through 2032;
- Investor briefs and valuation frameworks for M&A, greenfield processing investments and contract farming models, including sensitivity analyses for input‑cost shocks;
- Commercial go‑to‑market templates for processors and exporters focused on market diversification, buyer qualification and certification roadmaps;
- Primary‑research insights derived from grower interviews, processing site visits, buyer panels and customs/trade flow triangulation, supported by a reproducible methodology appendix.
Competitive Landscape — Who Moves the Market
The industry remains anchored by a mix of cooperatives, regional processors and export specialists. Our report profiles the leading operators and evaluates their strategic orientation and operational levers:
Worldwide Blackcurrant Seed Oil Market
- The CAMPCO Ltd (India): A cooperative model that combines procurement scale with value‑added processing and organic initiatives. CAMPCO’s recent investment in warehousing and procurement infrastructure signals a focus on farmer capture, quality traceability and supply stabilization.
- GM Group and established Indian traders/processors: These firms remain agile on grading and logistics, with export channels that underpin price discovery for origin markets.
- Surya Exim and other export‑oriented processors: Facility upgrades (including optical sorting and hygienic packaging) are reshaping export readiness; firms that modernize quickly gain access to high‑value buyers requiring documented food‑safety compliance.
- Regional suppliers in Indonesia and Vietnam: These players supply differentiated origin lots and have a strategic role in smoothing seasonality for global buyers; their quality and consistency investments determine premium access.
- Specialist traders and smaller processors: They continue to serve fast‑moving domestic and regional end‑uses, but face margin squeeze unless they upgrade value chains or consolidate.
Recent operational developments underscore these trends. Notably, CAMPCO’s infrastructure expansion and Surya Exim’s commissioning of advanced sorting lines reflect a broader shift toward capital‑intensive quality assurance. Public sector initiatives—such as state‑level agro‑processing clusters—are lowering the barrier to mechanized processing and post‑harvest loss reduction for smallholders, influencing where future processing scale will anchor.
Regulation, Health Classification and Trade Policy — Navigating the Non‑Market Risks
Three regulatory vectors are shaping strategy in 2026:
- Import controls and food‑safety enforcement in major consuming markets remain active. For example, destination market import alerts and detention practices create asymmetric costs for exporters who cannot demonstrate robust controls.
- Origin‑market trade policy and protectionist measures raise domestic price floors and create export disincentives unless exporters can demonstrate value‑addition and foreign‑exchange returns.
- Public‑health classifications and municipal bans affect downstream markets and brand positioning. These drive buyers towards certification, traceability and reformulation strategies for alternative uses.
Our guidance is explicit: exporters and brand owners must invest in documented food‑safety systems and upstream traceability to defend market access and price realization. Firms that ignore these forces will face rising rejection rates, insurance cost increases and reputational dilution.
Raw Materials and Cost Pressures — Strategic Responses
Agricultural input inflation—particularly in fertilizers and crop protection—has raised smallholder cost of production materially. The result is a risk of supply volatility unless mitigations are adopted. The report provides a set of operational responses:
- Contract farming and price‑sharing mechanisms to stabilize supplies and improve input procurement efficiency;
- Targeted mechanization and pack‑line investments that reduce labour intensity and post‑harvest losses;
- Productivity interventions (nutrient management, integrated pest management) that reduce chemical‑input dependence and improve sustainability credentials;
- Financial instruments and working‑capital structures that protect processors from intra‑season price swings.
Value‑Chain and Commercial Playbooks for 2026
We translate market analytics into executable strategies for four archetypal stakeholders:
- Producers / Cooperatives: Focus on aggregation, quality segmentation and backward integration into cleaning/primary processing. Public‑private collaboration for cluster‑level mechanization can be a force multiplier.
- Processors / Exporters: Prioritize capital investment in sorting, hygienic packing and certification. Implement multi‑market diversification to reduce exposure to any single enforcement regime.
- Traders / Distributors: Invest in digital traceability and buyer assurance packages; shift towards managed inventory solutions to capture premium for guaranteed quality.
- Investors / PE Funds: Seek bolt‑on consolidation targets with controllable quality upgrades and route‑to‑market access; insist on regulatory compliance as a precondition for valuation multiples.
Scenarios and Financial Implications
The report presents three plausible 2026‑2032 scenarios—base, downside (regulatory tightening and input‑cost shock) and upside (quality premium and new industrial demand). Each scenario is accompanied by modeled P&L and capex schedules to inform investment committees. For boardrooms planning capex in 2026, the message is clear: timing and choice of investment matter. Early movers that secure feedstock via contracting and prioritize compliance often achieve payback curves materially superior to late entrants.
How This Report Helps Executives in 2026
- It converts industry noise (import alerts, duty changes, health classifications) into decision heuristics that can be applied in procurement, capex and market‑entry choices;
- It supplies a prioritized investment agenda—what to spend on first (sorting, cold storage, traceability) and why—linked to measured impact on export access and margin;
- It offers actionable M&A screening criteria built around quality improvement potential, trade compliance status and supply‑base control; and
- It equips risk teams with a tested playbook for regulatory contingencies, including certification pathways and buyer remediation protocols.
Partial Disclosure — Why You Need the Full Report
In keeping with our “trailer” approach, this release outlines the analytical architecture and high‑level conclusions—but does not disclose the granular segmental revenue breakdowns, per‑region unit economics or proprietary buyer‑level datasets that underpin valuation and procurement recommendations. Those datasets and the supporting spreadsheets are included in the full PW Consulting report and are essential for transaction diligence, contract negotiation and board‑level financial modeling.
Next Steps for Readers
For executives preparing 2026 budgets, the immediate priorities are to: (1) audit export compliance and certification readiness, (2) stress‑test procurement under multiple input‑price scenarios, and (3) sequence capital investment to capture quality premiums. PW Consulting’s full report provides the necessary datasets, model templates and vendor shortlists to operationalize these steps.
Accessing the complete report will equip your team with the empirical detail and playbooks needed to execute confidently in 2026. Visit PW Consulting’s report page for download access, executive briefings and bespoke advisory engagements designed to translate market intelligence into measurable commercial outcomes.
For detailed analysis of this topic, please visit the official page: Worldwide Areca Nut Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Chinese Domestic Databases Market to Expand at 18.5% CAGR Through 2032, Forcing Rethink of On‑Premise vs Cloud Strategies
By pmarketresearch, 2026-08-12
PW Consulting Strategic Brief: Preview of the Worldwide Chinese Domestic Databases Market Report (Base Year 2025)
As senior strategic advisors and the lead industry analysts at PW Consulting, we present a high-level preview of our newest market intelligence product: the Worldwide Chinese Domestic Databases Market report. This briefing outlines why the report will be essential for enterprise and public-sector decision-makers shaping database, cloud, and data-governance investments in 2026. It highlights macro market dynamics, competitive positioning, regulatory drivers and the practical, execution-oriented content clients will find in the full study—while intentionally withholding the granular segment tables and proprietary model outputs that are available only in the full report.
Worldwide BBQ Wood Pellets Market
Why this market matters for 2026 strategy
The domestic Chinese database ecosystem has moved well beyond niche substitution to become a strategic pillar for organizations operating in or with China. Underpinning that shift is a period of sustained growth: since 2020 the market has expanded markedly to reach a base-year size of USD 3.8 billion (revenues reported in Million USD for 2025), and our forecast horizon (2026–2032) projects continued rapid expansion at a compound annual growth rate (CAGR) of 18.5%. By 2032 the market is expected to be an order of magnitude larger than five years prior, reflecting accelerated cloud adoption, large-scale digital transformation in regulated sectors, and targeted public policy incentives.
Worldwide Managed Content as a Service (MCaaS) Market
For boards, CIOs, and procurement leaders, this combination of scale, growth velocity and policy-driven adoption creates both opportunity and complexity. The questions that will dominate boardroom agendas in 2026 are operational rather than academic: Which database architectures minimize compliance and migration risk? How to select vendors that balance cloud maturity, performance and sovereign-compliance coverage? How to re-evaluate TCO when power subsidies, localized supply chains, and chips policy materially change infrastructure economics? Our report is structured to answer those questions with the level of rigour required for decisive action.
Anti-Termite Treatments Market
Key macro drivers shaping vendor and buyer choices
-
Regulatory acceleration: Amendments to national cybersecurity and data-governance laws effective in early 2026 have tightened data sovereignty and cross-border transfer controls. Organizations that handle core or important data now face stricter localization, assessment and approval requirements—shaping sourcing decisions, contractual terms and cloud architecture choices.
-
Xinchuang & procurement momentum: National initiatives to replace foreign systems in government, SOEs and critical industries have matured from policy to procurement. Public-sector and regulated buyers are implementing replacement pathways that materially influence market demand and vendor roadmaps.
-
Infrastructure economics: Local incentives—such as electricity subsidies for data centers that adopt domestic chips—and the rapid expansion of national data-center capacity (over several million standard rack units by late‑2025) are altering TCO models for on-premise and cloud deployments. These shifts mean that buyers must re-run TCO with localized cost inputs rather than relying on global benchmarks alone.
-
Technology convergence: Domestic vendors are increasingly delivering cloud-native distributed databases, NewSQL, and AI-native capabilities that blur traditional lines between transactional and analytical workloads. This trend increases the opportunity for consolidation, but also raises migration complexity for legacy systems.
What the competitive landscape looks like
The market is moderately concentrated: our analysis shows the three largest providers account for a substantial portion of the market and the top five capture a clear majority, underscoring both incumbent strength and the presence of a vibrant mid-tier of specialized vendors. This concentration has practical implications for procurement risk, ecosystem lock-in, and negotiation dynamics.
-
Leading hyperscalers and cloud-native challengers: Major cloud providers have invested heavily in in-house distributed databases and cloud-native offerings. These solutions emphasize operational automation, scale and cloud integration—making them attractive for new cloud-first projects and for large transactional workloads that require high availability and benchmark performance.
-
Open-source and NewSQL innovators: Several vendors combine open-source community traction with enterprise-grade extensions, offering hybrid transactional and analytical processing capabilities that appeal to firms pursuing consolidation of analytic and OLTP platforms.
-
Specialized and regulated-use suppliers: A number of vendors focus on financial-grade transactionality, government localization and compliant deployment patterns. Their roadmaps prioritize robust security features, certification readiness and performance under high compliance constraints.
Notable vendor developments in recent quarters demonstrate the market’s rapid product evolution: a leading distributed database open-sourced an AI-native hybrid-search database late in 2025; several cloud vendors achieved benchmark performance leadership; and continuous product releases through early 2026 focused on operational tooling, observability and primary/standby architecture enhancements. These moves reflect a race to combine performance, AI-ready capabilities and enterprise-grade manageability.
Strategic implications for enterprise and public-sector buyers in 2026
-
Reassess migration roadmaps with policy as a first-order constraint. Technical feasibility must now be evaluated together with regulatory approval timelines, security assessment requirements and potential contractual constraints on cross-border data flows.
-
Adopt modular architectures for risk mitigation. Blended deployment strategies—mixing cloud-native, managed services, and controlled on-premise footprints—allow organizations to preserve agility while meeting localization and continuity requirements.
-
Quantify true TCO with localized inputs. Buyers should model scenarios that include regional power economics, potential subsidies, and chip availability constraints; these factors can materially alter the calculus between on-premise and cloud choices.
-
Prioritize vendor maturity in operations and observability. As databases scale into mission-critical systems, the ability to operate, monitor and recover at scale becomes a key selection criterion—sometimes outweighing raw benchmark performance.
-
Embed compliance workflows into procurement and contracts. Security assessments, data export controls, and certification roadmaps must be codified into vendor SLAs and migration contracts up front.
What the PW Consulting report delivers (high-level)
Designed for practitioners who must act in 2026, the full report combines rigorous market modelling with execution-focused tools. Deliverables include:
-
Market sizing and trend analysis (historical 2020–2025, base year 2025, and forward projections 2026–2032) with scenario modelling and sensitivity analysis to inform multiyear budgets and capital plans.
-
Vendor benchmark profiles that synthesize architecture, deployment maturity, compliance posture, performance claims and go-to-market strengths—accompanied by an ecosystem map of partnerships, certified systems integrators and managed-service operators.
-
Operational playbooks for migration and coexistence—including migration matrices, cutover risk frameworks, rollback planning and runbook templates for hybrid transactional/analytical consolidation.
-
Procurement and contracting templates aligned with data-security assessment workflows and localization requirements, enabling procurement teams to accelerate compliant vendor selection.
-
TCO and ROI models with configurable inputs for power subsidies, local labor rates, and chip availability scenarios—supporting finance and IT trade-off conversations.
-
Scenario-based risk assessments covering supply-chain constraints, regulatory shifts and escalation pathways that boards and risk committees should monitor closely.
These deliverables are supported by primary interviews, vendor disclosures, benchmark data and policy analysis. The report balances strategic orientation with tactical deliverables that technical and procurement teams can put to immediate use.
How organizations should use this intelligence in 2026
-
Short term (0–12 months): Use the report to define compliant migration paths for projects in flight, validate vendor performance claims against third-party benchmarks, and lock in contractual protections for cross-border data operations.
-
Medium term (12–24 months): Recalibrate platform roadmaps to exploit cloud-native efficiencies while hedging with on-premise or co‑located deployments for regulated data. Update RFPs and vendor scorecards with the report’s operational metrics and procurement templates.
-
Long term (24+ months): Incorporate the report’s scenario-led forecasts into multi-year capital planning, talent development (DBA and SRE capability building) and partner selection strategies—anticipating consolidation and continued product evolution across the ecosystem.
About market concentration and risk
Market concentration metrics indicate that a few large providers account for a significant share of revenues, while a competitive mid‑tier supplies specialized and regulated solutions. For buyers, concentration implies both negotiating leverage and systemic vendor risk—making diversification and contractual protections strategic necessities. For vendors, the path to scale requires not only superior engineering but also compliance certifications, ecosystem partnerships and demonstrable operational maturity.
Next steps and where to find the full study
This briefing has been structured to provide actionable strategic insight while preserving the proprietary segment tables, vendor scoring matrices and downloadable TCO models that further enable decision-making. PW Consulting’s full Worldwide Chinese Domestic Databases Market report (base year 2025, historical 2020–2025, forecast 2026–2032) contains the granular breakdowns by deployment mode, database model and industry vertical, plus the full vendor benchmarking dataset and executable playbooks.
For executive briefings, bespoke workshops to apply the models to your environment, or access to the full report and supporting tools, please visit the PW Consulting report page or contact our strategy team to schedule a briefing. The full report is the only place to obtain the underlying tables, vendor scorecards and the downloadable scenario models referenced here.
For detailed analysis of this topic, please visit the official page: Worldwide Chinese Domestic Databases Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecasts Worldwide Reformer Unit Market to Expand at 6.95% CAGR During 2026–2032
By pmarketresearch, 2026-08-12
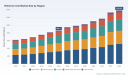
Worldwide Reformer Unit Market 2026 — Strategic Imperatives for Executives and Investors
As energy-transition timelines accelerate and industrial decarbonization becomes a boardroom priority, PW Consulting’s latest Worldwide Reformer Unit Market report surfaces as a practical decision-support instrument for 2026. Built on a 2020–2025 historical foundation and a 2026–2032 forecast horizon, the study quantifies a market that reached USD 864.5 Million in 2025 and—assuming current trajectories—expands at a 6.95% compound annual growth rate to approach USD 1,383.65 Million by 2032. The analysis blends quantitative rigor with executable guidance, enabling commercial leaders to align project pipelines, procurement strategies, and technology choices with near-term regulatory and cost pressures while preserving optionality for longer-term low‑carbon pathways.
Embryo Holding Medium Market
What the report delivers — practical, actionable intelligence
-
Consolidated market sizing and trend trajectories (base year 2025; historical window 2020–2025; forecast 2026–2032) with scenario-run sensitivities that stress-test demand under different carbon-pricing and technology-adoption assumptions.
Worldwide Commercial Collection Service Market -
Technology roadmaps and retrofit matrices for steam methane reformers (SMR), catalytic reformers, and autothermal reformers (ATR), including electricity‑integration readiness, heat‑integration opportunities, and CCS compatibility checklists.
Worldwide Portable Electric Scooter Market -
Vendor benchmarking and procurement playbooks covering licensing, EPC selection criteria, modular vs. stick-built trade-offs, and long‑lead component procurement timing to manage CAPEX and schedule risk.
-
Operational levers for reducing total cost of ownership—catalyst lifing strategies, tube metallurgy choices, predictive maintenance KPIs, and turnaround optimization—backed by component-life modeling and supplier warranties analysis.
-
Policy, regulatory and market stress tests mapping—how energy efficiency mandates, carbon pricing, and local content requirements alter project IRR, payback, and preferred technology pathways.
-
Case studies and templated action plans for hydrogen, ammonia, methanol and refinery-integrated applications that translate market dynamics into executable steps for 12–36 month horizons.
Why the report matters to 2026 corporate strategy
Three structural forces will shape reformer decisions in 2026: tightening climate policy, capital discipline under volatile commodity cycles, and the accelerating hydrogen economy. Regulatory attention and carbon-pricing mechanisms are increasing the economic penalty for unabated CO2 from conventional fuel-fired reformers, which is catalyzing adoption of electrification and CCS-ready configurations. Academic and pilot data show electrified steam reformers (e‑REFORMER) can materially lower direct flue-gas CO2 emissions—reported reductions of up to 91.56% in select ammonia plant retrofit scenarios—while improving thermal efficiency metrics (reported improvements from ~85.6% to ~88.9% in those cases). Translating those technical gains into bankable projects requires careful alignment of technology risk, offtake structures, and available green‑power contracts.
Concurrently, raw-material cycles matter. Global steel prices were at or near the bottom of the current price cycle in early 2026, with subdued recovery expected through the year and a more meaningful upturn projected from 2027. For executives that manage long‑lead items (reformer tubes, pressure vessels, and critical cast components), this implies an asymmetric procurement opportunity window in 2026 to lock favorable pricing and delivery dates—while balancing inventory, depreciation and cash constraints.
Competitive landscape — what to watch
The reformer ecosystem blends full‑stack licensors and EPCs with specialist equipment, catalyst, and metallurgy suppliers. Market concentration is meaningful but not prohibitive: our concentration metrics indicate the top three players hold a substantial share while the top five approach a clear majority—signalling an environment where established licensors and global EPC houses shape technology roadmaps, yet specialist suppliers can capture high-margin niches.
-
Linde Engineering (Selas‑Linde) — A global leader in steam reformer supply with a long installed base and modular HYDROPRIME® solutions designed for on‑site and low‑emission projects. Its experience in varied feedstocks and modular configurations positions it as a preferred partner for rapid decarbonization projects and small on‑site hydrogen solutions.
-
Honeywell UOP & Axens — Both maintain strong positions on catalytic reforming technology and licensing. Their portfolios and catalyst ecosystems make them pivotal to refiners optimizing gasoline quality and aromatics production where catalytic routes remain core.
-
KBR & Technip Energies — These engineering and technology providers drive major SMR and ATR projects, blending process licensing with EPC delivery. Their involvement is often decisive for large‑scale hydrogen and syngas projects where integration and project execution risk dominate.
-
Johnson Matthey — A critical supplier of reforming catalysts whose choices materially influence per‑unit production economics and catalyst exchange cycles, especially in ammonia and methanol contexts.
-
MetalTek International & Kubota Corporation — Specialist manufacturers of reformer tubes and high‑temperature components. Their materials science and casting practices directly affect tube life, maintenance cadence, and turnaround cost; improvements here unlock multi‑year OPEX savings.
-
Wood plc & Larsen & Toubro — Engineering, consulting and construction firms that provide integration, EPC and regional execution expertise; essential partners for translating licensor designs into constructible, financeable projects.
Recent market movements underscore these dynamics: licensors and equipment suppliers reported record on‑site hydrogen project wins and long‑term industrial gas agreements in 2025, and research presentations in late 2025 highlighted electrification of steam reformers as a credible decarbonization pathway. Together, these signals point to accelerating activity at the intersection of low‑carbon hydrogen and ammonia project pipelines.
Commercial implications — recommended near‑term moves for 2026
-
Prioritize modularity for early‑stage decarbonization projects. Modular and skid‑mounted reformers can de‑risk first‑mover projects, compress timelines and simplify contractual interfaces—especially for green ammonia and on‑site hydrogen applications.
-
Lock critical long‑lead items in 2026 where price momentum favors buyers, but avoid overcapitalizing inventory. Balance vendor financing and staged delivery to preserve flexibility for electrification or CCS retrofits.
-
Seek catalyst and metallurgy partnerships that include outcomes‑based guarantees (e.g., tube life, catalyst cycle lengths). Small gains in operational life translate into disproportionate OPEX reductions across a multi‑year asset horizon.
-
Design new projects with CCS and electrification compatibility as default options. Even if not deployed immediately, specifying space, tie‑ins and interconnection capacity early reduces retrofit premium and stranded‑asset risk.
-
Adopt a two‑track procurement strategy: engage top global licensors for core process risk control while qualifying select specialist suppliers to extract efficiency and lifecycle gains.
-
Run rapid scenario economics across carbon‑price sensitivities and fuel‑cost volatility—embed these outputs into investment committees to rationalize go/no‑go timing and offtake pricing.
Methodology & data integrity
The report’s base year is 2025, with historical coverage from 2020–2025 and a forecast window stretching 2026–2032. Our headline CAGR for the forecast period is 6.95%. Estimates leverage primary interviews with licensors, EPC contractors, OEMs and end‑users; secondary sources including industry publications, trade data, patent filings and tender activity; and bottom‑up modeling of capex, feedstock and operating assumptions. Market concentration metrics (top‑3 and top‑5 shares) are included as governance indicators for competitive risk assessment. For confidentiality and strategic positioning reasons this executive summary purposefully omits granular segment share tables; the full dataset, segmentation matrices and supplier scorecards are available in the complete report.
How to use this analysis in 2026 planning cycles
-
Board level: Use our scenarios to stress-test portfolio exposures to carbon pricing and to define threshold conditions for brown‑to‑green capex redirection.
-
Project teams: Apply the retrofit matrices and vendor scorecards during FEED to reduce scope creep and to secure performance guarantees that align with low‑carbon ambitions.
-
Procurement: Combine short‑term tactical buys for long‑lead items with strategic supplier partnerships for catalysts and metallurgy to reduce TCO.
-
Investors & lenders: Use the report’s risk‑adjusted forecasts to calibrate financing terms and to set technical milestones tied to disbursement.
Conclusion & next steps
PW Consulting’s Worldwide Reformer Unit Market report translates a shifting regulatory and cost environment into a pragmatic playbook for 2026. The sector is expanding—with a clear trajectory reflected in the reported USD 864.5 Million market size for 2025 and a near‑7% CAGR through 2032—yet the pathway to sustainable, bankable projects will be decided by a few critical choices: timing of procurement, modularization vs. bespoke engineering, catalyst and metallurgy strategies, and the degree to which CCS and electrification are embedded from day one.
To review the full segmentation breakdowns, supplier scorecards, and downloadable financial models, access the complete report and appendices on the PW Consulting research portal. The summary above is intentionally selective—designed to demonstrate our analytic depth and to invite strategic engagement; the full intelligence package contains the granular data and templates necessary to operationalize the recommendations for immediate 2026 planning cycles.
For detailed analysis of this topic, please visit the official page: Worldwide Reformer Unit Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Smart Ticketing Market to More Than Double — from USD 18.25B in 2025 to USD 41.24B by 2032 at a 12.35% CAGR
By pmarketresearch, 2026-08-12
Worldwide Smart Ticketing Market — Strategic Briefing for 2026 Decision-Makers
PW Consulting’s latest market study, Worldwide Smart Ticketing Market (base year 2025), provides a rigorous, execution-focused view of an industry undergoing rapid platformization and regulatory harmonization. The global market reached an estimated USD 18,250 Million in 2025 and — under our core forecast — is projected to grow at a compound annual growth rate (CAGR) of 12.35% through the 2026–2032 horizon. By 2032 the sector is expected to materially expand from today’s scale, driven by accelerating adoption of account-based ticketing, wallet-native transit experiences, and contactless EMV acceptance across major networks.
Worldwide Mechanical Booster Pumps Market
Why this report matters for 2026 strategy
- Timing and regulation are converging. National and supranational mandates for interoperability, together with updated payment-security requirements, create both compliance obligations and competitive opportunity windows that will crystallize in 2026.
- Platform decisions have long tails. Choices made in 2026 — around account-based architecture, credentialing standards, and wallet integrations — will define cost of ownership and competitive positioning for a decade.
- Capital allocation must be evidence-based. With the market expanding briskly, operators and investors need scenario-tested capex/opex models and vendor-selection frameworks to prioritize spend where it accelerates ridership, revenue, or operating efficiency.
High-level market dynamics (what is driving growth)
- Technical convergence: Mobile-first ticketing, NFC contactless credentials, QR-based validation, and bank-card acceptance are moving toward unified customer journeys. The interplay between credential vendors, semiconductor suppliers and software platforms is reshaping procurement requirements.
- Regulatory catalysts: Recent mandates for open standards and cross-border interoperability are shortening procurement cycles for compliant systems and increasing the premium for vendors that can prove standards alignment and data portability. Separately, payment security rules (including PCI DSS v4.0) are raising the bar for systems that process cardholder data.
- Deployment economics: Infrastructure costs vary by technology and deployment model; for example, urban NFC reader installations typically present a defined per-unit investment that operators must weigh against the benefits of reduced friction and the operational simplicity of account-based backends.
- Consolidation and specialization: Market concentration metrics indicate a sector that is neither monocultural nor fragmented: leading platforms capture meaningful share, but specialists remain crucial for integration, credential manufacture, and IC supply.
What PW Consulting’s report delivers — operationally usable content
This study is designed for executives who must convert insight into action in 2026. The report blends granular scenario modeling with practical deliverables that procurement teams, CIOs, and strategy groups can use immediately:
Worldwide Enterprise Mobility Management Software Market
- Top-down and bottom-up market sizing and a validateable forecast model (2026–2032) that supports stress-testing under alternative adoption, price and regulatory scenarios.
- Decision playbooks for choosing between account-based and card-centric architectures, including a vendor-agnostic checklist to assess interoperability, scalability, and data ownership.
- Total Cost of Ownership (TCO) templates that combine capital, operating, and lifecycle upgrade costs across typical rollout phasing — with sensitivity levers you can plug into your own financial models.
- Procurement-ready artifacts (RFP language snippets, SLA clauses, and scoring matrices) that embed standards compliance, cyber controls, and migration milestones so clients can shorten bid cycles and reduce legal friction.
- Implementation playbooks and risk registers for real-world rollouts (pilot design, fare migration, customer communication, validator retrofits), including escalation paths for payment incidents and interoperability disputes.
- Regulatory compliance roadmap that maps major mandates and payment-security requirements to concrete program milestones for 2026 implementation windows.
- Vendor shortlists and assessment frameworks built from public deployments, product capability, partner ecosystems and proven migration track records — intended to accelerate vendor selection without sacrificing rigor.
Competitive landscape — interpreting the players and recent moves
The marketplace is driven by a combination of platform providers, credential and hardware suppliers, and systems integrators. PW Consulting’s competitive diagnostic highlights capability clusters, recent strategic moves through 2025–2026, and implications for procurement and partnership strategies.
Worldwide Oil & Gas Processing Seals Market
- Platform and account-based specialists. Firms such as Masabi and Cubic have been leading customer-facing innovations: Masabi’s integration with wallet providers to enable tap-to-ride on consumer devices and Cubic’s evolution of multimodal platforms underscore a push toward seamless, app-native experiences. Expect wallet integrations and native platform capabilities to be differentiators in 2026 procurements.
- Mobility-as-a-Service aggregators. Mobility app providers — exemplified by Moovit — are translating app adoption into broader ticketing footprints by embedding account-based ticketing across city networks, expanding reach and lowering friction for operators that partner rather than build.
- Credential and semiconductor ecosystem. Suppliers like HID Global and NXP Semiconductors remain essential to the fabric of mass deployments: credential issuance, secure element design and card IC availability determine the feasibility and cost of large-scale rollouts. Their roadmaps influence migration timelines for legacy card programs.
- Systems integrators and integrative platform vendors. Thales and other major integrators provide end-to-end deployments that include contactless EMV and bank-card acceptance; these capabilities are increasingly important as networks look to simplify payment acceptance and reduce dependence on closed-loop credentialing.
- Regional and specialist operators. Established regional players and fare-collection specialists continue to support complex local requirements and airport or stadium deployments where integration complexity is high.
Recent strategic developments — such as wallet integrations, account-based expansion in new municipalities, and upgraded contactless EMV deployments — are not isolated innovations. They reflect three parallel trends: customer-experience centralization, payments-layer disruption, and standards-driven interoperability. Each trend has procurement and architecture consequences that our assessment explores in depth.
Strategic recommendations for decision-makers in 2026
- Prioritize pilot-to-scale pathways. Run bounded account-based pilots that validate back-office settlement, fare-capping rules, and revenue assurance before committing to network-wide rollouts.
- Embed interoperability in contracts. Require open-standards conformance, data portability clauses and staged exit provisions to reduce lock-in and enforce competitive maintenance of core interfaces.
- Make security a sourcing criterion. Treat PCI DSS v4.0 readiness and credential lifecycle management as pass/fail items during shortlisting; remediation costs for non-compliant systems are material and time-sensitive.
- Budget for hybrid infrastructure. Expect to operate mixed fleets of validators and credentials during migration; model capex and operating impacts across staged decommissions. Infrastructure unit costs should be quantified and stress-tested against adoption speed.
- Negotiate ecosystem partnerships. Whether working with wallet providers, semiconductor vendors, or MaaS aggregators, secure partnership terms that include roadmap alignment and joint go-to-market commitments.
- Adopt modular procurement approaches. Break projects into composable phases (core account engine, validation layer, customer channels) to preserve optionality and accelerate value capture.
How to use the full report
PW Consulting’s study is structured to support short-cycle executive decisions and detailed technical procurement workstreams. Use the report to:
- Calibrate strategic plans with our scenario-tested market forecast and elasticity assumptions;
- Extract RFP language and TCO templates directly into procurement processes;
- Shortlist vendors using our validated capability matrices and recent-deal tracking; and
- Operationalize migration pathways with the included playbooks and risk mitigations.
For teams preparing capital plans and procurement timelines for 2026, the report provides both the analytical backbone and the practical toolset necessary to convert market opportunity into measurable outcomes. To access the full datasets, vendor matrices, and the interactive forecast model — including the granular segmentation and scenario tables that support the executive summaries above — please visit the PW Consulting report page for Worldwide Smart Ticketing Market.
PW Consulting — Strategic intelligence for transit, payment and mobility leaders.
For detailed analysis of this topic, please visit the official page: Worldwide Smart Ticketing Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecasts 5.4% CAGR for Worldwide Subsea Well Access and BOP System Market Through 2032
By pmarketresearch, 2026-08-12
Worldwide Subsea Well Access and BOP System Market: Strategic Imperatives for 2026 Decision-Makers
PW Consulting’s latest market study on Worldwide Subsea Well Access and Blowout Preventer (BOP) Systems delivers a forward-looking playbook tailored for executives, investors and operational leaders preparing for the 2026 planning cycle. Drawing on a five-year historical lens (2020–2025) and a seven-year forecast (2026–2032), the study synthesizes market sizing, competitive dynamics, regulatory inflection points and technology trajectories into a decision-ready framework. The headline: the global market—measured in USD millions—stands at an established base in 2025 and is projected to grow at a compound annual growth rate (CAGR) of 5.4% through 2032, reaching roughly the mid‑single‑billion mark by the end of the forecast horizon.
Worldwide FR PP Compounds Market
Why this report matters for 2026
-
Timing: As operators and OEMs set capital allocation, supply‑chain commitments and technology roadmaps for 2026, this study isolates the structural drivers that will determine where returns accrue vs. where investments are likely to underperform.
Gas Station Canopy Light Market -
Actionability: Beyond topline forecasts, the research delivers scenario‑based implications for procurement strategy, product development priorities, and commercial contracting—critical inputs for near‑term multi‑year budgets.
Worldwide Haarlem Oil Market -
Risk‑adjusted insights: The report overlays regulatory and materials risk vectors (e.g., API and NACE compliance, alloy supply pressures) onto demand forecasts, allowing decision-makers to stress‑test projects against compliance and sourcing shocks.
Market outlook — what the numbers mean
Our analysis shows a steady recovery and expansion trajectory following the recent market trough and rebound. With the market growing at a 5.4% CAGR across the forecast period, the sector’s expansion is driven by persistent deepwater/ultra‑deepwater activity, a renewed push into frontier basins, and a parallel rise in intervention and decommissioning operations that require advanced well access solutions. For 2026 planning, the implication is clear: the addressable market is expanding sufficiently to justify both selective greenfield investments and capability upgrades for established suppliers, while creating differentiated opportunities for specialist service providers.
Importantly, market concentration metrics reveal a moderately consolidated landscape: the top three suppliers control just over half of the market, while the top five account for more than three quarters. That structural concentration underscores two competing strategic pathways for investors and mid‑tier vendors—scale-driven consolidation or focused differentiation via technology and service specialization.
Key industry dynamics shaping 2026 decisions
-
Regulatory and technical thresholds: Compliance with API standards for BOPs and intervention systems, alongside NACE requirements for sour service materials, is non‑negotiable. The push toward higher pressure ratings—examples of industry development work toward 20,000 psi class equipment—raises both certification and materials complexity, lengthening lead times and raising unit engineering costs.
-
Material and supply‑chain pressures: Production of high‑strength, corrosion‑resistant alloys is a gating item for BOP manufacturing. OEMs that secure reliable alloy supply and verticalize quality control will be advantaged in win rates and delivery performance.
-
Technology convergence: Intervention solutions—riserless, workover and integrated tree‑plus‑well access systems—are converging toward modular, serviceable architectures that reduce vessel dependency and lower operational risk. Novel valve designs that consolidate functions are already in market, and operators will prioritize interventions that demonstrably lower total intervention cost and failure risk.
-
Service & life‑of‑field economics: Growing activity in intervention, workover and abandonment creates recurring service revenues for specialized intervention providers. For oil companies, the economics of extending field life via targeted interventions increasingly outruns the spend required for new wells in many offshore basins.
Competitive landscape — who matters and why
The market is led by established global oilfield service and equipment firms with broad subsea portfolios. Our report includes a forensic competitive benchmarking of OEMs and service providers, examining capabilities across manufacturing scale, R&D intensity, service footprint, and commercial model flexibility.
-
Baker Hughes Company (Houston): Strong in IWOCS (Installation and Workover Control Systems) and subsea pressure control. Their advantage is integrated systems engineering for deepwater programs and a global service infrastructure that reduces mobilization risk.
-
SLB (Schlumberger Limited) (Houston): Offers end‑to‑end subsea pressure control and downhole intervention tools. Recent large‑scale completions contracts in ultra‑deepwater illustrate SLB’s ability to bundle technology with long‑term field support; its scale supports advanced interval control deployment for complex reservoirs.
-
Aker Solutions (Fornebu): Differentiates on integrated subsea production systems and combined well access/workover packages—appealing to operators seeking single‑vendor subsea delivery to simplify project risk.
-
TechnipFMC (Newcastle/Houston): Competes on integrated tree and intervention systems, with a strong project execution track record on large offshore developments.
-
NOV Inc. (Houston): A key equipment manufacturer focused on high‑pressure ram BOPs and subsea drilling technologies—strength lies in mechanical reliability and manufacturing throughput.
-
Halliburton, Weatherford, Dril‑Quip, Oceaneering, Expro, Proserv, Helix : These players populate niches across intervention services, valve technologies, and intervention vessels. Several have strengthened portfolios through targeted product launches or strategic agreements.
Recent market moves validate the tactical directions we recommend. A new single high‑debris shear‑and‑seal ball valve launched in early 2026 consolidates functionality to reduce complexity and failure exposure—an example of product innovation that can materially reduce intervention risk. Major contract awards for ultra‑deepwater completions and exclusive supply agreements between subsystem suppliers and OneSubsea highlight the industry’s tilt toward long‑term, integrated supply relationships.
What the PW Consulting report contains — practical deliverables
The study is purpose‑built for executives who must make near‑term commitments with multi‑year ramifications. Deliverables include:
-
Top‑down and bottom‑up market models with sensitivity analyses and three scenario paths (base, upside with accelerated deepwater activity, and downside with commodity stress).
-
Vendor scorecards assessing performance across manufacturing capacity, product certification readiness, aftermarket service coverage, and technology roadmaps.
-
Procurement playbooks and contract templates that address supplier lead‑time guarantees, material substitution clauses for alloy shortages, and regulatory compliance milestones tied to payments.
-
Capex vs. opex decision matrices for operators comparing full asset replacement, life‑extension interventions, and shared‑asset service models.
-
Risk registers and mitigation playbooks covering regulatory certification timelines, supply‑chain single‑point risks, and logistics for frontier basin operations.
-
Executive dashboards: succinct KPIs for portfolio managers (delivery performance, spare parts fill rate, intervention success rates, and warranty exposure).
Strategic recommendations for 2026 planning
-
Prioritize certification and materials readiness: If your 2026 program targets high‑pressure or sour service environments, fast‑track API and NACE‑aligned qualification paths and secure alloy supply commitments now to avoid 12–24 month delivery slippage.
-
Adjust commercial models toward outcome orientation: Operators should consider outcome‑based contracts with uptime and intervention success SLAs. Suppliers should price modular, serviceable systems that lower life‑cycle cost and increase aftermarket revenue.
-
Invest selectively in 20,000 psi capability: The development of extreme‑pressure equipment opens high‑margin frontier opportunities—but requires concentrated R&D and testing investment. Evaluate partnerships or acquisition of niche tech providers versus greenfield development.
-
Strengthen intervention options: Riserless and lower‑vessel‑dependence intervention technologies are becoming differentiators for operators seeking flexible well intervention windows and lower mobilization costs.
-
Prepare for consolidation or specialization: Given the market concentration dynamics, mid‑tier players should either pursue scale through M&A or double down on specialized product and service niches where technical differentiation yields premium margins.
Risk checklist for boardrooms
-
Certification timelines: Map API/NACE qualification milestones against project gating schedules and trigger contract remedies if suppliers miss key dates.
-
Alloy availability: Validate multi‑tier sourcing and consider inventory hedging for critical alloy inputs.
-
Regulatory shifts: Monitor jurisdictional changes that can alter intervention requirements or component approvals; build scenario triggers into project governance.
-
Technological obsolescence: Include upgrade pathways and retrofit clauses in long‑term supplier agreements to protect against rapid obsolescence of key subsea components.
Conclusion — how to use this intelligence in 2026
For 2026, executives must balance the dual imperatives of capability readiness (materials, certification, engineering) and commercial agility (contract design, service models and partnerships). The subsea well access and BOP landscape is expanding at a steady mid‑single‑digit CAGR and remains concentrated among a few large suppliers, creating windows for both scale players and technically differentiated specialists. PW Consulting’s study provides the operational templates, supplier evaluation tools, and scenario analyses you need to translate market growth into durable returns while managing certification, materials and execution risk.
To access the full dataset, vendor scorecards and the actionable procurement playbook that underpin these conclusions, consult the complete report on our website—equipped with downloadable executive dashboards and customizable scenario models to support your 2026 planning cycle.
For detailed analysis of this topic, please visit the official page: Worldwide Subsea Well Access And BOP System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Acute Ischemic Stroke Market Projected to Grow at a 7.82% CAGR Through 2032
By pmarketresearch, 2026-08-12
Worldwide Acute Ischemic Stroke Market — Strategic Preview for 2026 Decision-Makers
PW Consulting’s latest market intelligence brief, "Worldwide Acute Ischemic Stroke Market (Base Year 2025)", synthesizes clinical, commercial and policy signals into an actionable view that materially changes how medtech, pharmaceutical and health systems should plan for 2026. Our bottom-up model projects a robust market expansion beginning in 2026, driven by updated clinical guidance, improving reimbursement, and accelerating device innovation. Between the 2025 base year and the end of our forecast window, the market expands at a compound annual growth rate of 7.82%, delivering significant value creation opportunities across product classes and geographies.
Worldwide Excavator Multi-Processors Market
Why this report matters for 2026 strategy
Executives preparing 2026 budgets and strategic plans need forward-leaning intelligence that translates clinical momentum into commercial choices. The clinical eligibility window expansion and rising AIS incidence are changing patient volumes and the addressable opportunity for thrombectomy systems, aspiration platforms, and adjunctive therapies. At the same time, meaningful reimbursement actions and regulatory acceleration are lowering commercialization barriers for novel entrants while altering pricing dynamics for incumbents.
Smart Wearable Coin Battery Market
-
Investment prioritization: The report turns macro trends into capital allocation guidance — where to scale clinical evidence generation, when to accelerate regulatory filings, and which partnerships will shorten time-to-revenue in 2026.
Worldwide Legal Research Software Market -
Go-to-market calibration: We map evolving care pathways to channel economics, helping commercial leaders optimize hospital contracting, specialty clinic partnerships, and ambulatory surgical center penetration for the coming growth window.
-
M&A and portfolio plays: Our scenario-based models reveal where tuck-ins and bolt-ons create asymmetric upside versus where greenfield R&D is required — an essential input for 2026 deal calendars.
Market trajectory and the drivers that matter
PW Consulting’s analysis integrates historical performance (2020–2025) with granular assumptions to produce a 2026–2032 forecast that reflects new clinical guidelines and policy shifts. The base-year market in 2025 stands at USD 10,750 Million (revenue unit: Million, USD). Under current assumptions the market advances strongly after 2026 and reaches a materially larger size by 2032, reflecting compounded increases in patient eligibility, device penetration, and procedural intensity.
Key demand-side drivers:
-
Clinical guideline evolution: The AHA/ASA 2024 expansion of thrombectomy eligibility to selected patients up to 24 hours fundamentally expands the population that will be triaged for endovascular intervention. This is not theoretical — it changes hospital workflows, imaging investment decisions, and the cadence of interventional cases in 2026.
-
Demographics and incidence: Age-driven prevalence trends project substantial increases in AIS cases in major markets; PW’s synthesis of epidemiologic forecasts suggests clinically material growth by 2030 and beyond.
-
Reimbursement shifts: CMS’s FY2026 update to NTAP creates a step-function change in device economics for eligible thrombectomy systems. That policy alters negotiation dynamics between providers and manufacturers and shortens payback thresholds for hospital capital investment.
Supply-side forces shaping 2026 strategies:
-
Regulatory acceleration: A rise in Breakthrough Device Designations and other expedited pathways has compressed time-to-market for several novel thrombectomy systems, altering competitive timing and the value of first-mover clinical data.
-
Innovation in device platforms: New-generation stent retrievers, aspiration technologies, and integrated access platforms are increasing procedural efficiency and shifting preference patterns among neurointerventionalists. Recent product launches and clearances in late 2024–2025 validate this trend.
-
Supply-chain risk and cost pressure: Tariff adjustments on imported components have introduced new cost considerations, especially for manufacturers relying on cross-border neurovascular component sourcing. Procurement teams should build sensitivity to input-cost volatility into 2026 pricing scenarios.
Competitive landscape — what incumbents and challengers signal for 2026
The AIS device market is innovation-intensive and clinically driven. PW’s competitive analysis highlights four strategic archetypes operating in parallel: category leaders scaling clinical evidence and channel reach; fast-follow platform innovators optimizing procedural efficiency; niche players targeting differentiated access or adjunctive therapies; and new entrants leveraging regulatory fast-tracks.
-
Stryker Corporation — continues to reinforce its mechanical thrombectomy leadership through iterative product launches and expanded clinical applications. Recent innovations focused on complex aneurysm and flow-diversion adjuncts illustrate a dual strategy of protecting core thrombectomy share while growing adjacent neurovascular categories.
-
Medtronic plc — combines long-duration clinical evidence with aspiration and retriever platforms. Positive medium-term clinical data reported in 2025 strengthens adoption narratives and supports premium positioning in hospital procurement processes.
-
Johnson & Johnson (Cerenovus) — following regulatory approvals for next‑generation devices, the company is pursuing aggressive evidence generation and hospital-level integration, positioning to capture large-vessel occlusion cases where device performance and workflow integration matter most.
-
Penumbra, Inc. — with new regulatory clearances in 2025 for faster aspiration systems, Penumbra is executing on an aspiration-led differentiation that shortens procedure times and improves throughput, a compelling commercial message for cash-strapped stroke centers.
-
Balt USA, Terumo, MicroVention, Rapid Medical — these regional and niche specialists are executing targeted clinical programs, expanding geographic footprint and, in some cases, leveraging CE Mark or other approvals to accelerate European and APAC growth. Their focused product strategies create tactical threats to incumbents in price-sensitive or access-constrained settings.
Taken together, these moves indicate a market where product performance, procedure economics, and evidence generation will determine share shifts in 2026. Our analysis suggests that clinical endorsements and a few decisive regulatory clearances this year will disproportionately influence procurement cycles next year.
What the report contains — practical deliverables
PW Consulting’s report is designed for 2026 execution. It does not stop at high-level forecasts; it provides a toolkit to act immediately:
-
Proprietary forecast model (2026–2032) with scenario toggles for guideline adoption, reimbursement realization, and tariff impacts — enabling CFOs to run revenue and margin sensitivity analyses for planning cycles.
-
Clinical pathway maps that translate guideline changes into patient flows and procedure volumes by care setting, with tactical recommendations for training, imaging investments, and hub-and-spoke network design.
-
Commercial playbooks covering pricing levers, hospital contracting templates, and value-based propositions aligned with expected NTAP reimbursements and payer negotiation windows.
-
M&A screening and diligence checklists that prioritize targets by technological fit, geographic lift, and clinical evidence maturity — including shortlists derived from primary clinician and payer interviews.
-
Regulatory and reimbursement roadmaps per major market, including time-to-reimbursement estimates and policy-risk heatmaps to support 2026 launch sequencing.
To preserve competitive advantage for our clients, the report intentionally omits raw subsegment disclosures in public summaries; detailed regional, treatment-type and end-user breakdowns, as well as interactive dashboards and model inputs, are available to licensed purchasers.
How to use these insights in 2026 planning
-
Prioritize evidence investments that close the smallest clinical gaps with the biggest commercial returns. Our value-mapping engine quantifies ROI of incremental trial endpoints and registry participation relative to procurement timelines.
-
Lock in supplier diversification and tariff mitigation plans for any component exposure tied to vulnerable geographies. The model shows breakeven points for localized manufacturing or long-term supply agreements under tariff stress scenarios.
-
Align commercial rollouts with reimbursement timing. For manufacturers, synchronizing regulatory milestones with anticipated NTAP and payer coverage shifts materially shortens the sales cycle in 2026.
-
For health systems and hospital groups, the playbooks provide a clear framework for capacity expansion decisions: which centers to upgrade, when to centralize advanced care, and how to negotiate device-bundle pricing to protect margins as case volumes grow.
Methodology and editorial rigor
Our findings synthesize primary interviews with neurointerventionalists, hospital procurement leads, and payers; a proprietary device and procedure-volume model; regulatory and reimbursement tracking; and a thorough review of recent product launches and clinical studies. We triangulate public filings, regulatory databases and primary research to ensure our 2026 planning assumptions are grounded in observable market moves, including the notable product launches, clearances and study readouts in 2024–2025.
Next steps — where to get the full intelligence
This release is a deliberate preview: it demonstrates the analytic depth clients rely on while reserving granular subsegment and interactive model access for licensed report purchasers. If your 2026 plan depends on capturing value in the acute ischemic stroke ecosystem — whether as a manufacturer, investor, or health system — schedule a briefing with PW Consulting to obtain the full forecast model, bespoke scenario runs, and the commercial playbooks that operationalize these insights.
Contact PW Consulting to request an executive briefing and unlock the full dataset and dashboards that power fiscally responsible, clinically aligned decision-making for 2026.
For detailed analysis of this topic, please visit the official page: Worldwide Acute Ischemic Stroke Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Industrial Epoxy Glass Market to Expand from USD 2,842.6 Million in 2025 to USD 4,218.9 Million by 2032 at a 5.82% CAGR — FR‑4, Asia Pacific and Electrical & Electronics Lead Growth
By pmarketresearch, 2026-08-12
Worldwide Industrial Epoxy Glass Market — Strategic Briefing for 2026 Decision-Makers
PW Consulting’s latest market study on the Worldwide Industrial Epoxy Glass Market provides a focused, execution-oriented view designed specifically to support corporate planning and investment decisions in 2026. The industry is transitioning from steady recovery into differentiated growth: the overall market expands from a 2025 base of USD 2,842.6 Million into a structurally larger market in 2026 (projected USD 3,008.6 Million), with a compound annual growth rate (CAGR) of 5.82% through our 2026–2032 forecast window. This briefing highlights the practical implications of those trends for sourcing, product strategy, capacity planning, and M&A — while intentionally reserving detailed segment-level figures for the full report.
Worldwide Mobile Event Apps Market
What the report delivers — practical content for 2026 action plans
- Validated market sizing and top‑line forecasts (base year 2025; forecast period 2026–2032), with scenario stress‑testing to quantify upside and downside cases relevant to 2026 planning cycles.
- Demand‑driver analysis linking end‑market dynamics (electrical & electronics, aerospace & defense, automotive electronics, industrial machinery) to product-level requirements and margin pools.
- Upstream cost mapping and sensitivity models that show how epoxy resin price moves transmit to finished goods costs and gross margin under alternative sourcing and hedging strategies.
- Supply‑side diagnostic: capacity maps, utilization analysis, logistics choke points, and supplier scorecards for supplier consolidation or dual‑sourcing decisions.
- Competitive benchmarking and playbooks (pricing, certification, product differentiation, channel and service models) focused on near‑term execution and 12–24 month outcomes.
- M&A and partnership framework including target screening criteria, valuation multiples observed in recent transactions, and integration checklists for quick wins post‑close.
- Operational toolkits — Excel-ready models, supplier heatmaps, procurement negotiation scripts, and an executive dashboard for board‑level reporting.
Key macro and market dynamics that will shape 2026 choices
- Resilient top‑line growth but margin pressure points: the market’s mid‑single digit CAGR masks important upstream volatility — in 2026 epoxy resin price dynamics will remain a primary cost driver. Recent data points highlight regional price differentials (e.g., Northeast Asia epoxy resin quoted at approximately USD 2.62/kg in April 2026, and China pricing reported near USD 2,031/MT earlier in 2026). These swings materially affect unit economics for G‑10/FR‑4 producers and necessitate active procurement hedging or pass‑through mechanisms.
- Certification and compliance are baseline requirements: leading suppliers maintain UL 94 V‑0 flame retardancy and RoHS/REACH compliance as standard. For OEMs targeting regulated verticals (aerospace, defense, critical industrial applications), certification investments and traceability are non‑negotiable and materially affect supplier selection and time‑to‑market.
- Product innovation is bifurcating the value chain: new resin formulations and specialty prepregs (for example, next‑generation flame‑retardant clear epoxy prepregs introduced in 2026) are enabling premium product segments — particularly where visual aesthetics, flame performance and high‑reliability electrical properties converge. These niches command differentiated pricing and longer purchase cycles tied to qualification time.
- Capacity shifts and regional supply strategies: reported capacity expansions among large integrated producers signal continued consolidation of high‑volume supply, while many regional players focus on short lead-time and customized forms (rods, tubes, machined parts). The competitive footprint therefore supports both global scale players and nimble local specialists.
Competitive landscape — strategic positioning and implications
The sector shows a concentrated‑but‑fragmented structure: the top three suppliers account for roughly one‑third of market share, and the top five approach half the market — a profile that creates both competitive intensity and opportunities for mid‑market consolidation. Key competitors and the strategic implications for 2026 are summarized below.
Worldwide Creatine Citrate Market
- Ventec International Group (Taiwan) : Global leader in high‑performance copper clad laminates and prepregs. Strengths include deep technical capability in PCB substrates and a proven qualification pipeline for high‑reliability customers. For 2026, Ventec’s playbook centers on technology licensing, long‑cycle qualification wins in telecom and advanced PCB manufacturers, and selective capacity allocation to premium grades.
- Isola Group (United States) : Differentiated by broad copper‑clad laminate and prepreg portfolio, and strong relationships with demanding PCB OEMs. Isola’s positioning favors long‑term contractual relationships and co‑development; they are a logical partner for OEMs seeking integrated supply with design support services.
- Atlas Fibre, Franklin Fibre‑Lamitex, Current Inc., Iten Industries (United States) : These North American specialists offer depth in G‑10/FR‑4/G‑11 sheets, rods, tubes and machined components. Their strategic advantage is service responsiveness and MIL/NEMA compliance capabilities — attractive to defense and heavy industrial customers requiring short lead times and domestic sourcing.
- Hexcel Corporation & Park Aerospace (United States) : While better known for advanced composites in aerospace, these firms’ glass‑reinforced epoxy systems provide cross‑industry technology transfer — elevating performance expectations (e.g., thermal stability, weight optimization) and accelerating premium segment growth.
- SIDA (China JV group) & Hony Engineering Plastics (China) : Large‑scale manufacturers focused on high‑volume FR‑4 and related grades. Reported capacity expansions and catalog updates by these players increase competitive supply in both domestic and export markets. Their scale supports aggressive pricing tactics but also exposes them to upstream feedstock swings and regional policy shifts.
Five strategic playbooks for executives in 2026
- Insulate margins from resin volatility: establish blended sourcing, index‑linked contracts with suppliers, and a tactical inventory hedge program. Our sensitivity models quantify breakpoints where pass‑throughs become necessary versus when to absorb costs for strategic share retention.
- Prioritize qualification pipelines: invest selectively in certifying premium epoxy glass grades and flame‑retardant prepregs for high‑value end markets. Time‑to‑qualification will determine 2026 revenue capture in aerospace, defense and advanced electronics segments.
- Adopt a dual supply strategy: combine global scale partners for commodity volumes with regional specialists for rapid turnaround and custom fabrication. This hybrid reduces TCO and shortens NPI cycles for customer‑specific components.
- Differentiate with value services: expand offering beyond commodity sheets to include in‑house machining, assembly services, and material traceability packages. Service differentiation reduces price sensitivity and raises switching costs.
- Targeted M&A/joint ventures: pursue tuck‑ins that add fabrication capability, certification credentials or complementary resin technology rather than broad horizontal consolidation. Our target screening framework prioritizes accretive deals that deliver immediate synergies and protect against upstream shocks.
How PW Consulting’s report accelerates 2026 execution
This study is designed as a decision‑support pack rather than a descriptive white paper. Executives receive:
Worldwide LIMS Software Market
- Ready‑to‑use financial models and price‑sensitivity dashboards that integrate epoxy resin price scenarios and supplier contract structures.
- Supplier heatmaps and capability matrices to inform near‑term sourcing awards and 12‑month contingency plans.
- M&A playbooks and integration checklists that reduce execution risk and speed commercial capture post‑transaction.
- Go‑to‑market roadmaps with prioritized 90/180/360 day actions for product qualification, channel deployment, and regulatory alignment.
Concluding perspective
For 2026, the industrial epoxy glass market presents a clear task for executives: convert steady top‑line growth into durable margin expansion through disciplined feedstock risk management, accelerated product qualification in premium niches, and pragmatic supply‑chain design. The market’s aggregated growth profile (with a projected step‑up from the 2025 base into 2026 and a mid‑to‑high single‑digit trajectory through 2032) rewards early strategic moves that shorten qualification timelines, secure feedstock economics, and align capacity with differentiated product portfolios.
PW Consulting’s full Worldwide Industrial Epoxy Glass Market report contains the complete segmentation, supplier-level scorecards, and the detailed datasets required to operationalize these strategies. For executives building 2026 playbooks, the report provides the empirical backbone and practical toolkits to move from planning to decisive action.
For detailed analysis of this topic, please visit the official page: Worldwide Industrial Epoxy Glass Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Insulinoma Market Poised to Grow at a 5.75% CAGR Through 2032, New Report Finds
By pmarketresearch, 2026-08-12
Worldwide Insulinoma Market: Strategic Preview for 2026 — A PW Consulting Report Release
PW Consulting today releases an executive preview of our forthcoming Worldwide Insulinoma Market study (base year 2025, historical analysis 2020–2025, forecast 2026–2032). The insulinoma ecosystem is entering a phase of clinically driven inflection: the specialized market has expanded from roughly USD 126.12 Million in 2020 to an estimated USD 166.8 Million in 2025, and our long-range modeling projects growth to approximately USD 246.68 Million by 2032. Across the forecast window, the market’s compound annual growth rate (CAGR) of 5.75% reflects a balance of incremental clinical innovation, constrained patient populations, and concentrated clinical adoption pathways. This preview outlines the strategic implications for corporate decision‑makers in 2026 while deliberately withholding granular subsegment tables to encourage engagement with our full dataset and interactive models.
Worldwide Dual-side Aligners Market
Why 2026 Is a Strategic Inflection Point
-
Clinical readouts and regulatory alignments are converging. Near-term pivotal trials and confirmatory development programs — including a Phase 3 program employing an FDA-aligned single-arm design — create a compressed timeline for go/no-go decisions and commercial planning.
Worldwide Interventional Pulmonology Market -
Patient populations are small but clinically acute. Epidemiology remains rare (estimated incidence ranges), and a measurable portion of malignant cases are refractory to standard surgical and first-line medical management. These characteristics create high per-patient value but also place a premium on targeted evidence generation and payer negotiation.
Internet Intelligent Elderly Care Service Platform Market -
Treatment pathways remain anchored by surgical resection for curative intent; however, inoperable or malignant presentations rely on medical management where diazoxide and somatostatin analogs remain mainstays. Emerging targeted biologics and peptide therapies are positioned to disrupt these pathways, contingent on robust efficacy and safety data.
What the PW Consulting Report Delivers — Practical, Actionable, and Executable
Our full report is built for decision-makers who must convert scientific opportunity into commercial value. Highlights of the practical deliverables included in the study:
- Robust market-sizing methodology with reconciled top‑down and bottom‑up approaches, including sensitivity analyses to reflect varying uptake and reimbursement scenarios.
- Scenario-based forecasts that quantify the commercial impact of alternative clinical outcomes (pivotal success, partial response, or negative readouts) and regulatory pathways.
- Clinical-to-commercial maps that align patient segments, diagnostic pathways, and treatment sequences to inform clinical trial inclusion criteria and post-approval evidence plans.
- Detailed go‑to‑market playbooks: launch sequencing options, center-of-excellence targeting, specialist and multidisciplinary referral dynamics, and field force design tailored to ultra-rare oncology/endo markets.
- Pricing and reimbursement models reflecting orphan-value frameworks, HTA expectations, and payer negotiation levers across major markets.
- M&A and partnership scorecards assessing potential bolt-ons (diagnostics, specialty manufacturing, commercial distribution) and coalition strategies for de‑risked market entry.
- Customizable Excel workbooks and interactive dashboards for client-side scenario modeling — allowing teams to run “what‑if” cases that translate trial outcomes directly into revenue and access timelines.
We intentionally present these capabilities in outline here. The full intelligence pack contains the granular regional, treatment-type, and end‑user splits, plus patient flow analytics and unit‑economics models available through PW Consulting’s report portal.
Competitive Landscape — Focused Analysis on Rezolute, Inc.
Among emerging clinical-stage entrants, Rezolute, Inc. merits focused attention. Headquartered in Redwood City, California, Rezolute is advancing ersodetug (RZ358), an anti-insulin monoclonal antibody aimed at tumor-mediated hyperinsulinism, including malignant insulinoma and cases of refractory hypoglycemia. Recent regulatory alignment in September 2025 established an FDA‑accepted streamlined single‑arm, open‑label Phase 3 upLIFT design targeting a limited cohort; topline data are expected in H2 2026, while an ongoing congenital hyperinsulinism program (sunRIZE) is positioned to serve as supportive/confirmatory evidence.
Strategic implications of Rezolute’s program for industry participants and investors:
- Regulatory precedence: The FDA’s openness to cross‑program confirmatory evidence (congenital HI data supporting a tumor HI indication) signals a pragmatic regulatory pathway for rare-disease agents, but it also raises the evidentiary bar for cross-indication generalizability.
- Commercial timing and exclusivity: A positive H2 2026 topline could catalyze rapid single-product launches into specialized centers, but commercialization scale will be determined by labeling breadth, reimbursement recognition, and manufacturing capacity for biologics.
- Value creation vector: For small populations with high unmet need, the premium pricing window is tangible — yet payers will demand outcomes-based evidence, compendia support, and budget-impact mitigation strategies (e.g., restricted distribution, step edits, or coverage with evidence development).
- Investor signal: Early positive readouts in focused cohorts can materially re-rate companies, but downside risk is amplified given the narrow patient base; portfolio diversification or alliance strategies can mitigate binary outcome risk.
At the market level, concentration metrics indicate a moderately concentrated supplier landscape, underscoring opportunities for distinctive therapeutic differentiation as well as the importance of strategically scoped partnerships to access diagnostic and specialist channels.
Implications for Corporate Strategy in 2026 — Priorities and Tactical Roadmap
For executives planning resource allocation in 2026, PW Consulting recommends a triage of strategic priorities matched to timing sensitivities:
- Q1–Q2 2026 — Regulatory and Evidence Playbook: Engage with regulators early to align confirmatory evidence strategies; refine statistical plans to maximize label flexibility; prepare companion diagnostic strategies when appropriate.
- Q2–Q3 2026 — Commercial Readiness & Access Modeling: Build payer dossiers and health economic models now to accelerate reimbursement conversations upon topline announcements; pre-identify centers of excellence and referral networks to shorten time-to-therapy.
- Q3–Q4 2026 — Manufacturing & Supply Chain: Validate biologic manufacturing scale scenarios and secondary suppliers; develop a distribution plan that supports restricted channeling where clinically appropriate.
- Continuous — Portfolio Risk Management: Prepare contingency pathways (combination therapies, label extensions, diagnostic-driven subpopulations) should pivotal outcomes be partial or require additional evidence.
Scenario Planning — Translating Trial Outcomes into Market Trajectories
Our report models three high-level scenarios and translates each into commercial and strategic actions:
- Optimistic (robust pivotal shown): Expect accelerated uptake in specialized centers, favorable orphan pricing dynamics, and an elevated investment case for expansion into adjacent indications. M&A activity intensifies around complementary diagnostics and distribution capabilities.
- Moderate (efficacy signals but limited durability): Adoption concentrates in refractory cohorts and compassionate-use pathways; payers seek outcome-contingent agreements and tighter utilization controls; firms invest in real-world evidence generation to broaden access.
- Conservative (negative/ambiguous readout): Standard-of-care dominance persists; companies pivot to combination strategies or focus on incremental improvements in supportive care and symptom management.
Each scenario has been stress-tested against the base-market trajectory (CAGR 5.75%), and the variations inform prioritized investment, partnership, and commercialization pathways. The full report contains the quantitative scenario outputs and sensitivity matrices underpinning these narratives.
How PW Consulting’s Intelligence Accelerates Decision-Making
Leaders who use our insulinoma market intelligence gain three practical advantages:
- Speed: Pre-built models and playbooks reduce time-to-decision during narrow regulatory windows and near-term trial readouts.
- Precision: Integrated clinical, commercial, and payer perspectives convert a rare-disease scientific narrative into executable revenue and access plans.
- Optionality: Scenario planning enables dynamic capital allocation and partnership structuring that preserves upside while limiting downside exposure.
Next Steps
This preview is intended to establish the critical strategic contours for 2026. PW Consulting’s full Worldwide Insulinoma Market report contains the proprietary regional, treatment-type, and end‑user breakdowns, full company profiles, raw model files, and an advisory package for bespoke client workshops. For teams preparing to act around the H2 2026 readouts and subsequent reimbursement windows, the full dossier and our on-demand consulting services will be indispensable.
To request access to the complete report, download sample modeling templates, or schedule a briefing with our lead analysts, visit the PW Consulting report page or contact our client services team. Our analysts stand ready to translate the data into a tailored roadmap that aligns clinical timelines with commercial reality.
For detailed analysis of this topic, please visit the official page: Worldwide Insulinoma Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Predicts Worldwide Laboratory Glass Container Market to Grow at a 5.42% CAGR During 2026–2032
By pmarketresearch, 2026-08-12
Worldwide Laboratory Glass Container Market 2026: Strategic Imperatives for Corporate Decision‑Makers
PW Consulting today releases the executive preview of its forthcoming Worldwide Laboratory Glass Container Market report (base year 2025; forecast period 2026–2032). The global market for laboratory glass containers—used across pharmaceutical, biotechnology, academic research, clinical diagnostics, and industrial laboratories—was estimated at USD 4,255.5 Million in 2025 and is projected to expand to approximately USD 6,157.6 Million by 2032, growing at a compound annual growth rate (CAGR) of 5.42% across the forecast horizon. This preview outlines the strategic value of the full study for corporate planning in 2026 while intentionally withholding core segment-level tables and channelized figures to encourage direct engagement with the full report for actionable detail.
Worldwide Plating Bath Analysis Services Market
Why this market matters for 2026 planning
-
Demand resilience and quality premiumization: Laboratory glassware remains indispensable where chemical resistance and thermal stability are mission‑critical. The market’s steady mid-single-digit CAGR reflects enduring demand from regulated end markets even as consumable substitution and plastics adoption create pockets of competitive pressure.
Algo Trading Software Market -
Raw material and input cost dynamics: Borosilicate glass—the material of choice for high‑performance laboratory containers—faces upward cost pressure driven by rising boron compound prices and supply constraints. These dynamics are already influencing manufacturers’ cost structures and margin planning for 2026.
Worldwide ODM Smartphones Market -
Competitive concentration and consolidation signals: The market exhibits moderate concentration among top players, with the three largest firms accounting for a material share and the top five aggregating a clear majority of established premium capacity. This structure creates both defensive imperatives for incumbents and opportunities for well‑capitalized challengers to gain share through targeted M&A and capability investments.
What leaders need from this report in 2026
-
Portfolio prioritization: The full report provides a decision framework for prioritizing product lines (e.g., volumetric ware, sample vials, cell culture systems) against margin profiles, regulatory risk, and capital intensity. Executives can use our playbooks to rationalize SKUs, accelerate high‑value SKUs, or sunset non‑strategic items while protecting customer retention metrics.
-
Supply‑chain resilience planning: Our scenario modelling quantifies the potential P&L impact of boron price volatility and kiln capacity disruptions. The study includes mitigation tactics—strategic raw material contracting, backward integration feasibility checks, and alternative material pathways—tailored to different company archetypes.
-
Go‑to‑market and channel moves: For manufacturers and distributors, the report synthesizes channel dynamics—direct sales, distributors, and e‑commerce—offering playbooks for optimizing distribution agreements, negotiating margin levers, and executing targeted field sales initiatives in priority end markets.
-
M&A and inorganic growth mapping: We present a vetted pipeline of acquisition archetypes and integration risk matrices to help buyers and sellers calibrate valuations in a market where strategic assets (specialty borosilicate lines, pharmaceutical primary packaging capabilities, or global distribution networks) command premiums.
Practical contents and tools included in the full PW Consulting study
-
Market sizing and seven‑year scenarios: Bottom‑up and top‑down sizing with downside and upside cases—useful for stress testing revenue plans under alternative macro and commodity scenarios.
-
Competitive benchmarking: Proprietary supplier scorecards across manufacturing footprint, product breadth, regulatory certifications, and time‑to‑market. These are accompanied by actionable supplier development plans and KPIs to accelerate improvement cycles.
-
Segment playbooks: For each product family and end‑use cohort, we provide value‑chain economics, margin waterfall modelling, and recommended commercial tactics—without disclosing sensitive breakouts in this preview.
-
Procurement negotiation templates: Practical contract clauses for long‑lead raw materials, indexing recommendations for variable cost elements, and sample hedging strategies tailored to glass production timelines.
-
CapEx decision support: Payback modelling and capacity utilisation scenarios for greenfield and brownfield investments, including a decision matrix for conversion versus new build when expanding borosilicate production lines.
-
Regulatory and compliance mapping: Global regulatory touchpoints for pharmaceutical primary packaging and sterile containers, with a checklist for qualification, stability testing requirements, and audit readiness for 2026 inspections.
Competitive landscape: what the leaders and challengers are doing
Our analysis of key players shows a marketplace where legacy brands, engineering innovators, regional specialists, and integrated pharma suppliers each play distinct strategic roles. Top multinational glassmakers continue to defend premium positions with strong brand equity and global manufacturing footprints. Specialist firms—often family‑owned or regionally concentrated—leverage agility and deep customer relationships to serve bespoke laboratory and pilot production needs.
-
Legacy premium manufacturers: Longstanding brands known for high thermal and chemical resistance maintain pricing power in regulated applications. Their investments in process control, quality systems, and validated packaging solutions make them default partners for large pharmaceutical clients.
-
European precision producers: Firms with origins in volumetric and high‑precision glassware are extending into pharmaceutical and analytical vials, often via technology tie‑ups or product diversification strategies.
-
Indian and regional industrial players: Cost‑competitive manufacturers from South Asia and Eastern Europe have expanded capabilities, in some cases moving up the value chain through acquisitions or partnerships to offer broader portfolios and localized supply benefits.
-
Distributors and channel consolidators: Distribution agreements and expanded network reach remain an important avenue for market access. Recent distribution moves demonstrate how partnership reconfiguration can rapidly alter go‑to‑market dynamics in important national markets.
Two recent developments captured in our mapping illustrate these forces at work. First, a notable industrial player executed a strategic shift from a pure glassware manufacturer into adjacent analytical vials, filtration, and primary pharma packaging through targeted acquisitions—reflecting an industry impulse toward portfolio diversification and vertical adjacency. Second, a life‑science equipment supplier expanded its distribution footprint with major laboratory channel partners to increase reach for consumables and small instrumentation—underscoring the importance of channel partnerships in accelerating market access.
Strategic implications for five types of market participants
-
Global manufacturers: Prioritize hardened relationships with pharmaceutical customers, invest selectively in validated packaging capacity, and consider bolt‑on acquisitions that provide regulatory dossiers and qualification histories.
-
Regional producers: Accelerate upward migration to higher‑margin specialty products, invest in quality systems that meet pharma clientele expectations, and build distribution alliances to scale beyond domestic markets.
-
Distributors: Reassess exclusive agreements and hybrid distribution models that combine inventory pooling with vendor‑managed inventory to protect fill‑rates amid supplier cost pressure.
-
Private equity and strategic acquirers: Use our valuation matrices and integration playbooks to identify targets where manufacturing scale, technology differentiation, or distribution footprint unlock rapid synergies.
-
Procurement organizations: Apply our commodity stress tests and contract templates to renegotiate supplier terms, implement indexed pricing clauses, and explore dual‑sourcing for critical borosilicate inputs.
Risk factors and mitigation
-
Commodity inflation: Boron cost escalation and energy price volatility are the most immediate input risks. Mitigation includes long‑term supply contracts, formula‑based pricing, and selective vertical integration evaluation.
-
Substitution risk: Plastics and engineered polymers are encroaching in non‑critical applications. Manufacturers should sharpen value propositions around thermal/chemical performance and invest in marketing that translates technical superiority into purchasing decisions.
-
Regulatory and qualification hurdles: Pharmaceutical customers require validated supply chains and documentation. Investment in compliance infrastructure is non‑negotiable for suppliers targeting high‑growth regulated segments.
-
Capacity and lead times: Furnace and annealing capacity constraints can create bottlenecks. Our capacity planning templates help quantify capex lead times versus expected demand ramps.
Methodology and data confidence
PW Consulting’s full report synthesizes primary interviews with C‑level executives, procurement heads, and plant managers across the value chain, supplemented by trade data, customs flows, and factory‑level cost modelling. We triangulate demand forecasts with end‑market drivers—pharma R&D spending, diagnostic testing volumes, and laboratory infrastructure investments—producing a market view grounded in transactional reality and stress‑tested under multiple macro scenarios.
How to use this preview
This preview is designed as a strategic trailer: it demonstrates analytical depth and provides enough directional insight to inform early 2026 planning but deliberately withholds detailed segment figures, regional splits, and proprietary benchmarking that appear in the full report. For planners needing the decisive, quantified inputs for budgeting, M&A underwriting, and procurement renegotiation, the full report contains downloadable models, supplier scorecards, and CapEx templates.
Next steps
-
For access to the complete Worldwide Laboratory Glass Container Market report, including all segment tables, interactive models, and supplier scorecards, contact PW Consulting or visit our reports portal.
-
PW Consulting is offering a limited series of 60‑minute strategy briefings for clients who purchase the full study before Q3 2026. These sessions include bespoke scenario modelling applied to your company’s portfolio.
PW Consulting remains committed to equipping executive teams with field‑tested frameworks and practical tools to turn market insight into competitive advantage. The laboratory glass container market may look stable at the headline level, but beneath the surface, commodity tides, channel shifts, and targeted consolidation activity will determine winners and laggards in 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Worldwide Laboratory Glass Container Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com