

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecasts Worldwide Reformer Unit Market to Expand at 6.95% CAGR During 2026–2032

Worldwide Reformer Unit Market 2026 — Strategic Imperatives for Executives and Investors
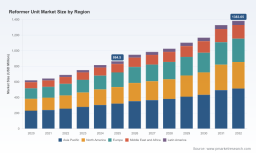
As energy-transition timelines accelerate and industrial decarbonization becomes a boardroom priority, PW Consulting’s latest Worldwide Reformer Unit Market report surfaces as a practical decision-support instrument for 2026. Built on a 2020–2025 historical foundation and a 2026–2032 forecast horizon, the study quantifies a market that reached USD 864.5 Million in 2025 and—assuming current trajectories—expands at a 6.95% compound annual growth rate to approach USD 1,383.65 Million by 2032. The analysis blends quantitative rigor with executable guidance, enabling commercial leaders to align project pipelines, procurement strategies, and technology choices with near-term regulatory and cost pressures while preserving optionality for longer-term low‑carbon pathways.
Embryo Holding Medium Market
What the report delivers — practical, actionable intelligence
-
Consolidated market sizing and trend trajectories (base year 2025; historical window 2020–2025; forecast 2026–2032) with scenario-run sensitivities that stress-test demand under different carbon-pricing and technology-adoption assumptions.
Worldwide Commercial Collection Service Market -
Technology roadmaps and retrofit matrices for steam methane reformers (SMR), catalytic reformers, and autothermal reformers (ATR), including electricity‑integration readiness, heat‑integration opportunities, and CCS compatibility checklists.
Worldwide Portable Electric Scooter Market -
Vendor benchmarking and procurement playbooks covering licensing, EPC selection criteria, modular vs. stick-built trade-offs, and long‑lead component procurement timing to manage CAPEX and schedule risk.
-
Operational levers for reducing total cost of ownership—catalyst lifing strategies, tube metallurgy choices, predictive maintenance KPIs, and turnaround optimization—backed by component-life modeling and supplier warranties analysis.
-
Policy, regulatory and market stress tests mapping—how energy efficiency mandates, carbon pricing, and local content requirements alter project IRR, payback, and preferred technology pathways.
-
Case studies and templated action plans for hydrogen, ammonia, methanol and refinery-integrated applications that translate market dynamics into executable steps for 12–36 month horizons.
Why the report matters to 2026 corporate strategy
Three structural forces will shape reformer decisions in 2026: tightening climate policy, capital discipline under volatile commodity cycles, and the accelerating hydrogen economy. Regulatory attention and carbon-pricing mechanisms are increasing the economic penalty for unabated CO2 from conventional fuel-fired reformers, which is catalyzing adoption of electrification and CCS-ready configurations. Academic and pilot data show electrified steam reformers (e‑REFORMER) can materially lower direct flue-gas CO2 emissions—reported reductions of up to 91.56% in select ammonia plant retrofit scenarios—while improving thermal efficiency metrics (reported improvements from ~85.6% to ~88.9% in those cases). Translating those technical gains into bankable projects requires careful alignment of technology risk, offtake structures, and available green‑power contracts.
Concurrently, raw-material cycles matter. Global steel prices were at or near the bottom of the current price cycle in early 2026, with subdued recovery expected through the year and a more meaningful upturn projected from 2027. For executives that manage long‑lead items (reformer tubes, pressure vessels, and critical cast components), this implies an asymmetric procurement opportunity window in 2026 to lock favorable pricing and delivery dates—while balancing inventory, depreciation and cash constraints.
Competitive landscape — what to watch
The reformer ecosystem blends full‑stack licensors and EPCs with specialist equipment, catalyst, and metallurgy suppliers. Market concentration is meaningful but not prohibitive: our concentration metrics indicate the top three players hold a substantial share while the top five approach a clear majority—signalling an environment where established licensors and global EPC houses shape technology roadmaps, yet specialist suppliers can capture high-margin niches.
-
Linde Engineering (Selas‑Linde) — A global leader in steam reformer supply with a long installed base and modular HYDROPRIME® solutions designed for on‑site and low‑emission projects. Its experience in varied feedstocks and modular configurations positions it as a preferred partner for rapid decarbonization projects and small on‑site hydrogen solutions.
-
Honeywell UOP & Axens — Both maintain strong positions on catalytic reforming technology and licensing. Their portfolios and catalyst ecosystems make them pivotal to refiners optimizing gasoline quality and aromatics production where catalytic routes remain core.
-
KBR & Technip Energies — These engineering and technology providers drive major SMR and ATR projects, blending process licensing with EPC delivery. Their involvement is often decisive for large‑scale hydrogen and syngas projects where integration and project execution risk dominate.
-
Johnson Matthey — A critical supplier of reforming catalysts whose choices materially influence per‑unit production economics and catalyst exchange cycles, especially in ammonia and methanol contexts.
-
MetalTek International & Kubota Corporation — Specialist manufacturers of reformer tubes and high‑temperature components. Their materials science and casting practices directly affect tube life, maintenance cadence, and turnaround cost; improvements here unlock multi‑year OPEX savings.
-
Wood plc & Larsen & Toubro — Engineering, consulting and construction firms that provide integration, EPC and regional execution expertise; essential partners for translating licensor designs into constructible, financeable projects.
Recent market movements underscore these dynamics: licensors and equipment suppliers reported record on‑site hydrogen project wins and long‑term industrial gas agreements in 2025, and research presentations in late 2025 highlighted electrification of steam reformers as a credible decarbonization pathway. Together, these signals point to accelerating activity at the intersection of low‑carbon hydrogen and ammonia project pipelines.
Commercial implications — recommended near‑term moves for 2026
-
Prioritize modularity for early‑stage decarbonization projects. Modular and skid‑mounted reformers can de‑risk first‑mover projects, compress timelines and simplify contractual interfaces—especially for green ammonia and on‑site hydrogen applications.
-
Lock critical long‑lead items in 2026 where price momentum favors buyers, but avoid overcapitalizing inventory. Balance vendor financing and staged delivery to preserve flexibility for electrification or CCS retrofits.
-
Seek catalyst and metallurgy partnerships that include outcomes‑based guarantees (e.g., tube life, catalyst cycle lengths). Small gains in operational life translate into disproportionate OPEX reductions across a multi‑year asset horizon.
-
Design new projects with CCS and electrification compatibility as default options. Even if not deployed immediately, specifying space, tie‑ins and interconnection capacity early reduces retrofit premium and stranded‑asset risk.
-
Adopt a two‑track procurement strategy: engage top global licensors for core process risk control while qualifying select specialist suppliers to extract efficiency and lifecycle gains.
-
Run rapid scenario economics across carbon‑price sensitivities and fuel‑cost volatility—embed these outputs into investment committees to rationalize go/no‑go timing and offtake pricing.
Methodology & data integrity
The report’s base year is 2025, with historical coverage from 2020–2025 and a forecast window stretching 2026–2032. Our headline CAGR for the forecast period is 6.95%. Estimates leverage primary interviews with licensors, EPC contractors, OEMs and end‑users; secondary sources including industry publications, trade data, patent filings and tender activity; and bottom‑up modeling of capex, feedstock and operating assumptions. Market concentration metrics (top‑3 and top‑5 shares) are included as governance indicators for competitive risk assessment. For confidentiality and strategic positioning reasons this executive summary purposefully omits granular segment share tables; the full dataset, segmentation matrices and supplier scorecards are available in the complete report.
How to use this analysis in 2026 planning cycles
-
Board level: Use our scenarios to stress-test portfolio exposures to carbon pricing and to define threshold conditions for brown‑to‑green capex redirection.
-
Project teams: Apply the retrofit matrices and vendor scorecards during FEED to reduce scope creep and to secure performance guarantees that align with low‑carbon ambitions.
-
Procurement: Combine short‑term tactical buys for long‑lead items with strategic supplier partnerships for catalysts and metallurgy to reduce TCO.
-
Investors & lenders: Use the report’s risk‑adjusted forecasts to calibrate financing terms and to set technical milestones tied to disbursement.
Conclusion & next steps
PW Consulting’s Worldwide Reformer Unit Market report translates a shifting regulatory and cost environment into a pragmatic playbook for 2026. The sector is expanding—with a clear trajectory reflected in the reported USD 864.5 Million market size for 2025 and a near‑7% CAGR through 2032—yet the pathway to sustainable, bankable projects will be decided by a few critical choices: timing of procurement, modularization vs. bespoke engineering, catalyst and metallurgy strategies, and the degree to which CCS and electrification are embedded from day one.
To review the full segmentation breakdowns, supplier scorecards, and downloadable financial models, access the complete report and appendices on the PW Consulting research portal. The summary above is intentionally selective—designed to demonstrate our analytic depth and to invite strategic engagement; the full intelligence package contains the granular data and templates necessary to operationalize the recommendations for immediate 2026 planning cycles.
For detailed analysis of this topic, please visit the official page: Worldwide Reformer Unit Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com