

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Acute Ischemic Stroke Market Projected to Grow at a 7.82% CAGR Through 2032

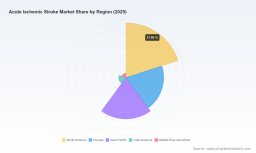
Worldwide Acute Ischemic Stroke Market — Strategic Preview for 2026 Decision-Makers
PW Consulting’s latest market intelligence brief, "Worldwide Acute Ischemic Stroke Market (Base Year 2025)", synthesizes clinical, commercial and policy signals into an actionable view that materially changes how medtech, pharmaceutical and health systems should plan for 2026. Our bottom-up model projects a robust market expansion beginning in 2026, driven by updated clinical guidance, improving reimbursement, and accelerating device innovation. Between the 2025 base year and the end of our forecast window, the market expands at a compound annual growth rate of 7.82%, delivering significant value creation opportunities across product classes and geographies.
Worldwide Excavator Multi-Processors Market
Why this report matters for 2026 strategy
Executives preparing 2026 budgets and strategic plans need forward-leaning intelligence that translates clinical momentum into commercial choices. The clinical eligibility window expansion and rising AIS incidence are changing patient volumes and the addressable opportunity for thrombectomy systems, aspiration platforms, and adjunctive therapies. At the same time, meaningful reimbursement actions and regulatory acceleration are lowering commercialization barriers for novel entrants while altering pricing dynamics for incumbents.
Smart Wearable Coin Battery Market
-
Investment prioritization: The report turns macro trends into capital allocation guidance — where to scale clinical evidence generation, when to accelerate regulatory filings, and which partnerships will shorten time-to-revenue in 2026.
Worldwide Legal Research Software Market -
Go-to-market calibration: We map evolving care pathways to channel economics, helping commercial leaders optimize hospital contracting, specialty clinic partnerships, and ambulatory surgical center penetration for the coming growth window.
-
M&A and portfolio plays: Our scenario-based models reveal where tuck-ins and bolt-ons create asymmetric upside versus where greenfield R&D is required — an essential input for 2026 deal calendars.
Market trajectory and the drivers that matter
PW Consulting’s analysis integrates historical performance (2020–2025) with granular assumptions to produce a 2026–2032 forecast that reflects new clinical guidelines and policy shifts. The base-year market in 2025 stands at USD 10,750 Million (revenue unit: Million, USD). Under current assumptions the market advances strongly after 2026 and reaches a materially larger size by 2032, reflecting compounded increases in patient eligibility, device penetration, and procedural intensity.
Key demand-side drivers:
-
Clinical guideline evolution: The AHA/ASA 2024 expansion of thrombectomy eligibility to selected patients up to 24 hours fundamentally expands the population that will be triaged for endovascular intervention. This is not theoretical — it changes hospital workflows, imaging investment decisions, and the cadence of interventional cases in 2026.
-
Demographics and incidence: Age-driven prevalence trends project substantial increases in AIS cases in major markets; PW’s synthesis of epidemiologic forecasts suggests clinically material growth by 2030 and beyond.
-
Reimbursement shifts: CMS’s FY2026 update to NTAP creates a step-function change in device economics for eligible thrombectomy systems. That policy alters negotiation dynamics between providers and manufacturers and shortens payback thresholds for hospital capital investment.
Supply-side forces shaping 2026 strategies:
-
Regulatory acceleration: A rise in Breakthrough Device Designations and other expedited pathways has compressed time-to-market for several novel thrombectomy systems, altering competitive timing and the value of first-mover clinical data.
-
Innovation in device platforms: New-generation stent retrievers, aspiration technologies, and integrated access platforms are increasing procedural efficiency and shifting preference patterns among neurointerventionalists. Recent product launches and clearances in late 2024–2025 validate this trend.
-
Supply-chain risk and cost pressure: Tariff adjustments on imported components have introduced new cost considerations, especially for manufacturers relying on cross-border neurovascular component sourcing. Procurement teams should build sensitivity to input-cost volatility into 2026 pricing scenarios.
Competitive landscape — what incumbents and challengers signal for 2026
The AIS device market is innovation-intensive and clinically driven. PW’s competitive analysis highlights four strategic archetypes operating in parallel: category leaders scaling clinical evidence and channel reach; fast-follow platform innovators optimizing procedural efficiency; niche players targeting differentiated access or adjunctive therapies; and new entrants leveraging regulatory fast-tracks.
-
Stryker Corporation — continues to reinforce its mechanical thrombectomy leadership through iterative product launches and expanded clinical applications. Recent innovations focused on complex aneurysm and flow-diversion adjuncts illustrate a dual strategy of protecting core thrombectomy share while growing adjacent neurovascular categories.
-
Medtronic plc — combines long-duration clinical evidence with aspiration and retriever platforms. Positive medium-term clinical data reported in 2025 strengthens adoption narratives and supports premium positioning in hospital procurement processes.
-
Johnson & Johnson (Cerenovus) — following regulatory approvals for next‑generation devices, the company is pursuing aggressive evidence generation and hospital-level integration, positioning to capture large-vessel occlusion cases where device performance and workflow integration matter most.
-
Penumbra, Inc. — with new regulatory clearances in 2025 for faster aspiration systems, Penumbra is executing on an aspiration-led differentiation that shortens procedure times and improves throughput, a compelling commercial message for cash-strapped stroke centers.
-
Balt USA, Terumo, MicroVention, Rapid Medical — these regional and niche specialists are executing targeted clinical programs, expanding geographic footprint and, in some cases, leveraging CE Mark or other approvals to accelerate European and APAC growth. Their focused product strategies create tactical threats to incumbents in price-sensitive or access-constrained settings.
Taken together, these moves indicate a market where product performance, procedure economics, and evidence generation will determine share shifts in 2026. Our analysis suggests that clinical endorsements and a few decisive regulatory clearances this year will disproportionately influence procurement cycles next year.
What the report contains — practical deliverables
PW Consulting’s report is designed for 2026 execution. It does not stop at high-level forecasts; it provides a toolkit to act immediately:
-
Proprietary forecast model (2026–2032) with scenario toggles for guideline adoption, reimbursement realization, and tariff impacts — enabling CFOs to run revenue and margin sensitivity analyses for planning cycles.
-
Clinical pathway maps that translate guideline changes into patient flows and procedure volumes by care setting, with tactical recommendations for training, imaging investments, and hub-and-spoke network design.
-
Commercial playbooks covering pricing levers, hospital contracting templates, and value-based propositions aligned with expected NTAP reimbursements and payer negotiation windows.
-
M&A screening and diligence checklists that prioritize targets by technological fit, geographic lift, and clinical evidence maturity — including shortlists derived from primary clinician and payer interviews.
-
Regulatory and reimbursement roadmaps per major market, including time-to-reimbursement estimates and policy-risk heatmaps to support 2026 launch sequencing.
To preserve competitive advantage for our clients, the report intentionally omits raw subsegment disclosures in public summaries; detailed regional, treatment-type and end-user breakdowns, as well as interactive dashboards and model inputs, are available to licensed purchasers.
How to use these insights in 2026 planning
-
Prioritize evidence investments that close the smallest clinical gaps with the biggest commercial returns. Our value-mapping engine quantifies ROI of incremental trial endpoints and registry participation relative to procurement timelines.
-
Lock in supplier diversification and tariff mitigation plans for any component exposure tied to vulnerable geographies. The model shows breakeven points for localized manufacturing or long-term supply agreements under tariff stress scenarios.
-
Align commercial rollouts with reimbursement timing. For manufacturers, synchronizing regulatory milestones with anticipated NTAP and payer coverage shifts materially shortens the sales cycle in 2026.
-
For health systems and hospital groups, the playbooks provide a clear framework for capacity expansion decisions: which centers to upgrade, when to centralize advanced care, and how to negotiate device-bundle pricing to protect margins as case volumes grow.
Methodology and editorial rigor
Our findings synthesize primary interviews with neurointerventionalists, hospital procurement leads, and payers; a proprietary device and procedure-volume model; regulatory and reimbursement tracking; and a thorough review of recent product launches and clinical studies. We triangulate public filings, regulatory databases and primary research to ensure our 2026 planning assumptions are grounded in observable market moves, including the notable product launches, clearances and study readouts in 2024–2025.
Next steps — where to get the full intelligence
This release is a deliberate preview: it demonstrates the analytic depth clients rely on while reserving granular subsegment and interactive model access for licensed report purchasers. If your 2026 plan depends on capturing value in the acute ischemic stroke ecosystem — whether as a manufacturer, investor, or health system — schedule a briefing with PW Consulting to obtain the full forecast model, bespoke scenario runs, and the commercial playbooks that operationalize these insights.
Contact PW Consulting to request an executive briefing and unlock the full dataset and dashboards that power fiscally responsible, clinically aligned decision-making for 2026.
For detailed analysis of this topic, please visit the official page: Worldwide Acute Ischemic Stroke Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com