

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecasts 5.4% CAGR for Worldwide Subsea Well Access and BOP System Market Through 2032

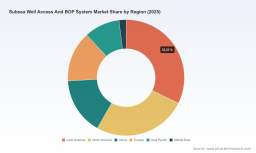
Worldwide Subsea Well Access and BOP System Market: Strategic Imperatives for 2026 Decision-Makers
PW Consulting’s latest market study on Worldwide Subsea Well Access and Blowout Preventer (BOP) Systems delivers a forward-looking playbook tailored for executives, investors and operational leaders preparing for the 2026 planning cycle. Drawing on a five-year historical lens (2020–2025) and a seven-year forecast (2026–2032), the study synthesizes market sizing, competitive dynamics, regulatory inflection points and technology trajectories into a decision-ready framework. The headline: the global market—measured in USD millions—stands at an established base in 2025 and is projected to grow at a compound annual growth rate (CAGR) of 5.4% through 2032, reaching roughly the mid‑single‑billion mark by the end of the forecast horizon.
Worldwide FR PP Compounds Market
Why this report matters for 2026
-
Timing: As operators and OEMs set capital allocation, supply‑chain commitments and technology roadmaps for 2026, this study isolates the structural drivers that will determine where returns accrue vs. where investments are likely to underperform.
Gas Station Canopy Light Market -
Actionability: Beyond topline forecasts, the research delivers scenario‑based implications for procurement strategy, product development priorities, and commercial contracting—critical inputs for near‑term multi‑year budgets.
Worldwide Haarlem Oil Market -
Risk‑adjusted insights: The report overlays regulatory and materials risk vectors (e.g., API and NACE compliance, alloy supply pressures) onto demand forecasts, allowing decision-makers to stress‑test projects against compliance and sourcing shocks.
Market outlook — what the numbers mean
Our analysis shows a steady recovery and expansion trajectory following the recent market trough and rebound. With the market growing at a 5.4% CAGR across the forecast period, the sector’s expansion is driven by persistent deepwater/ultra‑deepwater activity, a renewed push into frontier basins, and a parallel rise in intervention and decommissioning operations that require advanced well access solutions. For 2026 planning, the implication is clear: the addressable market is expanding sufficiently to justify both selective greenfield investments and capability upgrades for established suppliers, while creating differentiated opportunities for specialist service providers.
Importantly, market concentration metrics reveal a moderately consolidated landscape: the top three suppliers control just over half of the market, while the top five account for more than three quarters. That structural concentration underscores two competing strategic pathways for investors and mid‑tier vendors—scale-driven consolidation or focused differentiation via technology and service specialization.
Key industry dynamics shaping 2026 decisions
-
Regulatory and technical thresholds: Compliance with API standards for BOPs and intervention systems, alongside NACE requirements for sour service materials, is non‑negotiable. The push toward higher pressure ratings—examples of industry development work toward 20,000 psi class equipment—raises both certification and materials complexity, lengthening lead times and raising unit engineering costs.
-
Material and supply‑chain pressures: Production of high‑strength, corrosion‑resistant alloys is a gating item for BOP manufacturing. OEMs that secure reliable alloy supply and verticalize quality control will be advantaged in win rates and delivery performance.
-
Technology convergence: Intervention solutions—riserless, workover and integrated tree‑plus‑well access systems—are converging toward modular, serviceable architectures that reduce vessel dependency and lower operational risk. Novel valve designs that consolidate functions are already in market, and operators will prioritize interventions that demonstrably lower total intervention cost and failure risk.
-
Service & life‑of‑field economics: Growing activity in intervention, workover and abandonment creates recurring service revenues for specialized intervention providers. For oil companies, the economics of extending field life via targeted interventions increasingly outruns the spend required for new wells in many offshore basins.
Competitive landscape — who matters and why
The market is led by established global oilfield service and equipment firms with broad subsea portfolios. Our report includes a forensic competitive benchmarking of OEMs and service providers, examining capabilities across manufacturing scale, R&D intensity, service footprint, and commercial model flexibility.
-
Baker Hughes Company (Houston): Strong in IWOCS (Installation and Workover Control Systems) and subsea pressure control. Their advantage is integrated systems engineering for deepwater programs and a global service infrastructure that reduces mobilization risk.
-
SLB (Schlumberger Limited) (Houston): Offers end‑to‑end subsea pressure control and downhole intervention tools. Recent large‑scale completions contracts in ultra‑deepwater illustrate SLB’s ability to bundle technology with long‑term field support; its scale supports advanced interval control deployment for complex reservoirs.
-
Aker Solutions (Fornebu): Differentiates on integrated subsea production systems and combined well access/workover packages—appealing to operators seeking single‑vendor subsea delivery to simplify project risk.
-
TechnipFMC (Newcastle/Houston): Competes on integrated tree and intervention systems, with a strong project execution track record on large offshore developments.
-
NOV Inc. (Houston): A key equipment manufacturer focused on high‑pressure ram BOPs and subsea drilling technologies—strength lies in mechanical reliability and manufacturing throughput.
-
Halliburton, Weatherford, Dril‑Quip, Oceaneering, Expro, Proserv, Helix : These players populate niches across intervention services, valve technologies, and intervention vessels. Several have strengthened portfolios through targeted product launches or strategic agreements.
Recent market moves validate the tactical directions we recommend. A new single high‑debris shear‑and‑seal ball valve launched in early 2026 consolidates functionality to reduce complexity and failure exposure—an example of product innovation that can materially reduce intervention risk. Major contract awards for ultra‑deepwater completions and exclusive supply agreements between subsystem suppliers and OneSubsea highlight the industry’s tilt toward long‑term, integrated supply relationships.
What the PW Consulting report contains — practical deliverables
The study is purpose‑built for executives who must make near‑term commitments with multi‑year ramifications. Deliverables include:
-
Top‑down and bottom‑up market models with sensitivity analyses and three scenario paths (base, upside with accelerated deepwater activity, and downside with commodity stress).
-
Vendor scorecards assessing performance across manufacturing capacity, product certification readiness, aftermarket service coverage, and technology roadmaps.
-
Procurement playbooks and contract templates that address supplier lead‑time guarantees, material substitution clauses for alloy shortages, and regulatory compliance milestones tied to payments.
-
Capex vs. opex decision matrices for operators comparing full asset replacement, life‑extension interventions, and shared‑asset service models.
-
Risk registers and mitigation playbooks covering regulatory certification timelines, supply‑chain single‑point risks, and logistics for frontier basin operations.
-
Executive dashboards: succinct KPIs for portfolio managers (delivery performance, spare parts fill rate, intervention success rates, and warranty exposure).
Strategic recommendations for 2026 planning
-
Prioritize certification and materials readiness: If your 2026 program targets high‑pressure or sour service environments, fast‑track API and NACE‑aligned qualification paths and secure alloy supply commitments now to avoid 12–24 month delivery slippage.
-
Adjust commercial models toward outcome orientation: Operators should consider outcome‑based contracts with uptime and intervention success SLAs. Suppliers should price modular, serviceable systems that lower life‑cycle cost and increase aftermarket revenue.
-
Invest selectively in 20,000 psi capability: The development of extreme‑pressure equipment opens high‑margin frontier opportunities—but requires concentrated R&D and testing investment. Evaluate partnerships or acquisition of niche tech providers versus greenfield development.
-
Strengthen intervention options: Riserless and lower‑vessel‑dependence intervention technologies are becoming differentiators for operators seeking flexible well intervention windows and lower mobilization costs.
-
Prepare for consolidation or specialization: Given the market concentration dynamics, mid‑tier players should either pursue scale through M&A or double down on specialized product and service niches where technical differentiation yields premium margins.
Risk checklist for boardrooms
-
Certification timelines: Map API/NACE qualification milestones against project gating schedules and trigger contract remedies if suppliers miss key dates.
-
Alloy availability: Validate multi‑tier sourcing and consider inventory hedging for critical alloy inputs.
-
Regulatory shifts: Monitor jurisdictional changes that can alter intervention requirements or component approvals; build scenario triggers into project governance.
-
Technological obsolescence: Include upgrade pathways and retrofit clauses in long‑term supplier agreements to protect against rapid obsolescence of key subsea components.
Conclusion — how to use this intelligence in 2026
For 2026, executives must balance the dual imperatives of capability readiness (materials, certification, engineering) and commercial agility (contract design, service models and partnerships). The subsea well access and BOP landscape is expanding at a steady mid‑single‑digit CAGR and remains concentrated among a few large suppliers, creating windows for both scale players and technically differentiated specialists. PW Consulting’s study provides the operational templates, supplier evaluation tools, and scenario analyses you need to translate market growth into durable returns while managing certification, materials and execution risk.
To access the full dataset, vendor scorecards and the actionable procurement playbook that underpin these conclusions, consult the complete report on our website—equipped with downloadable executive dashboards and customizable scenario models to support your 2026 planning cycle.
For detailed analysis of this topic, please visit the official page: Worldwide Subsea Well Access And BOP System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com