

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Narrow-Body Aircraft MRO Market Poised for 5.6% CAGR Through 2032

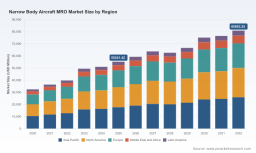
PW Consulting: Strategic Outlook — Worldwide Narrow-Body Aircraft MRO Market (Base Year 2025) — A Decision-Grade Briefing for 2026
PW Consulting today releases an executive briefing accompanying our full market study, Worldwide Narrow Body Aircraft MRO Market. The briefing synthesizes the study’s strategic implications for industry leaders, investors, and operators making binding decisions in 2026. Our analysis shows the global narrow-body MRO market recovering and expanding from a post‑pandemic base — with the market valued at approximately USD 55.2 billion in 2025 and projected to grow at a 5.6% CAGR through the 2026–2032 forecast window, reaching roughly USD 80.9 billion by 2032. This trajectory underscores material opportunity — and material execution risk — for stakeholders across the aftermarket value chain.
Worldwide CRM and Customer Experience Implementation Services Market
Why this report matters now
-
Timing pressure: Fleet deployments and OEM delivery ramps in 2026 force hard capital and capacity decisions today. Facilities, licensed capabilities and long-lead spare contracts require commitments measured in quarters, not months.
Barcode Scanner Batteries Market -
Margin leverage: Rising labor and materials costs compress repair margins unless operations and commercial terms are proactively re‑engineered. Our study quantifies the margin sensitivity to cost inflation in scenarios relevant to narrow‑body platforms.
Disposable Hospital Curtain Market -
Competitive inflection: Market concentration metrics indicate that incumbents retain meaningful share but do not preclude aggressive entrants or capacity-driven regional shifts. The top-three MRO providers account for roughly 31.4% of market throughput, while the top-five represent about 42.9%, creating both competitive clustering and white‑space pockets for specialised plays.
-
Regulatory and certification gatekeepers: Engine platform licensing — notably for the LEAP family — is a determinative capability that reshapes capability economics, shop utilization and OEM/MRO commercial relationships.
What the full report delivers (practical, non‑generic tools)
-
Demand and capacity scenarios: Three operational scenarios (Constrained Supply, Balanced Growth, and Capacity Overflow) model shop utilization by aircraft vintage and engine family through 2032, enabling capital timing and lease-versus‑build arbitration.
-
Executable commercial playbooks: Contract archetypes and negotiation levers for airlines, lessors and independent providers — including guaranteed-availability structures, risk‑sharing frameworks, and inventory consignment clauses tailored to narrow‑body flows.
-
Cost-to-serve matrix and profitability model: A playable spreadsheet model that isolates labor, material, overhead and logistics drivers for narrow‑body shop visits; parametrised for regional wage inflation and material shocks so teams can stress-test pricing.
-
Supply chain resilience toolkit: Risk heatmaps for critical spares, second‑tier suppliers and lead‑time exposure, alongside a prioritised action list for alternative sourcing, strategic stocking and vendor qualification.
-
Workforce and skills roadmap: A three‑phase talent plan to close certified mechanic gaps — recruitment, upskilling partnerships, and productivity levers — with projected ROI under varied wage inflation paths.
-
Deal and M&A screening templates: Quick‑score checklists and valuation sensitivities for bolt‑on acquisitions, capability buys (e.g., engine shop certifications) and JV structures that accelerate market entry.
-
Benchmarking database: Operational and commercial KPIs for leading narrow‑body MRO facilities — utilization, turnaround times, shop‑visit mix and select unit cost indices — structured to support target-setting without disclosing client‑level confidentiality.
Market dynamics shaping 2026 decisions
-
Recurring demand dominance: Narrow‑body fleets remain the engine of global short‑haul travel and therefore of recurring MRO volume. This creates predictable baseline demand but also concentrates exposure to single‑platform shocks and delivery cadence shifts.
-
Labor and material inflation are real and quantifiable: Industry surveys indicate skilled labor shortages persist, with wage inflation near 6.6% in 2024 and projected around 5.7% in 2025; material costs surged about 7.7% in 2024 with a continued elevated trajectory into 2025. These inputs materially affect shop economics and must be incorporated into 2026 contracting and capex plans.
-
Supply chain friction: Parts availability and production delays continue to extend turnaround times and reduce throughput. Our models show that even moderate elongation of critical lead times can reduce effective shop capacity and materially increase working capital needs.
-
Certification as a strategic moat: Specialized licensing and technical capability for prime narrow‑body engine families — notably the LEAP series used on current neo/MAX platforms — are differentiators. Providers that obtain or expand “Premier” capability capture higher‑value shop visits and ancillary revenue.
Competitive landscape: who’s shaping the market
-
Lufthansa Technik — A broad capability set across base and line maintenance, engine overhaul and platform modifications, supported by a global footprint and large dedicated narrow‑body facilities. Their multi‑site capacity and OEM relationships make them the reference integrator for airline and lessor partners.
-
ST Engineering Aerospace — The largest independent airframe MRO by man‑hours, with aggressive capacity expansion in engine MRO. Their recent facility investments are designed to capture incremental CFM56 and LEAP demand in Asia‑Pacific and beyond.
-
AAR Corp. — A North American independent with targeted narrow‑body capabilities and capacity expansion in strategic hubs. Their playbook blends landing‑gear, component and airframe specialization to win regional airline business.
-
Delta TechOps — An airline‑affiliated powerhouse with unique licensed capability for both LEAP variants in North America, giving it a durable competitive advantage for carrier and third‑party shop visits on neo and MAX platforms.
-
SR Technics — Focused engine heavy shop visits and component MRO with recent multi‑year agreements that demonstrate the persistent opportunity in legacy narrow‑body engine support.
-
HAECO, Turkish Technic, Iberia Maintenance, TAP Maintenance & Engineering — Regional leaders with capacity and contract wins that make them pivotal partners for operators in their respective theatres, often leveraging airline affiliations or airport privileges to secure flow‑through business.
Recent commercial moves underscore the market’s directional signals: expanded LEAP capability among airline MROs, multi‑year engine support deals, and greenfield capacity openings targeted at doubling shop throughput for high‑volume narrow‑body engine platforms. These are not isolated events — they are coordinated strategic bets that change the competitive map for serviceables and capacity allocation through 2027.
Strategic imperatives for 2026 (what to do next)
-
Prioritise capability, not just capacity. Where licensing (e.g., LEAP) provides revenue uplift and margin protection, accelerate certification and vendor relationships rather than incremental hangar additions alone.
-
Hedge material risk via dual‑sourcing and targeted inventory. Short-term working capital for key rotables reduces disruption risk and can be priced into service agreements to protect margins.
-
Revisit commercial models: transition from transactional shop‑visits toward outcome‑linked contracts (availability, reliability) to capture higher lifetime value from airline partners.
-
Invest in predictive maintenance and digital workflows to recover turnaround time and improve shop throughput; the ROI is compelling when staged against current wage and material inflation scenarios.
-
Adopt selective partnerships or bolt‑on M&A to access certifications and customer funnels quickly; internal build options are long and capital‑intensive.
-
Embed scenario planning in capital approvals: require stress‑tested utilization curves and sensitivity to 10–20% shifts in lead times and labor cost trajectories.
How PW Consulting supports executable decisions
-
Tailored workshops that run your commercial, operations and finance teams through the report’s scenario models and the provided cost‑to‑serve toolset.
-
Benchmarking and confidential peer comparisons to validate your shop economics against the market without exposing proprietary client data.
-
Deal advisory for JV formations, capacity investments and acquisition screening, using our forecast model to stress test valuations under multiple macro environments.
-
Implementation support for capability upgrades—project scoping for certification pathways, capex phasing, and workforce plans aligned to delivery timelines.
Our study provides both the strategic perspective and the tactical instruments that management teams need to move from analysis to action in 2026. For those who want the complete intelligence — including the full, granular breakdowns by region, activity and aircraft generation, the proprietary scenario files, and the benchmarking datasets referenced here — download the full report or contact PW Consulting for a personalized briefing. The headline numbers and directional drivers presented in this briefing only scratch the surface; the full deliverable is designed for immediate operationalisation.
Contact PW Consulting to schedule a 2026 strategy session and to obtain the comprehensive dataset and model licenses that will allow your team to translate forecast into competitive advantage.
For detailed analysis of this topic, please visit the official page: Worldwide Narrow Body Aircraft MRO Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com