

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Industrial Epoxy Glass Market to Expand from USD 2,842.6 Million in 2025 to USD 4,218.9 Million by 2032 at a 5.82% CAGR — FR‑4, Asia Pacific and Electrical & Electronics Lead Growth

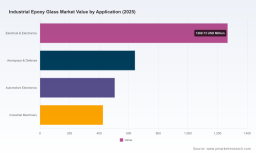
Worldwide Industrial Epoxy Glass Market — Strategic Briefing for 2026 Decision-Makers
PW Consulting’s latest market study on the Worldwide Industrial Epoxy Glass Market provides a focused, execution-oriented view designed specifically to support corporate planning and investment decisions in 2026. The industry is transitioning from steady recovery into differentiated growth: the overall market expands from a 2025 base of USD 2,842.6 Million into a structurally larger market in 2026 (projected USD 3,008.6 Million), with a compound annual growth rate (CAGR) of 5.82% through our 2026–2032 forecast window. This briefing highlights the practical implications of those trends for sourcing, product strategy, capacity planning, and M&A — while intentionally reserving detailed segment-level figures for the full report.
Worldwide Mobile Event Apps Market
What the report delivers — practical content for 2026 action plans
- Validated market sizing and top‑line forecasts (base year 2025; forecast period 2026–2032), with scenario stress‑testing to quantify upside and downside cases relevant to 2026 planning cycles.
- Demand‑driver analysis linking end‑market dynamics (electrical & electronics, aerospace & defense, automotive electronics, industrial machinery) to product-level requirements and margin pools.
- Upstream cost mapping and sensitivity models that show how epoxy resin price moves transmit to finished goods costs and gross margin under alternative sourcing and hedging strategies.
- Supply‑side diagnostic: capacity maps, utilization analysis, logistics choke points, and supplier scorecards for supplier consolidation or dual‑sourcing decisions.
- Competitive benchmarking and playbooks (pricing, certification, product differentiation, channel and service models) focused on near‑term execution and 12–24 month outcomes.
- M&A and partnership framework including target screening criteria, valuation multiples observed in recent transactions, and integration checklists for quick wins post‑close.
- Operational toolkits — Excel-ready models, supplier heatmaps, procurement negotiation scripts, and an executive dashboard for board‑level reporting.
Key macro and market dynamics that will shape 2026 choices
- Resilient top‑line growth but margin pressure points: the market’s mid‑single digit CAGR masks important upstream volatility — in 2026 epoxy resin price dynamics will remain a primary cost driver. Recent data points highlight regional price differentials (e.g., Northeast Asia epoxy resin quoted at approximately USD 2.62/kg in April 2026, and China pricing reported near USD 2,031/MT earlier in 2026). These swings materially affect unit economics for G‑10/FR‑4 producers and necessitate active procurement hedging or pass‑through mechanisms.
- Certification and compliance are baseline requirements: leading suppliers maintain UL 94 V‑0 flame retardancy and RoHS/REACH compliance as standard. For OEMs targeting regulated verticals (aerospace, defense, critical industrial applications), certification investments and traceability are non‑negotiable and materially affect supplier selection and time‑to‑market.
- Product innovation is bifurcating the value chain: new resin formulations and specialty prepregs (for example, next‑generation flame‑retardant clear epoxy prepregs introduced in 2026) are enabling premium product segments — particularly where visual aesthetics, flame performance and high‑reliability electrical properties converge. These niches command differentiated pricing and longer purchase cycles tied to qualification time.
- Capacity shifts and regional supply strategies: reported capacity expansions among large integrated producers signal continued consolidation of high‑volume supply, while many regional players focus on short lead-time and customized forms (rods, tubes, machined parts). The competitive footprint therefore supports both global scale players and nimble local specialists.
Competitive landscape — strategic positioning and implications
The sector shows a concentrated‑but‑fragmented structure: the top three suppliers account for roughly one‑third of market share, and the top five approach half the market — a profile that creates both competitive intensity and opportunities for mid‑market consolidation. Key competitors and the strategic implications for 2026 are summarized below.
Worldwide Creatine Citrate Market
- Ventec International Group (Taiwan) : Global leader in high‑performance copper clad laminates and prepregs. Strengths include deep technical capability in PCB substrates and a proven qualification pipeline for high‑reliability customers. For 2026, Ventec’s playbook centers on technology licensing, long‑cycle qualification wins in telecom and advanced PCB manufacturers, and selective capacity allocation to premium grades.
- Isola Group (United States) : Differentiated by broad copper‑clad laminate and prepreg portfolio, and strong relationships with demanding PCB OEMs. Isola’s positioning favors long‑term contractual relationships and co‑development; they are a logical partner for OEMs seeking integrated supply with design support services.
- Atlas Fibre, Franklin Fibre‑Lamitex, Current Inc., Iten Industries (United States) : These North American specialists offer depth in G‑10/FR‑4/G‑11 sheets, rods, tubes and machined components. Their strategic advantage is service responsiveness and MIL/NEMA compliance capabilities — attractive to defense and heavy industrial customers requiring short lead times and domestic sourcing.
- Hexcel Corporation & Park Aerospace (United States) : While better known for advanced composites in aerospace, these firms’ glass‑reinforced epoxy systems provide cross‑industry technology transfer — elevating performance expectations (e.g., thermal stability, weight optimization) and accelerating premium segment growth.
- SIDA (China JV group) & Hony Engineering Plastics (China) : Large‑scale manufacturers focused on high‑volume FR‑4 and related grades. Reported capacity expansions and catalog updates by these players increase competitive supply in both domestic and export markets. Their scale supports aggressive pricing tactics but also exposes them to upstream feedstock swings and regional policy shifts.
Five strategic playbooks for executives in 2026
- Insulate margins from resin volatility: establish blended sourcing, index‑linked contracts with suppliers, and a tactical inventory hedge program. Our sensitivity models quantify breakpoints where pass‑throughs become necessary versus when to absorb costs for strategic share retention.
- Prioritize qualification pipelines: invest selectively in certifying premium epoxy glass grades and flame‑retardant prepregs for high‑value end markets. Time‑to‑qualification will determine 2026 revenue capture in aerospace, defense and advanced electronics segments.
- Adopt a dual supply strategy: combine global scale partners for commodity volumes with regional specialists for rapid turnaround and custom fabrication. This hybrid reduces TCO and shortens NPI cycles for customer‑specific components.
- Differentiate with value services: expand offering beyond commodity sheets to include in‑house machining, assembly services, and material traceability packages. Service differentiation reduces price sensitivity and raises switching costs.
- Targeted M&A/joint ventures: pursue tuck‑ins that add fabrication capability, certification credentials or complementary resin technology rather than broad horizontal consolidation. Our target screening framework prioritizes accretive deals that deliver immediate synergies and protect against upstream shocks.
How PW Consulting’s report accelerates 2026 execution
This study is designed as a decision‑support pack rather than a descriptive white paper. Executives receive:
Worldwide LIMS Software Market
- Ready‑to‑use financial models and price‑sensitivity dashboards that integrate epoxy resin price scenarios and supplier contract structures.
- Supplier heatmaps and capability matrices to inform near‑term sourcing awards and 12‑month contingency plans.
- M&A playbooks and integration checklists that reduce execution risk and speed commercial capture post‑transaction.
- Go‑to‑market roadmaps with prioritized 90/180/360 day actions for product qualification, channel deployment, and regulatory alignment.
Concluding perspective
For 2026, the industrial epoxy glass market presents a clear task for executives: convert steady top‑line growth into durable margin expansion through disciplined feedstock risk management, accelerated product qualification in premium niches, and pragmatic supply‑chain design. The market’s aggregated growth profile (with a projected step‑up from the 2025 base into 2026 and a mid‑to‑high single‑digit trajectory through 2032) rewards early strategic moves that shorten qualification timelines, secure feedstock economics, and align capacity with differentiated product portfolios.
PW Consulting’s full Worldwide Industrial Epoxy Glass Market report contains the complete segmentation, supplier-level scorecards, and the detailed datasets required to operationalize these strategies. For executives building 2026 playbooks, the report provides the empirical backbone and practical toolkits to move from planning to decisive action.
For detailed analysis of this topic, please visit the official page: Worldwide Industrial Epoxy Glass Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com