

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Predicts Worldwide Laboratory Glass Container Market to Grow at a 5.42% CAGR During 2026–2032

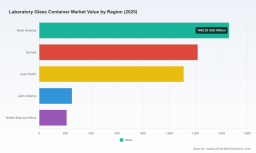
Worldwide Laboratory Glass Container Market 2026: Strategic Imperatives for Corporate Decision‑Makers
PW Consulting today releases the executive preview of its forthcoming Worldwide Laboratory Glass Container Market report (base year 2025; forecast period 2026–2032). The global market for laboratory glass containers—used across pharmaceutical, biotechnology, academic research, clinical diagnostics, and industrial laboratories—was estimated at USD 4,255.5 Million in 2025 and is projected to expand to approximately USD 6,157.6 Million by 2032, growing at a compound annual growth rate (CAGR) of 5.42% across the forecast horizon. This preview outlines the strategic value of the full study for corporate planning in 2026 while intentionally withholding core segment-level tables and channelized figures to encourage direct engagement with the full report for actionable detail.
Worldwide Plating Bath Analysis Services Market
Why this market matters for 2026 planning
-
Demand resilience and quality premiumization: Laboratory glassware remains indispensable where chemical resistance and thermal stability are mission‑critical. The market’s steady mid-single-digit CAGR reflects enduring demand from regulated end markets even as consumable substitution and plastics adoption create pockets of competitive pressure.
Algo Trading Software Market -
Raw material and input cost dynamics: Borosilicate glass—the material of choice for high‑performance laboratory containers—faces upward cost pressure driven by rising boron compound prices and supply constraints. These dynamics are already influencing manufacturers’ cost structures and margin planning for 2026.
Worldwide ODM Smartphones Market -
Competitive concentration and consolidation signals: The market exhibits moderate concentration among top players, with the three largest firms accounting for a material share and the top five aggregating a clear majority of established premium capacity. This structure creates both defensive imperatives for incumbents and opportunities for well‑capitalized challengers to gain share through targeted M&A and capability investments.
What leaders need from this report in 2026
-
Portfolio prioritization: The full report provides a decision framework for prioritizing product lines (e.g., volumetric ware, sample vials, cell culture systems) against margin profiles, regulatory risk, and capital intensity. Executives can use our playbooks to rationalize SKUs, accelerate high‑value SKUs, or sunset non‑strategic items while protecting customer retention metrics.
-
Supply‑chain resilience planning: Our scenario modelling quantifies the potential P&L impact of boron price volatility and kiln capacity disruptions. The study includes mitigation tactics—strategic raw material contracting, backward integration feasibility checks, and alternative material pathways—tailored to different company archetypes.
-
Go‑to‑market and channel moves: For manufacturers and distributors, the report synthesizes channel dynamics—direct sales, distributors, and e‑commerce—offering playbooks for optimizing distribution agreements, negotiating margin levers, and executing targeted field sales initiatives in priority end markets.
-
M&A and inorganic growth mapping: We present a vetted pipeline of acquisition archetypes and integration risk matrices to help buyers and sellers calibrate valuations in a market where strategic assets (specialty borosilicate lines, pharmaceutical primary packaging capabilities, or global distribution networks) command premiums.
Practical contents and tools included in the full PW Consulting study
-
Market sizing and seven‑year scenarios: Bottom‑up and top‑down sizing with downside and upside cases—useful for stress testing revenue plans under alternative macro and commodity scenarios.
-
Competitive benchmarking: Proprietary supplier scorecards across manufacturing footprint, product breadth, regulatory certifications, and time‑to‑market. These are accompanied by actionable supplier development plans and KPIs to accelerate improvement cycles.
-
Segment playbooks: For each product family and end‑use cohort, we provide value‑chain economics, margin waterfall modelling, and recommended commercial tactics—without disclosing sensitive breakouts in this preview.
-
Procurement negotiation templates: Practical contract clauses for long‑lead raw materials, indexing recommendations for variable cost elements, and sample hedging strategies tailored to glass production timelines.
-
CapEx decision support: Payback modelling and capacity utilisation scenarios for greenfield and brownfield investments, including a decision matrix for conversion versus new build when expanding borosilicate production lines.
-
Regulatory and compliance mapping: Global regulatory touchpoints for pharmaceutical primary packaging and sterile containers, with a checklist for qualification, stability testing requirements, and audit readiness for 2026 inspections.
Competitive landscape: what the leaders and challengers are doing
Our analysis of key players shows a marketplace where legacy brands, engineering innovators, regional specialists, and integrated pharma suppliers each play distinct strategic roles. Top multinational glassmakers continue to defend premium positions with strong brand equity and global manufacturing footprints. Specialist firms—often family‑owned or regionally concentrated—leverage agility and deep customer relationships to serve bespoke laboratory and pilot production needs.
-
Legacy premium manufacturers: Longstanding brands known for high thermal and chemical resistance maintain pricing power in regulated applications. Their investments in process control, quality systems, and validated packaging solutions make them default partners for large pharmaceutical clients.
-
European precision producers: Firms with origins in volumetric and high‑precision glassware are extending into pharmaceutical and analytical vials, often via technology tie‑ups or product diversification strategies.
-
Indian and regional industrial players: Cost‑competitive manufacturers from South Asia and Eastern Europe have expanded capabilities, in some cases moving up the value chain through acquisitions or partnerships to offer broader portfolios and localized supply benefits.
-
Distributors and channel consolidators: Distribution agreements and expanded network reach remain an important avenue for market access. Recent distribution moves demonstrate how partnership reconfiguration can rapidly alter go‑to‑market dynamics in important national markets.
Two recent developments captured in our mapping illustrate these forces at work. First, a notable industrial player executed a strategic shift from a pure glassware manufacturer into adjacent analytical vials, filtration, and primary pharma packaging through targeted acquisitions—reflecting an industry impulse toward portfolio diversification and vertical adjacency. Second, a life‑science equipment supplier expanded its distribution footprint with major laboratory channel partners to increase reach for consumables and small instrumentation—underscoring the importance of channel partnerships in accelerating market access.
Strategic implications for five types of market participants
-
Global manufacturers: Prioritize hardened relationships with pharmaceutical customers, invest selectively in validated packaging capacity, and consider bolt‑on acquisitions that provide regulatory dossiers and qualification histories.
-
Regional producers: Accelerate upward migration to higher‑margin specialty products, invest in quality systems that meet pharma clientele expectations, and build distribution alliances to scale beyond domestic markets.
-
Distributors: Reassess exclusive agreements and hybrid distribution models that combine inventory pooling with vendor‑managed inventory to protect fill‑rates amid supplier cost pressure.
-
Private equity and strategic acquirers: Use our valuation matrices and integration playbooks to identify targets where manufacturing scale, technology differentiation, or distribution footprint unlock rapid synergies.
-
Procurement organizations: Apply our commodity stress tests and contract templates to renegotiate supplier terms, implement indexed pricing clauses, and explore dual‑sourcing for critical borosilicate inputs.
Risk factors and mitigation
-
Commodity inflation: Boron cost escalation and energy price volatility are the most immediate input risks. Mitigation includes long‑term supply contracts, formula‑based pricing, and selective vertical integration evaluation.
-
Substitution risk: Plastics and engineered polymers are encroaching in non‑critical applications. Manufacturers should sharpen value propositions around thermal/chemical performance and invest in marketing that translates technical superiority into purchasing decisions.
-
Regulatory and qualification hurdles: Pharmaceutical customers require validated supply chains and documentation. Investment in compliance infrastructure is non‑negotiable for suppliers targeting high‑growth regulated segments.
-
Capacity and lead times: Furnace and annealing capacity constraints can create bottlenecks. Our capacity planning templates help quantify capex lead times versus expected demand ramps.
Methodology and data confidence
PW Consulting’s full report synthesizes primary interviews with C‑level executives, procurement heads, and plant managers across the value chain, supplemented by trade data, customs flows, and factory‑level cost modelling. We triangulate demand forecasts with end‑market drivers—pharma R&D spending, diagnostic testing volumes, and laboratory infrastructure investments—producing a market view grounded in transactional reality and stress‑tested under multiple macro scenarios.
How to use this preview
This preview is designed as a strategic trailer: it demonstrates analytical depth and provides enough directional insight to inform early 2026 planning but deliberately withholds detailed segment figures, regional splits, and proprietary benchmarking that appear in the full report. For planners needing the decisive, quantified inputs for budgeting, M&A underwriting, and procurement renegotiation, the full report contains downloadable models, supplier scorecards, and CapEx templates.
Next steps
-
For access to the complete Worldwide Laboratory Glass Container Market report, including all segment tables, interactive models, and supplier scorecards, contact PW Consulting or visit our reports portal.
-
PW Consulting is offering a limited series of 60‑minute strategy briefings for clients who purchase the full study before Q3 2026. These sessions include bespoke scenario modelling applied to your company’s portfolio.
PW Consulting remains committed to equipping executive teams with field‑tested frameworks and practical tools to turn market insight into competitive advantage. The laboratory glass container market may look stable at the headline level, but beneath the surface, commodity tides, channel shifts, and targeted consolidation activity will determine winners and laggards in 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Worldwide Laboratory Glass Container Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com