

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Smart Ticketing Market to More Than Double — from USD 18.25B in 2025 to USD 41.24B by 2032 at a 12.35% CAGR

Worldwide Smart Ticketing Market — Strategic Briefing for 2026 Decision-Makers
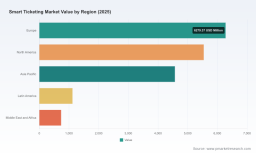
PW Consulting’s latest market study, Worldwide Smart Ticketing Market (base year 2025), provides a rigorous, execution-focused view of an industry undergoing rapid platformization and regulatory harmonization. The global market reached an estimated USD 18,250 Million in 2025 and — under our core forecast — is projected to grow at a compound annual growth rate (CAGR) of 12.35% through the 2026–2032 horizon. By 2032 the sector is expected to materially expand from today’s scale, driven by accelerating adoption of account-based ticketing, wallet-native transit experiences, and contactless EMV acceptance across major networks.
Worldwide Mechanical Booster Pumps Market
Why this report matters for 2026 strategy
- Timing and regulation are converging. National and supranational mandates for interoperability, together with updated payment-security requirements, create both compliance obligations and competitive opportunity windows that will crystallize in 2026.
- Platform decisions have long tails. Choices made in 2026 — around account-based architecture, credentialing standards, and wallet integrations — will define cost of ownership and competitive positioning for a decade.
- Capital allocation must be evidence-based. With the market expanding briskly, operators and investors need scenario-tested capex/opex models and vendor-selection frameworks to prioritize spend where it accelerates ridership, revenue, or operating efficiency.
High-level market dynamics (what is driving growth)
- Technical convergence: Mobile-first ticketing, NFC contactless credentials, QR-based validation, and bank-card acceptance are moving toward unified customer journeys. The interplay between credential vendors, semiconductor suppliers and software platforms is reshaping procurement requirements.
- Regulatory catalysts: Recent mandates for open standards and cross-border interoperability are shortening procurement cycles for compliant systems and increasing the premium for vendors that can prove standards alignment and data portability. Separately, payment security rules (including PCI DSS v4.0) are raising the bar for systems that process cardholder data.
- Deployment economics: Infrastructure costs vary by technology and deployment model; for example, urban NFC reader installations typically present a defined per-unit investment that operators must weigh against the benefits of reduced friction and the operational simplicity of account-based backends.
- Consolidation and specialization: Market concentration metrics indicate a sector that is neither monocultural nor fragmented: leading platforms capture meaningful share, but specialists remain crucial for integration, credential manufacture, and IC supply.
What PW Consulting’s report delivers — operationally usable content
This study is designed for executives who must convert insight into action in 2026. The report blends granular scenario modeling with practical deliverables that procurement teams, CIOs, and strategy groups can use immediately:
Worldwide Enterprise Mobility Management Software Market
- Top-down and bottom-up market sizing and a validateable forecast model (2026–2032) that supports stress-testing under alternative adoption, price and regulatory scenarios.
- Decision playbooks for choosing between account-based and card-centric architectures, including a vendor-agnostic checklist to assess interoperability, scalability, and data ownership.
- Total Cost of Ownership (TCO) templates that combine capital, operating, and lifecycle upgrade costs across typical rollout phasing — with sensitivity levers you can plug into your own financial models.
- Procurement-ready artifacts (RFP language snippets, SLA clauses, and scoring matrices) that embed standards compliance, cyber controls, and migration milestones so clients can shorten bid cycles and reduce legal friction.
- Implementation playbooks and risk registers for real-world rollouts (pilot design, fare migration, customer communication, validator retrofits), including escalation paths for payment incidents and interoperability disputes.
- Regulatory compliance roadmap that maps major mandates and payment-security requirements to concrete program milestones for 2026 implementation windows.
- Vendor shortlists and assessment frameworks built from public deployments, product capability, partner ecosystems and proven migration track records — intended to accelerate vendor selection without sacrificing rigor.
Competitive landscape — interpreting the players and recent moves
The marketplace is driven by a combination of platform providers, credential and hardware suppliers, and systems integrators. PW Consulting’s competitive diagnostic highlights capability clusters, recent strategic moves through 2025–2026, and implications for procurement and partnership strategies.
Worldwide Oil & Gas Processing Seals Market
- Platform and account-based specialists. Firms such as Masabi and Cubic have been leading customer-facing innovations: Masabi’s integration with wallet providers to enable tap-to-ride on consumer devices and Cubic’s evolution of multimodal platforms underscore a push toward seamless, app-native experiences. Expect wallet integrations and native platform capabilities to be differentiators in 2026 procurements.
- Mobility-as-a-Service aggregators. Mobility app providers — exemplified by Moovit — are translating app adoption into broader ticketing footprints by embedding account-based ticketing across city networks, expanding reach and lowering friction for operators that partner rather than build.
- Credential and semiconductor ecosystem. Suppliers like HID Global and NXP Semiconductors remain essential to the fabric of mass deployments: credential issuance, secure element design and card IC availability determine the feasibility and cost of large-scale rollouts. Their roadmaps influence migration timelines for legacy card programs.
- Systems integrators and integrative platform vendors. Thales and other major integrators provide end-to-end deployments that include contactless EMV and bank-card acceptance; these capabilities are increasingly important as networks look to simplify payment acceptance and reduce dependence on closed-loop credentialing.
- Regional and specialist operators. Established regional players and fare-collection specialists continue to support complex local requirements and airport or stadium deployments where integration complexity is high.
Recent strategic developments — such as wallet integrations, account-based expansion in new municipalities, and upgraded contactless EMV deployments — are not isolated innovations. They reflect three parallel trends: customer-experience centralization, payments-layer disruption, and standards-driven interoperability. Each trend has procurement and architecture consequences that our assessment explores in depth.
Strategic recommendations for decision-makers in 2026
- Prioritize pilot-to-scale pathways. Run bounded account-based pilots that validate back-office settlement, fare-capping rules, and revenue assurance before committing to network-wide rollouts.
- Embed interoperability in contracts. Require open-standards conformance, data portability clauses and staged exit provisions to reduce lock-in and enforce competitive maintenance of core interfaces.
- Make security a sourcing criterion. Treat PCI DSS v4.0 readiness and credential lifecycle management as pass/fail items during shortlisting; remediation costs for non-compliant systems are material and time-sensitive.
- Budget for hybrid infrastructure. Expect to operate mixed fleets of validators and credentials during migration; model capex and operating impacts across staged decommissions. Infrastructure unit costs should be quantified and stress-tested against adoption speed.
- Negotiate ecosystem partnerships. Whether working with wallet providers, semiconductor vendors, or MaaS aggregators, secure partnership terms that include roadmap alignment and joint go-to-market commitments.
- Adopt modular procurement approaches. Break projects into composable phases (core account engine, validation layer, customer channels) to preserve optionality and accelerate value capture.
How to use the full report
PW Consulting’s study is structured to support short-cycle executive decisions and detailed technical procurement workstreams. Use the report to:
- Calibrate strategic plans with our scenario-tested market forecast and elasticity assumptions;
- Extract RFP language and TCO templates directly into procurement processes;
- Shortlist vendors using our validated capability matrices and recent-deal tracking; and
- Operationalize migration pathways with the included playbooks and risk mitigations.
For teams preparing capital plans and procurement timelines for 2026, the report provides both the analytical backbone and the practical toolset necessary to convert market opportunity into measurable outcomes. To access the full datasets, vendor matrices, and the interactive forecast model — including the granular segmentation and scenario tables that support the executive summaries above — please visit the PW Consulting report page for Worldwide Smart Ticketing Market.
PW Consulting — Strategic intelligence for transit, payment and mobility leaders.
For detailed analysis of this topic, please visit the official page: Worldwide Smart Ticketing Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com