

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Chinese Domestic Databases Market to Expand at 18.5% CAGR Through 2032, Forcing Rethink of On‑Premise vs Cloud Strategies

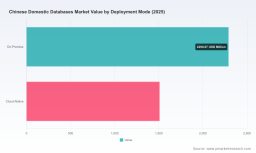
PW Consulting Strategic Brief: Preview of the Worldwide Chinese Domestic Databases Market Report (Base Year 2025)
As senior strategic advisors and the lead industry analysts at PW Consulting, we present a high-level preview of our newest market intelligence product: the Worldwide Chinese Domestic Databases Market report. This briefing outlines why the report will be essential for enterprise and public-sector decision-makers shaping database, cloud, and data-governance investments in 2026. It highlights macro market dynamics, competitive positioning, regulatory drivers and the practical, execution-oriented content clients will find in the full study—while intentionally withholding the granular segment tables and proprietary model outputs that are available only in the full report.
Worldwide BBQ Wood Pellets Market
Why this market matters for 2026 strategy
The domestic Chinese database ecosystem has moved well beyond niche substitution to become a strategic pillar for organizations operating in or with China. Underpinning that shift is a period of sustained growth: since 2020 the market has expanded markedly to reach a base-year size of USD 3.8 billion (revenues reported in Million USD for 2025), and our forecast horizon (2026–2032) projects continued rapid expansion at a compound annual growth rate (CAGR) of 18.5%. By 2032 the market is expected to be an order of magnitude larger than five years prior, reflecting accelerated cloud adoption, large-scale digital transformation in regulated sectors, and targeted public policy incentives.
Worldwide Managed Content as a Service (MCaaS) Market
For boards, CIOs, and procurement leaders, this combination of scale, growth velocity and policy-driven adoption creates both opportunity and complexity. The questions that will dominate boardroom agendas in 2026 are operational rather than academic: Which database architectures minimize compliance and migration risk? How to select vendors that balance cloud maturity, performance and sovereign-compliance coverage? How to re-evaluate TCO when power subsidies, localized supply chains, and chips policy materially change infrastructure economics? Our report is structured to answer those questions with the level of rigour required for decisive action.
Anti-Termite Treatments Market
Key macro drivers shaping vendor and buyer choices
-
Regulatory acceleration: Amendments to national cybersecurity and data-governance laws effective in early 2026 have tightened data sovereignty and cross-border transfer controls. Organizations that handle core or important data now face stricter localization, assessment and approval requirements—shaping sourcing decisions, contractual terms and cloud architecture choices.
-
Xinchuang & procurement momentum: National initiatives to replace foreign systems in government, SOEs and critical industries have matured from policy to procurement. Public-sector and regulated buyers are implementing replacement pathways that materially influence market demand and vendor roadmaps.
-
Infrastructure economics: Local incentives—such as electricity subsidies for data centers that adopt domestic chips—and the rapid expansion of national data-center capacity (over several million standard rack units by late‑2025) are altering TCO models for on-premise and cloud deployments. These shifts mean that buyers must re-run TCO with localized cost inputs rather than relying on global benchmarks alone.
-
Technology convergence: Domestic vendors are increasingly delivering cloud-native distributed databases, NewSQL, and AI-native capabilities that blur traditional lines between transactional and analytical workloads. This trend increases the opportunity for consolidation, but also raises migration complexity for legacy systems.
What the competitive landscape looks like
The market is moderately concentrated: our analysis shows the three largest providers account for a substantial portion of the market and the top five capture a clear majority, underscoring both incumbent strength and the presence of a vibrant mid-tier of specialized vendors. This concentration has practical implications for procurement risk, ecosystem lock-in, and negotiation dynamics.
-
Leading hyperscalers and cloud-native challengers: Major cloud providers have invested heavily in in-house distributed databases and cloud-native offerings. These solutions emphasize operational automation, scale and cloud integration—making them attractive for new cloud-first projects and for large transactional workloads that require high availability and benchmark performance.
-
Open-source and NewSQL innovators: Several vendors combine open-source community traction with enterprise-grade extensions, offering hybrid transactional and analytical processing capabilities that appeal to firms pursuing consolidation of analytic and OLTP platforms.
-
Specialized and regulated-use suppliers: A number of vendors focus on financial-grade transactionality, government localization and compliant deployment patterns. Their roadmaps prioritize robust security features, certification readiness and performance under high compliance constraints.
Notable vendor developments in recent quarters demonstrate the market’s rapid product evolution: a leading distributed database open-sourced an AI-native hybrid-search database late in 2025; several cloud vendors achieved benchmark performance leadership; and continuous product releases through early 2026 focused on operational tooling, observability and primary/standby architecture enhancements. These moves reflect a race to combine performance, AI-ready capabilities and enterprise-grade manageability.
Strategic implications for enterprise and public-sector buyers in 2026
-
Reassess migration roadmaps with policy as a first-order constraint. Technical feasibility must now be evaluated together with regulatory approval timelines, security assessment requirements and potential contractual constraints on cross-border data flows.
-
Adopt modular architectures for risk mitigation. Blended deployment strategies—mixing cloud-native, managed services, and controlled on-premise footprints—allow organizations to preserve agility while meeting localization and continuity requirements.
-
Quantify true TCO with localized inputs. Buyers should model scenarios that include regional power economics, potential subsidies, and chip availability constraints; these factors can materially alter the calculus between on-premise and cloud choices.
-
Prioritize vendor maturity in operations and observability. As databases scale into mission-critical systems, the ability to operate, monitor and recover at scale becomes a key selection criterion—sometimes outweighing raw benchmark performance.
-
Embed compliance workflows into procurement and contracts. Security assessments, data export controls, and certification roadmaps must be codified into vendor SLAs and migration contracts up front.
What the PW Consulting report delivers (high-level)
Designed for practitioners who must act in 2026, the full report combines rigorous market modelling with execution-focused tools. Deliverables include:
-
Market sizing and trend analysis (historical 2020–2025, base year 2025, and forward projections 2026–2032) with scenario modelling and sensitivity analysis to inform multiyear budgets and capital plans.
-
Vendor benchmark profiles that synthesize architecture, deployment maturity, compliance posture, performance claims and go-to-market strengths—accompanied by an ecosystem map of partnerships, certified systems integrators and managed-service operators.
-
Operational playbooks for migration and coexistence—including migration matrices, cutover risk frameworks, rollback planning and runbook templates for hybrid transactional/analytical consolidation.
-
Procurement and contracting templates aligned with data-security assessment workflows and localization requirements, enabling procurement teams to accelerate compliant vendor selection.
-
TCO and ROI models with configurable inputs for power subsidies, local labor rates, and chip availability scenarios—supporting finance and IT trade-off conversations.
-
Scenario-based risk assessments covering supply-chain constraints, regulatory shifts and escalation pathways that boards and risk committees should monitor closely.
These deliverables are supported by primary interviews, vendor disclosures, benchmark data and policy analysis. The report balances strategic orientation with tactical deliverables that technical and procurement teams can put to immediate use.
How organizations should use this intelligence in 2026
-
Short term (0–12 months): Use the report to define compliant migration paths for projects in flight, validate vendor performance claims against third-party benchmarks, and lock in contractual protections for cross-border data operations.
-
Medium term (12–24 months): Recalibrate platform roadmaps to exploit cloud-native efficiencies while hedging with on-premise or co‑located deployments for regulated data. Update RFPs and vendor scorecards with the report’s operational metrics and procurement templates.
-
Long term (24+ months): Incorporate the report’s scenario-led forecasts into multi-year capital planning, talent development (DBA and SRE capability building) and partner selection strategies—anticipating consolidation and continued product evolution across the ecosystem.
About market concentration and risk
Market concentration metrics indicate that a few large providers account for a significant share of revenues, while a competitive mid‑tier supplies specialized and regulated solutions. For buyers, concentration implies both negotiating leverage and systemic vendor risk—making diversification and contractual protections strategic necessities. For vendors, the path to scale requires not only superior engineering but also compliance certifications, ecosystem partnerships and demonstrable operational maturity.
Next steps and where to find the full study
This briefing has been structured to provide actionable strategic insight while preserving the proprietary segment tables, vendor scoring matrices and downloadable TCO models that further enable decision-making. PW Consulting’s full Worldwide Chinese Domestic Databases Market report (base year 2025, historical 2020–2025, forecast 2026–2032) contains the granular breakdowns by deployment mode, database model and industry vertical, plus the full vendor benchmarking dataset and executable playbooks.
For executive briefings, bespoke workshops to apply the models to your environment, or access to the full report and supporting tools, please visit the PW Consulting report page or contact our strategy team to schedule a briefing. The full report is the only place to obtain the underlying tables, vendor scorecards and the downloadable scenario models referenced here.
For detailed analysis of this topic, please visit the official page: Worldwide Chinese Domestic Databases Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com