

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Category: market research
PW Consulting: Worldwide Twist Dispensing Closure Market to Grow at 5.06% CAGR, Reaching USD 678.8 Million by 2032
By pmarketresearch, 2026-08-12
PW Consulting: Strategic Preview — Worldwide Twist Dispensing Closure Market Report (Base Year 2025) and Its Value for 2026 Decision‑Making
Executive summary
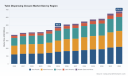
PW Consulting’s latest market study on the Worldwide Twist Dispensing Closure Market positions industry leaders and investors to make time‑sensitive, high‑impact decisions through 2026 and beyond. Our analysis shows the market expanding from an assessed 2025 revenue of USD 480.5 Million to an expected USD 509.2 Million in 2026, reflecting a compound annual growth trajectory (CAGR) of approximately 5.06% over the forecast horizon. By 2032, we project the market will approach USD 679 Million under the base scenario, driven by packaging innovation, sustainability regulation, and steady end‑market demand.
Medical Gas Supply Equipment Market
Why this report matters for 2026 strategic planning
- Tactical timing: 2026 is a pivot year for closure manufacturers and brand owners. Regulatory milestones, recycled content mandates, and faster product innovation cycles mean capital allocation and product roadmaps set in 2026 will determine competitive positioning into the early 2030s.
- Cost sensitivity and margin management: Raw‑material trajectories (notably polypropylene and HDPE) and supply chain tightness continue to influence unit economics for twist dispensing formats. Our scenario analysis quantifies margin exposure to resin price swings and offers hedging and sourcing strategies tailored to different business models.
- Product and portfolio decisions: Choices between mono‑material, tethered, multi‑part, and elastomer‑insert solutions have implications for recyclability compliance, manufacturing complexity, and application performance. The report maps these trade‑offs and prescribes go‑to‑market sequencing for 2026 launches.
- M&A and JV prioritization: With measured market growth and pockets of accelerated demand, 2026 is an optimal window to evaluate bolt‑on acquisitions that fill capability gaps (e.g., tethered systems, induction sealing, PCR processing) or to pursue capacity rationalization where overhang exists.
Market dynamics shaping the outlook
The twist dispensing closure category is influenced by a confluence of structural and near‑term dynamics. On the structural side, secular shifts in consumer preference toward convenience and dosing control continue to expand applications across food & beverage, personal care, household, and pharmaceutical segments. On the near‑term side, sustainability regulation and resin economics are the dominant drivers.
Agricultural Photovoltaic System Market
- Regulatory pressure: Extended Producer Responsibility (EPR) schemes and single‑use plastics rules have accelerated product redesign toward tethered and mono‑material closures. These mandates change not only product specs but also supplier qualification criteria, testing, and lifecycle reporting requirements.
- Resin price volatility: As of April 2026, polypropylene prices show meaningful regional spreads — an operational reality for manufacturers with global footprints. This pricing dispersion creates opportunities for localized sourcing, cost arbitrage, and shifts in material mix, but also raises the importance of flexible tooling and dual‑resin designs.
- Recycled content and circularity: Brand owners are increasingly requesting post‑consumer recycled (PCR) content in closure components. Performance trade‑offs for PCR, and the need for consistent supply, creates a premium on supplier capabilities in material qualification and processing know‑how.
Competitive landscape — capabilities that matter in 2026
The market is populated by established closure OEMs and specialized manufacturers that each bring distinct capabilities. Our competitive assessment focuses on capability clusters that will determine winners and followers in 2026’s market environment.
Aerospace Laser Rangefinder Market
- Integrated, scale‑oriented suppliers: Companies with broad global manufacturing footprints and multi‑channel relationships to major beverage and FMCG brands retain advantages in large contract wins and rapid ramping of tethered or mono‑material designs. Their scale supports investment in automation and high‑speed application systems.
- Innovation and specialty players: Firms with deep experience in child‑resistant, tamper‑evident, and dosing solutions continue to command technical premium and faster adoption in regulated segments (e.g., pharmaceuticals, certain personal care products). Recent product launches demonstrate a continued push into safety‑oriented and eco‑friendly closures.
- Service‑oriented converters and distributors: Those that combine localized inventory management, customization services, and fast prototyping are preferred partners for mid‑sized brands that require agility rather than scale.
Company spotlights — strategic takeaways
- Silgan Holdings Inc. — Recognized for established twist‑off and mono‑material Plasti‑Twist® solutions, Silgan’s strengths lie in integration with liquid food and non‑carbonated beverage systems, including liner and induction sealing know‑how. Strategic implication: Silgan is well positioned to convert large CPG accounts seeking simplified recycling streams.
- AptarGroup Inc. — Aptar’s focus on dispensing innovation and sustainable designs, including recent child‑resistant twist solutions, makes it a go‑to supplier for brands prioritizing consumer convenience and regulatory compliance. Strategic implication: partnerships around co‑developed sustainable closures can accelerate market adoption for both parties.
- Berry Global Group, Inc. — With strong capabilities across pumps, valves, and dispensing mechanisms, Berry presents a compelling supplier for complex, multi‑component dispensing systems. Strategic implication: Berry is attractive for brands consolidating suppliers for integrated dispensing assemblies.
- Closure Systems International (CSI) — CSI’s tethered and high‑speed application strengths align with beverage and dairy customers adapting to tethered mandates. Strategic implication: CSI is a logical partner for beverage producers seeking compliance with minimal line rework.
- O.Berk, Mold‑Rite, Amcor, TriMas, BERICAP, Guala Closures — These players collectively represent the mid‑to‑high end of the market: diverse portfolios, specialty formats, and geographic reach. Strategic implication: collaborative sourcing and co‑innovation agreements (e.g., PCR adoption, elastomer inserts) will be common strategies in 2026.
Recent innovation cues and what they signal
Product announcements over the 2024–2026 window underline the dual track of innovation: performance plus sustainability. New launches that combine child safety, gas‑tight seals, and recycled content demonstrate how technical differentiation is increasingly tied to circularity credentials. For buyers, this means product roadmaps should not treat sustainability as a bolt‑on but as a core functional requirement.
What PW Consulting’s report includes (practical, executable content)
Our report is designed as a strategic playbook for executives, product managers, procurement leads, and investors. Highlights include:
- Market model and scenarios: A buildable financial model with topline and bottom‑line scenarios reflecting different regulatory and resin‑price environments through 2032.
- Cost sensitivity and pricing deck: Unit‑cost models showing the impact of resin price shifts, PCR premiums, and assembly complexity — paired with recommended pricing levers and margin protection strategies.
- Go‑to‑market playbooks: Tailored roadmaps for OEMs, converters, and brand owners that prioritize product launches, channel strategies, and customer segmentation without disclosing confidential segment share data in the summary.
- Supplier capability matrix: A pragmatic vendor shortlist aligned to capability clusters (e.g., tethered systems, induction sealing, PCR processing) and qualification checklists for faster vendor selection in 2026.
- Regulatory and compliance toolkit: Actionable checklists and timelines to manage EPR reporting, tethered closure implementation, and recyclability certification with recommended third‑party partners.
- M&A and capital allocation framework: Valuation lenses and integration playbooks for bolt‑on acquisitions or joint ventures targeted at closing capability gaps in sustainability, high‑speed application systems, or specialty dosing technologies.
How to use the report to accelerate outcomes in 2026
- Procurement leads: Use the supplier matrix and cost sensitivity tools to renegotiate contracts and lock in blended resin supply arrangements that hedge regional price spreads.
- Product teams: Adopt the design trade‑off maps to prioritize mono‑material and tethered variants where regulation and brand positioning demand recyclability without sacrificing functionality.
- C‑suite and strategy teams: Apply the M&A framework and scenario models to stress test inorganic growth options and to timetable capex for tooling and automation investments.
- Investors: Use the competitive assessment to identify differentiated capabilities that de‑risk execution and align with 2032 growth vectors.
Teaser: deeper insights behind the paywall
This press release purposefully highlights the strategic contours of the market while withholding granular segmentation and proprietary competitive share tables. The full PW Consulting report contains detailed regional and end‑use splits, customer win/loss analyses, and granular concentration metrics required for transactional due diligence and product prioritization. These datasets and the interactive model are accessible via the report portal for subscribers and bespoke advisory clients.
Next steps and how to engage PW Consulting
For leadership teams preparing their 2026 playbooks, PW Consulting offers three engagement options: (1) full report purchase including interactive financial model; (2) short advisory sprint to translate report findings into a 90‑day action plan; (3) custom due diligence and integration support for M&A or strategic sourcing. Early engagement ensures access to scenario workshops that align cost, regulatory, and product development timelines with your capital planning cycle.
Contact PW Consulting to request the report overview, schedule a briefing, or commission a tailored advisory engagement. Our team of packaging engineers, regulatory analysts, and market strategists is prepared to convert the market’s unfolding dynamics into executable advantage for 2026.
For detailed analysis of this topic, please visit the official page: Worldwide Twist Dispensing Closure Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Market Insights: Worldwide Liquid Termiticides Market to Hit USD 4,042.31 Million by 2032, Expanding at a 5.12% CAGR
By pmarketresearch, 2026-08-12
Worldwide Liquid Termiticides Market — 2026 Strategic Outlook (PW Consulting)
Executive summary
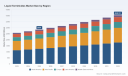
As the liquid termiticides market enters a new strategic inflection point, PW Consulting’s latest market study provides an indispensable evidence base for 2026 corporate decision-making. The market has grown from USD 2,579.14 Million in 2023 to an estimated USD 2,850.0 Million in 2025, and our baseline projection shows expansion to roughly USD 4,042.31 Million by 2032. Our forecast for the 2026–2032 period is driven by a compound annual growth rate (CAGR) of 5.12% under the base-case scenario.
Mental Stress Analyzer (Heart Rate Variability Detector) Market
These headline figures only hint at the complexity behind industry dynamics. Strategic choices in 2026 — around R&D prioritization, supply chain resilience, product stewardship and M&A — will determine winners and laggards through the coming cycle. This release summarizes the report’s high-value insights and tactical frameworks, while reserving the detailed segment-level tables and proprietary scenario outputs for the full report.
Worldwide Heavy Duty Truck Seat Market
Why 2026 is a pivotal year
-
Regulatory tightening and stewardship expectations are accelerating. The U.S. EPA’s 2025 Insecticide Strategy (April 2025) elevates mitigation requirements for insecticides to protect endangered species, creating new constraints on field use patterns and technical support expectations from manufacturers.
Ethylene Oxide Device Sterilization Market -
Active ingredient risk profiles and market access are in flux. Policy actions and scientific assessments continue to constrain agricultural uses of certain actives — a dynamic that spills into structural pest management through supply pressure, public perception, and stewardship obligations.
-
Supply-side dynamics are more volatile. Between raw material price inflation for key actives and episodic supply chain bottlenecks linked to geopolitics and transport disruptions, manufacturers face margin and availability trade-offs that require immediate mitigation plans.
-
Customer expectations and commercial models are evolving. Professional applicators demand formulations that balance efficacy, safety, application efficiency and regulatory defensibility; meanwhile, service models and bait technologies continue to reshape purchase and adoption dynamics.
What PW Consulting’s report delivers (practical, execution-focused)
-
Robust market-sizing and probabilistic forecasting model: Our model produces top-line market trajectories (2020–2032) with alternative scenarios that embed commodity shocks, regulatory tightening, and adoption curves for reduced-risk chemistries.
-
Regulatory and stewardship dashboard: A jurisdiction-by-jurisdiction heat map of regulatory risk drivers and expected timelines for policy actions, including mitigation measures that materially affect use patterns and labeling.
-
Supply chain risk maps and cost-to-serve analysis: An operational playbook identifying single points of failure, near-shoring opportunities, and indexed sensitivity of gross margins to raw material cost movements.
-
Competitive positioning toolkit: Product and channel benchmarking, go-to-market playbooks for global and regional rollouts, and a transaction screen for target selection in consolidation scenarios.
-
Field-efficacy and stewardship matrix: Comparative performance and application-efficiency scores for major liquid formulations, tied to technician training and quality assurance interventions that improve in-field outcomes.
-
Scenario-based strategic roadmaps: Tactical initiatives ranked by expected value and implementation complexity — from formulation reformulation programs to pilot manufacturing partnerships and targeted commercial trials.
Competitive dynamics — what the major players signal
The liquid termiticides market remains moderately concentrated: the top three global suppliers account for a material share of volumes and influence over distribution channels, with the top five further consolidating market power. Against this backdrop, incumbent agrochemical and pest management firms retain a mix of advantages — established portfolios, regulatory dossiers, and deep technical support networks — while nimble specialists and generics providers exert pricing pressure in mature channels.
-
BASF SE (Termidor portfolio) — Strengths: market-leading brand recognition and a proven non-repellent solution set that underpins pre- and post-construction programs. Strategic implication: BASF’s depth in stewardship programs and technical support raises the barrier for new entrants seeking share in professional channels.
-
Syngenta AG (Altriset / chlorantraniliprole) — Strengths: a reduced-risk active that aligns with regulatory and customer demand for lower mammalian and non-target toxicity. Strategic implication: regulatory windows (including recent temporary residue tolerances) materially affect commercialization runway; manufacturers should plan for both opportunity windows and expiry of special allowances.
-
FMC Corporation — Strengths: broad pyrethroid portfolio and strong relationships with professional applicators. Strategic implication: price and supply management for pyrethroid active ingredients will influence FMC’s mix decisions; investment in stewardship and non-target risk mitigation is essential to defend market access.
-
Bayer AG — Strengths: Premise (imidacloprid-based) legacy product and global distribution muscle. Strategic implication: imidacloprid’s constrained agricultural profile requires Bayer to focus on structural use stewardship and labeling clarity to maintain acceptance among customers and regulators.
-
Nufarm Limited and Sumitomo Chemical — Strengths: global formulation and distribution capabilities tailored to local market needs. Strategic implication: these firms are well-positioned to offer regionally adapted formulations and to execute nimble supply strategies.
-
Control Solutions Inc. and Ensystex Inc. — Strengths: competitive generics and integrated service-product offerings that compete on cost and convenience. Strategic implication: generics and integrated-service models will continue to exert downward price pressure and accelerate commoditization in selected channels.
Regulatory and raw-material realities that will shape 2026 decisions
-
Policy developments are active and consequential. The U.S. EPA’s Insecticide Strategy (April 2025) signals heightened mitigation and species-protection obligations that apply to insecticide use patterns, including those relevant to termiticide applications.
-
Time-limited regulatory allowances create tactical windows. A recent time-limited tolerance established in late 2025 for residues of a reduced-risk active in a specific commodity illustrates how administrative flexibility can create temporary commercialization advantages — but such allowances come with expiration dates that must be planned for.
-
Raw material cost and supply volatility matter. Key active ingredients experienced meaningful price increases in recent years, and transport or production bottlenecks have periodically disrupted supply. Companies without diversified sourcing or hedging strategies face margin compression or lost sales.
-
Non-target protections and agricultural restrictions are reshaping perceptions. Uses of some historically common actives have been restricted in agriculture due to pollinator and non-target risks; this regulatory and reputational pressure prompts manufacturers to accelerate alternatives and stewardship investments in structural pest control.
Risks, opportunities and priority choices for 2026
-
Risk — Regulatory tailwinds can turn into constraints: Firms overly dependent on a narrow set of actives risk sudden label changes, use restrictions or reputational headwinds. Mitigation: diversify active portfolios and invest in residue and non-target monitoring programs.
-
Opportunity — Reduced-risk chemistries and application efficiencies: Accelerating adoption of lower-risk actives and high-efficiency application systems is a durable market trend. Action: allocate R&D and field-trial budgets now to capture early-adopter share and to build stewardship narratives.
-
Risk — Supply-chain fragility and raw-material cost shocks: Single-supplier dependencies for specialty intermediates create commercial vulnerability. Mitigation: near-shoring, dual sourcing, and strategic inventory policies should be stress-tested under the scenarios we provide.
-
Opportunity — Service-led differentiation: Integrated offerings that combine product, digital decision-support and technician training materially increase switching costs and customer lifetime value. Action: pilot service bundles in key provinces and measure retention uplift.
Top-line strategic recommendations for 2026
-
Prioritize portfolio resilience: Invest in at least two alternative active chemistries and accelerate formulation work that reduces reliance on constrained inputs.
-
Operationalize regulatory scenario planning: Create a cross-functional “regulatory war room” to model label changes, conditional tolerances and mitigation prescriptions that could hit volumes or application methods.
-
Hedge supply risk pragmatically: Combine contractual off-take, strategic inventory buffers and selective near-shoring to reduce single-point failure exposure without overcapitalizing.
-
Monetize stewardship: Turn regulatory compliance into a commercial asset by certifying applicator networks and using stewardship credentials to secure premium channel partnerships.
-
Use M&A and partnerships selectively: Target bolt-on formulations, local manufacturing capacity and service platforms that accelerate time-to-market for reduced-risk solutions.
How PW Consulting supports execution
The full PW Consulting report is designed as both a strategy blueprint and an implementation toolkit. Subscribers receive the granular scenario outputs, the full segmentation matrices, playbooks for pricing and channel expansion, and customizable financial models. We also provide advisory engagements to operationalize recommendations through pilot programs, regulatory engagement strategies, and M&A target diligence.
This briefing is a strategic “trailer” that highlights the decision levers that matter entering 2026. For the detailed segment tables, localized forecasts, and the proprietary scenario model that underpins the USD 4,042.31 Million 2032 projection (with a 5.12% CAGR for 2026–2032), please refer to the full Worldwide Liquid Termiticides Market report and contact PW Consulting for access to the complete dataset and bespoke advisory options.
For detailed analysis of this topic, please visit the official page: Worldwide Liquid Termiticides Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report: Worldwide Fish & Shrimp Feed Additives Market Poised to Grow at a 5.45% CAGR in the 2026–2032 Forecast
By pmarketresearch, 2026-08-12
Worldwide Fish and Shrimp Feed Additive Market — Strategic Preview for 2026 Decision‑Makers
Executive summary
PW Consulting’s new market intelligence brief positions the global fish and shrimp feed additive market as a strategically important, steadily growing segment of aquaculture value chains. The global market expanded from USD 1,879.03 Million in 2020 to USD 2,450.00 Million in 2025, and our scenario-based models project an ascent to approximately USD 3,552.16 Million by 2032. This trajectory implies a compound annual growth rate (CAGR) of 5.45% across the 2026–2032 forecast window, underscoring durable demand driven by intensifying protein production, feed efficiency optimisation and rising farmer sophistication.
Worldwide Anchor Windlass Market
Why this matters for 2026 strategy
For corporate leadership teams evaluating investments, partnerships or product-roadmap shifts in 2026, this market sits at the intersection of three decisive forces: input cost volatility, regulatory tightening, and sustainability-driven innovation. These dynamics reshape supplier margins, route-to-market economics and differentiation vectors for both ingredient manufacturers and integrated feed houses. Our report translates these macro forces into pragmatic choices — where to protect margin, where to invest for growth, and what to buy or build to capture the next wave of value.
Worldwide Single Speed Bike Market
Market trajectory and macro drivers
- Growth momentum: The market’s steady CAGR of 5.45% reflects a balance of mature demand in established species and incremental adoption of functional additives that deliver measurable improvements in feed conversion, disease resilience and product quality.
- Input cost pressure: Synthetic amino acids (notably methionine and lysine) and traditional marine ingredients experienced price shocks driven by energy market swings and regional regulatory shifts. These upstream movements materially affect cost structures across the value chain.
- Sustainability pivot: A rapid pivot toward alternative protein sources (for example, insect meal and plant-based ingredients) is reducing reliance on fishmeal and fish oil and creating addressable demand for complementary additives that stabilise digestion, nutrient uptake and gut health when formulations change.
- Regulatory and compliance load: Regulatory compliance is a non‑trivial operating expense. For context, the total annual regulatory cost burden across US aquaculture farms was estimated at USD 196 million in 2023 (2023 USD), representing a material proportion of operating costs on many farms. Regulatory approvals and feed certifications are therefore value multipliers for suppliers.
Competitive landscape — what the leader set signals
The market is neither a pure commodity space nor a protected niche; it shows moderate concentration with the top three players accounting for under one-third of market share and the top five for roughly two-fifths. This “consolidated-fragmented” structure rewards scale in manufacturing and distribution while leaving room for specialised innovators.
Fully Enclosed Cable Carrier Market
Key incumbents — ranging from global ingredient conglomerates through to integrated feed multinationals and regional champions — are deploying divergent strategies: vertical integration, specialty performance portfolios, sustainability certifications, and targeted partnerships to secure alternative-protein inputs. Recent headline moves include commercialisation of insect-meal based shrimp feed solutions and first-in-market feed certification wins, which accelerate market adoption by lowering buyer risk.
Regulatory and technology inflection points
- Regulatory approvals for therapeutic additives and generics are loosening certain competitive bottlenecks — exemplified by recent approvals for aquaculture-targeted antimicrobials — but they also raise scrutiny on residue management and withdrawal periods.
- Certifications (e.g., third‑party feed sustainability schemes) are transitioning from “nice to have” to procurement prerequisites for large buyers and retailers. Certification delivers price elasticity advantages and accelerates market access in premium channels.
- Technology convergence — microbiome science, precision nutrition and enzyme engineering — is enabling additives to be marketed on verifiable performance claims (reduced FCR, lower mortality, improved pigmentation), changing the buyer conversation from price per kg to value per tonne of produced biomass.
Risks that will influence 2026 decisions
Executives need to stress-test strategies around three interlinked risk clusters:
- Raw-material exposure: Volatility in amino acids and marine ingredients can compress margins quickly. Hedging, contract innovation and diversification of input suppliers are practical mitigants.
- Regulatory shifts: Faster approvals can democratise access to proven actives but also shorten exclusivity windows. Conversely, tighter residue standards can abruptly constrain certain product lines.
- Market access and certification risk: Buyers increasingly demand traceability and accredited sustainability proof points; failure to secure certifications delays entry into higher‑value channels.
Where value will be captured in 2026 — an operator’s playbook
Based on our cross‑market analysis, the highest‑leverage moves for 2026 are concrete and executable:
- Portfolio prioritisation: Reallocate R&D and commercial resources toward additive classes that demonstrably reduce input cost per unit biomass or unlock premium pricing (gut-modulators, targeted amino acid blends, enzyme systems and certification‑aligned pigment solutions).
- Supply chain hedges: Negotiate flexible supply contracts and strategic inventory positions for synthetic amino acids and critical co‑ingredients; consider toll-manufacturing partnerships to smooth margin volatility.
- Partnerships for alternative proteins: Fast-track offtake agreements and co‑development with insect meal, single-cell protein and plant-protein producers to lock preferential access and co-create additive suites that mitigate formulation shifts.
- Regulatory and certification roadmap: Invest in dossier development and pre‑emptive safety studies for priority markets; obtain feed certifications that shorten buyer trial cycles and reduce procurement friction.
- M&A and bolt‑on criteria: When evaluating targets, prioritise companies with predictable raw-material exposure profiles, validated product efficacy data, scalable manufacturing and existing certification traction.
What PW Consulting’s report delivers — operational depth
The full PW Consulting report is designed as an operational toolset for 2026 planning, not an academic exercise. Core deliverables include:
- Bottom‑up market-size build and reconciled top‑down validation for the 2020–2032 window, with scenario outputs tuned to input-cost, regulatory and adoption-rate sensitivities.
- Segment-level diagnostic frameworks (by additive type and application) that illuminate margin pools, penetration curves and unit-economics breakpoints — presented as playbooks for product prioritisation.
- Supply‑chain mapping and vulnerability heatmaps that identify single-source risks, pricing transmission lags and viable domestic/regional supply alternatives.
- Competitive benchmarking of the leading global and regional players, including capability maps (manufacturing, R&D, commercial reach), recent strategic moves and deal‑rationale templates.
- Regulatory and certification trackers with go-to-dossier checklists tailored to the major export markets and premium procurement channels.
- Commercial due diligence pack: customer willingness-to-pay matrices, trade-channel economics, and sample pitch decks to accelerate commercial trials and procurement approvals.
- Valuation and M&A playbooks, with sensitivity-tested thesis memoranda suited for private equity and corporate development teams.
To respect the “trailer” principle, the report demonstrates how each of these modules interlocks to support a 12–24 month strategic plan without exposing proprietary segment tables or region‑by‑application revenue splits in this press preview.
Actionable recommendations for 2026 leadership teams
For management teams preparing budgets and capital allocation cycles in 2026, we recommend the following prioritized actions:
- Recast P&L scenarios with at least two raw‑material price shocks and one regulatory tightening case; stress-test product mix at the SKU level.
- Execute 1–2 strategic supplier agreements (one for risk mitigation, one for preferential innovation) to lock critical inputs or co‑develop alternative‑protein formulations.
- Fast‑track validation projects with lead customers using performance‑linked pricing pilots that capture value from demonstrated FCR or mortality improvements.
- Acquire or partner for certification credentials in priority markets — the time-to-certification advantage converts into commercial access and margin resilience.
- Use M&A to acquire niche capabilities (microbiome science, enzyme engineering or pigment technologies) that would be capital‑inefficient to develop in‑house over 24 months.
Concluding perspective
The fish and shrimp feed additive market is poised for measured expansion: reliable growth at the aggregate level combined with pockets of rapid change at the product and channel levels. In 2026, winners will be those that translate technical differentiation into verified commercial outcomes, hedge exposure to upstream shocks, and move faster than peers on certification and supply‑base transformation. PW Consulting’s full report provides the quantitative underpinnings and executable playbooks to choose which defensive measures to implement and which offensive bets to make.
Next steps
For boards, corporate development teams and commercial leaders ready to convert this strategic preview into a 90‑day execution plan, PW Consulting offers tailored workshops, target screening for M&A, and hands‑on due diligence engagements. The full report contains detailed segment tables, regional demand matrices and vendor-level data that are intentionally reserved for the primary report package — contact PW Consulting to access the complete dataset and model pack.
For detailed analysis of this topic, please visit the official page: Worldwide Fish and Shrimp Feed Additive Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Wearable Injectors Market to Reach USD 22,323.33 Million by 2032 at a 13.5% CAGR
By pmarketresearch, 2026-08-12
Worldwide Wearable Injectors Market: Strategic Imperatives for 2026 — PW Consulting Insights
As wearable injectors transition from niche innovation to mainstream delivery platforms, 2026 represents a decisive year for commercial teams, device manufacturers, and strategic investors. PW Consulting’s latest market study — anchored on a 2025 base year and projecting through 2032 — quantifies a striking trajectory: the global market more than doubled in five years to USD 9,200 Million in 2025 and is set to surpass USD 10,900 Million in 2026, with a forecast compound annual growth rate (CAGR) of 13.5% across the 2026–2032 horizon. This growth is accompanied by increased market concentration (CR3 ~55.4%; CR5 ~72.8%), maturing regulatory clarity, and accelerating payer engagement — forces that together define a narrow window of opportunity for first movers and fast followers.
Lead-acid Battery for Telecom Base Station Market
Why 2026 Decisions Will Define Multi-Year Outcomes
-
Adoption inflection: Clinical evidence packages and human factors work completed in 2024–2025 are starting to unlock regulatory clearances and commercial launches. The coming year will separate organizations that can operationalize commercialization from those still optimizing R&D.
Next Generation Managed Security Service Market -
Commercial tooling and reimbursement alignment: With clearer billing pathways emerging, notably specific HCPCS codes that can be applied to wearable injector supplies under Medicare Part B, manufacturers who align product design, labeling, and coding strategies now will accelerate time-to-market and reimbursement capture.
Solar-Powered Water Pump Inverters Market -
Consolidation and partnering: A concentrated supplier base means that strategic partnerships — licensing, co-development, or commercialization agreements — will materially shape access to scale. The reported CR3/CR5 levels indicate that a handful of players already control substantial share, raising the stakes for alliance-making in 2026.
What the PW Consulting Report Delivers — Practically
Our research is designed to be operational from day one. The report is deliberately structured to translate intelligence into executable plans, without requiring readers to distill raw data into strategy themselves. Key deliverables include:
-
Market sizing and scenario models calibrated to the 2025 base year and spanning 2026–2032, with alternative uptake assumptions (conservative, base, accelerated) and sensitivity levers for pricing, penetration, and reimbursement.
-
Go-to-market playbooks tailored for device OEMs, pharma partners, and contract manufacturers: channel strategies, launch sequencing, field force deployment, and sample-to-prescription conversion frameworks.
-
Commercial due diligence templates and NPV models for M&A and partnership negotiations, including break-even timelines, dilution scenarios, and milestone structuring guidance.
-
Regulatory and clinical path maps covering device standards, key submission strategies, and human factors evidence aligned to ISO and IEC requirements.
-
Reimbursement and pricing roadmaps that integrate payer segmentation, coding strategies, and warranty/service models to protect margin while supporting adoption.
-
Supply-chain risk heatmaps — from resin pricing to electronics sourcing — with mitigation playbooks and supplier scorecards to preserve time-to-volume.
-
Competitive landscaping with capability matrices, partnership mappings, and likely strategic trajectories for the leading players (teaser level; segment-level share tables are reserved for the full report).
Competitive Landscape — Who Matters and Why
The wearable injector arena is dominated by a mix of specialized device OEMs and strategic supply partners. PW Consulting’s analysis highlights several companies whose actions in 2024–2025 materially shift competitive dynamics:
-
Ypsomed (Switzerland) — A leader in on-body systems with platforms designed for large-volume subcutaneous delivery. Their October 2025 launch of an enhanced connectivity-enabled SmartPilot marks a deliberate push to convert digital telemetry into clinical and commercial value, improving adherence verification and real-time dosing visibility for pharma partners.
-
West Pharmaceutical Services (USA) — With a strong platform approach and deep commercial relationships, West announced a major commercial supply agreement in March 2025 that signals confidence among top-tier pharma customers in the SmartDose platform. West’s scale positions it as an attractive partner for companies seeking rapid commercialization.
-
Enable Injections (USA) — A technology specialist focused on high-volume self-administration devices. FDA 510(k) clearance in June 2025 for a 10mL variant of the enFuse injector expands its addressable indications and reinforces its role as a prime partner for biologic developers targeting patient-centric delivery.
-
Stevanda (India) — Focused on cost-competitive solutions for emerging markets, Stevanda represents a distinct strategic play: serving price-sensitive systems and local pharma ecosystems where affordability drives adoption.
-
Medipim (Belgium) — With multi-day delivery systems designed for chronic indications, Medipim’s device architecture appeals to therapies demanding extended dosing windows and patient convenience.
-
Nexus Pharmaceuticals (USA) — Functions as a commercialization and distribution enabler, connecting device manufacturers with therapeutic sponsors, particularly in oncology and rare disease segments.
Taken together, these players illustrate two parallel market evolutions: technological differentiation (connectivity, dose volume, user experience) and commercial consolidation (strategic supply agreements and FDA-clearance-based credibility). With CR3 and CR5 concentrations indicating a substantially concentrated market, partnership choice and timing will drive competitive advantage.
Standards, Reimbursement and Supply-Chain Realities
-
Regulatory and safety standards: Wearable injectors are subject to established device norms — ISO 11608-01 for needle-based injection systems and IEC 60601-1 for electrical safety. Compliance to these standards is non-negotiable for market entry and payer acceptance.
-
Reimbursement mechanics: US Medicare coding developments (notably HCPCS-level designations for wearable injector supplies) have reduced a key commercial barrier. However, coding is only part of the puzzle: evidence of real-world effectiveness and cost-offsets is required to secure favorable coverage and utilization.
-
Materials and manufacturing: Device housings commonly rely on medical-grade polymers. Current bulk resin pricing remains an input consideration (medical-grade polycarbonate and cyclic olefin copolymer resins typically trade in an approximate range of USD 8–12/kg), and electronics supply constraints continue to affect lead times — both factors that should be stress-tested in 2026 budgeting cycles.
-
Regulatory usage constraints: Wearable injectors are prescription-only devices and not intended for experimental compounding without regulatory oversight — an important compliance guardrail for commercial and hospital adoption.
Strategic Imperatives for 2026 — What Leaders Should Do Now
-
Prioritize payer-ready evidence: Invest in targeted health-economic studies and real-world evidence collection that demonstrate adherence gains, administration cost savings, and potential reductions in site-of-care utilization.
-
Lock in scalable manufacturing early: Given resin pricing and electronics sourcing risks, secure dual-sourcing agreements and discuss capacity reservations with CMOs to avoid launch delays.
-
Design for digital integration: Telemetry and adherence data will increasingly influence formularies and contracting. Embed secure, standards-compliant connectivity options that align with sponsor data needs and regulatory expectations.
-
Choose partnership models strategically: Evaluate co-development, licensing, and white-label manufacturing against full-internalization scenarios. For many pharma companies, partnering with an established platform provider will accelerate time-to-market and reduce regulatory risk.
-
Segment go-to-market by payer sensitivity: Deploy differentiated pricing and service bundles for private payers, government payers, and self-pay channels to optimize uptake while preserving margin.
-
Prepare for consolidation dynamics: With a concentrated top tier, prepare contingency playbooks for potential competitor M&A or exclusive supply arrangements that could affect access to key platforms.
Why PW Consulting’s Report Is Essential for 2026 Execution
Our study bridges strategy and implementation. Beyond headline market figures, the report delivers executable plans, negotiation-ready financial models, and regulatory roadmaps aligned to current ISO/IEC expectations and recent reimbursement developments. It synthesizes competitive intelligence — including recent product launches, FDA clearances, and commercial agreements announced through 2025 — and maps likely scenarios that will shape 2026 market entry and scale-up.
If your organization is contemplating licensing, developing an in-house wearable injector, structuring a commercialization partnership, or evaluating acquisition targets, the intelligence in this report reduces uncertainty and accelerates decision velocity. To access the full dataset, granular segment analysis, and proprietary supply-chain scorecards that underpin these recommendations, please consult the full PW Consulting Worldwide Wearable Injectors Market report on our website.
For detailed analysis of this topic, please visit the official page: Worldwide Wearable Injectors Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Insect Growth Regulators Market to Climb from USD 1,105.04 Million in 2025 to USD 1,607.48 Million by 2032 at a 5.5% CAGR
By pmarketresearch, 2026-08-12
Worldwide Insect Growth Regulators Market — Strategic Briefing for 2026 Decision-Makers
PW Consulting’s latest market study on the Worldwide Insect Growth Regulators (IGR) market provides an executive-grade roadmap designed to inform capital allocation, product strategy, and regulatory positioning for 2026. Anchored on a 2025 base year and a forward-looking 2026–2032 forecast window, the analysis quantifies the market’s trajectory — a mid-single-digit compound annual growth rate (CAGR) and a clear expansion of the total addressable market over the forecast period — while delivering practical, decision-ready insight without exposing the proprietary line-item breakdowns that underlie our models.
Worldwide Paid Email Service Market
Why this report matters in 2026
-
Market momentum: After robust recovery and reinvestment across agriculture, urban pest management and animal health channels in the early 2020s, the IGR market is growing steadily. Our base-year assessment for 2025 and modeled trajectories through 2032 reflect an expansion consistent with sustained demand for selective, resistance-managing chemistries and an increase in professional pest-control spending globally.
Fixed Medical Pendant Market -
Consolidation and concentration: Competitive dynamics are neither fragmented nor monopolistic — market concentration is meaningful and favors incumbent global crop protection and specialty chemical players. This concentration creates both barriers to entry and strategic corridors for targeted M&A and portfolio carve-outs. Our concentration metrics show that the top-tier players account for a substantial share of the market, providing scale advantages in R&D, registrations and channel access.
Coagulation Test Kit Market -
Regulatory and stewardship pressure: Regulatory scrutiny continues to shape product design and go-to-market choices. Labeling requirements that reflect slower developmental activity, product group classifications tied to insect life-cycle stages, and use restrictions on certain granular formulations are forcing manufacturers to reengineer registrational strategies and stewardship programs.
-
Innovation vectors: Product innovation is moving on at least three axes — new modes of action and chemistries (including next‑generation ketoenols), formulations engineered for systemic activity and minimal residues, and application innovations supporting integrated pest management (IPM) in greenhouses, livestock systems and urban environments.
What the PW Consulting report delivers — practical assets for 2026 execution
-
Demand model with scenario capability: A flexible, auditable forecast model that converts macro drivers (crop prices, urbanization, livestock intensification, regulatory timelines) into demand volumes and revenue ranges under three planning scenarios.
-
Regulatory heat map and tracker: A rolling assessment of registration risks and label constraints across major jurisdictions, with distilled guidance on likely approval timelines and label language that materially affects adoption and use patterns.
-
Commercial playbooks: Channel-specific GTM modules for agriculture, professional pest management and animal health that prescribe packaging, pricing and distribution approaches tailored to each channel’s procurement dynamics and stewardship requirements.
-
Product portfolio optimization toolkit: A profitability and risk matrix that flags candidates for lifecycle extension, reformulation, or divestiture — designed to support 2026 budget allocation and R&D prioritization.
-
Competitive scorecards and M&A screening: Qualitative and quantitative assessment of the major market participants, plus acquisition target archetypes and a tactical M&A playbook for rapidly capturing niche growth pockets.
Competitive landscape — strategic implications for leading players
-
BASF SE — With a broad crop protection portfolio that includes chitin synthesis inhibitors and juvenile hormone analogs, BASF’s scale and channel reach enable it to defend premium agricultural segments. Strategic focus for 2026: leverage formulation know‑how to extend patent cliffs and bundle IGRs into integrated solutions that emphasize resistance management.
-
Bayer AG — The introduction of next-generation ketoenol products with systemic movement marks Bayer’s intent to own sap-feeder control and seed/foliar systemic plays. Strategic focus: accelerate seed-to-harvest stewardship pilots and explore subscription or service models that pair systemic IGRs with monitoring technology.
-
Syngenta AG — Syngenta’s expansion of urban-control formulations underscores a dual play across agriculture and professional pest control. Strategic focus: capitalize on urban pest resistance cycles by broadening monitoring partnerships with facilities management firms.
-
Sumitomo Chemical — Specialization in low‑residue chitin synthesis inhibitors for rice and horticulture offers a defensive moat in sensitive cropping systems. Strategic focus: protect regulatory advantages and explore label expansions into adjacent high-value vegetable and fruit markets.
-
Corteva Agriscience — As an integrated crop protection player, Corteva is positioned to embed IGRs into broader IPM portfolios. Strategic focus: orchestrate bundled offers that combine cultural, biological and chemical controls to preserve efficacy and rationalize application windows.
-
FMC Corporation — FMC’s portfolio emphasis on agricultural and speciality pest control enables nimble responses to niche opportunities. Strategic focus: cultivate specialty distribution partners and accelerate registration in underserved regulatory corridors.
-
ADAMA Ltd. — Recent launches for greenhouse thrips and whiteflies demonstrate ADAMA’s capability to win in regulated, high-margin horticultural niches. Strategic focus: double down on formulatory agility and local regulatory compliance to defend greenhouse channels.
-
Nufarm Limited — As a global supplier, Nufarm can flex across regions but must prioritize capital allocation. Strategic focus: prioritize scale plays in high-growth value chains while outsourcing complex registrations.
-
Valent U.S.A. LLC — U.S.-focused offerings position Valent to exploit domestic urban and agricultural demand. Strategic focus: align stewardship programs with state-level regulatory trends and professional applicator training.
-
Central Life Sciences — Specialization in feed-through products for livestock illustrates the value of targeted, channel-specific chemistries. Strategic focus: extend partnerships with animal health integrators and demonstrate ROI through field efficacy studies.
-
MGK — Focus on poultry and professional fly control gives MGK a durable niche. Strategic focus: convert technical leadership into bundled service contracts with major integrators.
-
Russell IPM — Niche developer and supplier to integrated pest management programs, with strength in horticulture and on‑farm solutions. Strategic focus: build licensing and white‑label partnerships with larger distributors.
Regulatory and supply‑chain dynamics to watch in 2026
-
Label-driven differentiation: Several IGR products carry regulatory labeling that reflects delayed developmental activity, group‑specific classifications and use restrictions in sensitive ecosystems. These constraints can materially affect application frequency and perceived value — and should be embedded into pricing and stewardship strategies.
-
Formulation constraints: Certain granular formulations have explicit use restrictions in particular crop types (e.g., rice paddies). Manufacturers must coordinate formulation R&D with regulatory teams to preserve addressable use cases.
-
Intermediates and raw materials: Synthesis of many IGR active ingredients depends on specialized intermediates (for example, phenoxyphenyl derivatives and juvenile hormone analog precursors). Securing upstream supply, qualifying secondary suppliers, and building inventory buffers are prudent actions to mitigate input volatility.
-
Resistance management and stewardship: EPA and other regulators increasingly expect active stewardship programs that limit resistance risk. This creates differentiation opportunities for firms that pair chemistry with monitoring, application guidance and education services.
Scenarios and recommended strategic moves for 2026
-
Baseline acceleration (most likely): Moderate demand growth persists as agronomic and urban spending trends continue. Recommendation: Invest selectively in reformulations that extend label life, scale targeted field trials to support premium pricing, and lock key intermediates with multi-year supply agreements.
-
Innovator upgrade (high-opportunity): Rapid adoption of next-gen systemic and low-residue IGRs in high-value crops and greenhouse systems. Recommendation: Fast-track commercial pilots with premium growers, pursue co-marketing with precision application vendors, and ready regulatory dossiers for adjacent geographies.
-
Regulatory tightening (risk scenario): Accelerated restriction of certain formulations compresses addressable markets in specific use-cases. Recommendation: Rebalance portfolios toward products with favorable residue and toxicity profiles, accelerate IP-protected formulation patents, and evaluate divestiture of at‑risk SKUs.
How PW Consulting partners with executive teams in 2026
-
Rapid-read briefings: Condensed C-suite briefings that translate our full market model into three immediate decisions — where to invest, what to shelve, and whom to partner with this financial year.
-
Regulatory playbook execution: End-to-end support from label language optimization to dossier readiness and regulatory engagement strategy.
-
M&A and carve‑out advisory: Target screening, valuation models that reflect product lifecycle and regulatory tail risk, and diligence playbooks focused on integration value capture for specialty IGR assets.
-
Commercial pilots and channel design: Field-proven go-to-market pilots with KPIs tied to adoption, repeat purchase and stewardship compliance — to de‑risk scale-up decisions.
PW Consulting’s Worldwide Insect Growth Regulators Market study is designed to be both a strategic compass and an operational manual for 2026 — showing where value pools will grow, where regulatory and supply risks concentrate, and the precise tactical moves that unlock ROI. The full report includes our detailed demand model, jurisdictional regulatory trackers, company scorecards and proprietary segmentation analyses. To access the complete intelligence package and the underlying data that informs our recommendations, please visit PW Consulting’s report page and request the full briefing.
For leaders evaluating portfolio shifts, M&A options, or aggressive commercial plays in 2026, this study provides the confidence and practical prescription to act. PW Consulting stands ready to translate these insights into executable plans that preserve efficacy, navigate regulation, and accelerate profitable growth in the evolving IGR landscape.
For detailed analysis of this topic, please visit the official page: Worldwide Insect Growth Regulators Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecast: Worldwide Cloud IDS/IPS Market to Surge at a 15.2% CAGR Through 2032
By pmarketresearch, 2026-08-12
PW Consulting Releases Worldwide Cloud IDS/IPS Market Report — A Strategic Playbook for 2026 Decision-Makers
PW Consulting today publishes its authoritative Worldwide Cloud IDS/IPS Market report, offering senior security and cloud leaders a pragmatic roadmap for decisions that will determine resiliency, economics, and compliance posture through the 2026 planning cycle and beyond. Built on a robust historical baseline (2020–2025) and a detailed seven-year forecast (2026–2032), the study quantifies a market expanding rapidly — driven by cloud-native adoption, distributed application architectures, and the operationalization of threat intelligence. The global market was approximately USD 2,850 Million in our 2025 base year and is projected to grow to roughly USD 7,673.8 Million by 2032, representing a compound annual growth rate of 15.2% over the forecast period.
Worldwide Media and Influencer Targeting Software Market
Why this report matters for 2026 strategy
-
Timing and confidence: Security procurement and architecture cycles in 2026 will be governed by shorter product lifecycles, accelerated cloud migration plans, and tighter capital discipline. Our report translates market trajectory into decision-ready timelines — helping CISOs and CIOs prioritize pilots, migrations, and vendor evaluations within the 12–36 month window when technology choice still matters most.
Worldwide Harbor Operations Software Market -
Cost and capacity realism: As cloud IDS/IPS becomes a continuous, traffic-sensitive function, hosting economics matter. The report aligns market growth with operational drivers — including the material rise in data center electricity demand and AI-driven workload growth — so finance and security teams can anticipate the real TCO implications of inline versus agent-based models and public versus private cloud placements.
Cord Blood Sealer Market -
Regulatory and procurement clarity: With shifting certification pathways and evolving data sovereignty rules, our analysis highlights the regulatory inflection points that will affect vendor selection, deployment topology, and contractual obligations in regulated industries and government procurement.
-
Competitive context without the noise: We provide a practical vendor landscape and capability mapping that illuminates where the market is consolidating and where specialist players are innovating — enabling buyers to fast-track shortlist decisions while preserving room to validate technical fit in PoC phases.
What the report contains — operational, practitioner-focused deliverables
-
Executive decision matrix: A concise framework that maps business objectives (risk reduction, compliance, cost control, speed-to-market) to technical options (cloud-native IDS, virtual appliances, host-based solutions, managed services), with recommended prioritization for 2026 procurement cycles.
-
Vendor capability playbooks: Actionable profiles and comparative criteria for leading and emerging suppliers — covering integration posture, threat intelligence sourcing, automation maturity, and managed service delivery models.
-
Implementation blueprints: Ready-to-adapt deployment patterns for common enterprise environments (greenfield cloud-native workloads, lift-and-shift migrations, multi-cloud orchestration, and regulated-sector hybrid deployments), including sample rule management workflows and escalation pathways.
-
TCO and energy sensitivity models: Interactive scenario analysis that quantifies how compute, traffic growth, and rising electricity demand influence per-GB inspection costs and the relative attractiveness of centralized versus distributed inspection points.
-
Procurement and contracting templates: Clauses and KPIs designed for 2026 realities (data locality, shared responsibility, SLAs for detection-to-response, and audit support), to reduce negotiation cycles and preserve operational flex.
-
Validation playbook and PoC templates: Test plans that emphasize adverse-case scenarios (lateral east-west traffic, encrypted flows, and AI-driven attack patterns), enabling buyers to validate detection efficacy and false-positive economics before deployment scale-up.
-
Risk and compliance compendium: A practical guide to mapping data sovereignty, sectoral localization rules, and recent certification changes into architectural constraints and vendor roadmaps.
Competitive landscape — who matters and why
The Cloud IDS/IPS market is maturing into a mix of large platform providers, cloud-native specialists, and security incumbents transitioning their portfolios. Market concentration is meaningful: the largest three firms account for a material share of vendor revenue, and the top five expand that concentration further — creating both integration advantages and strategic risk for buyers who prefer supplier diversity.
Key companies profiled in the report include platform leaders and specialists that matter to enterprise buyers in 2026:
-
Cisco Systems — brings cloud-native and hybrid IDS/IPS capabilities tightly integrated with its Secure Firewall and broader security platforms. Cisco’s strength is enterprise-grade integration and a broad installed base that eases operations for global deployments.
-
Fortinet — positions cloud-delivered IPS/IDS with AI-driven threat intelligence and scalable inspection engines, appealing to organizations seeking consolidated networking and security stacks.
-
Trend Micro — emphasizes automated rule management and one-click managed policy groups for major cloud marketplaces, simplifying deployment and ongoing tuning in public cloud environments.
-
Palo Alto Networks — integrates IDS/IPS functions into comprehensive cloud workload security, delivering unified prevention across network and host contexts.
-
Check Point, CrowdStrike, Zscaler, IBM Security, Microsoft, AWS, Google Cloud, Juniper, and Sophos — each brings differentiated strengths in threat telemetry, cloud platform integration, zero-trust positioning, or managed service delivery that will influence partner strategies and procurement choices.
Recent market activity referenced in the report underscores the pace of productization and cloud partnership strategies: Trend Micro’s partnership to offer one-click managed rule groups in major cloud marketplaces reduces operational friction for buyers; and new cloud firewall offerings embedding IDS/IPS functions reflect vendor moves to consolidate north-south and east-west protection in single consoles. These developments accelerate buyer value capture but also raise interoperability and lock-in considerations that the report helps negotiate.
Industry dynamics — energy, regulation, and deployment complexity
Beyond vendor capabilities, two structural forces will shape 2026 outcomes and are examined in depth:
-
Energy and operational cost pressures: Data center electricity demand rose markedly in recent years, driven by AI and heavy compute workloads. The report models how rising energy costs and power density constraints change the economics of continuous inline inspection versus sampled or host-based approaches, and how architects can optimize inspection placement to reduce marginal operational cost.
-
Regulatory and certification shifts: Notable changes in government testing and certification pathways — including the sunset and transition of legacy procurement lists — require security teams to rethink compliance roadmaps and validate alternative certification strategies. Meanwhile, data sovereignty and cross-border restrictions continue to impose architectural constraints for regulated industries and global enterprises.
Actionable recommendations for 2026 planning
-
Adopt a staged deployment strategy: Begin with focused PoCs in mission-critical but contained environments to validate detection efficacy and operational cost, then expand to high-risk east-west segments once rule automation proves effective.
-
Incorporate energy and TCO sensitivity into procurement: Require vendors to disclose inspection compute profiles and energy estimates, and include energy-adjusted TCO in bid evaluation to avoid surprise operational costs as workloads scale.
-
Prioritize interoperability and telemetry portability: Choose solutions that export normalized telemetry and support standardized APIs to avoid long-term lock-in and to enable multivendor analytics.
-
Plan for regulatory contingencies: Build deployment templates that can isolate data flows by jurisdiction and retain the option to localize inspection capabilities where sovereignty rules require it.
-
Use concentration-aware sourcing: Where supplier concentration introduces systemic risk, consider blended sourcing (platform + specialist) and diversify critical detection functions across different technology bases.
A final note — depth with discretion
PW Consulting’s Worldwide Cloud IDS/IPS Market report is intentionally designed as a practitioner’s playbook: it reveals the analytical frameworks, vendor comparisons, and scenario models you need to make confident 2026 decisions, while preserving sensitive subsegment intelligence for subscribers. The report demonstrates our deep quantitative modeling — anchored by the 2025 market baseline and a 15.2% CAGR to 2032 — and pairs it with operational templates and procurement-ready assets to shorten your time to value.
For procurement teams, security architects, and executive sponsors preparing 2026 budgets and roadmaps, this report reduces ambiguity and accelerates decision cycles. To access the full dataset, vendor scorecards, and PoC templates that underpin our strategic recommendations, please visit the PW Consulting report page for subscription and licensing information.
For detailed analysis of this topic, please visit the official page: Worldwide Cloud IDS IPS Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Predicts 18% CAGR — Worldwide Active Optical Cable & Extender Market to Reach USD 14.34 Billion by 2032
By pmarketresearch, 2026-08-12
Worldwide Active Optical Cable and Extender Market: Strategic Imperatives for 2026
As enterprises, cloud providers, and network equipment manufacturers enter a decisive build-out phase for AI-ready infrastructure, Active Optical Cables (AOCs) and optical extenders have moved from niche enablers to core strategic assets. PW Consulting’s latest market study projects the worldwide AOC and extender market to reach approximately USD 4.50 billion in 2025, accelerating to roughly USD 5.49 billion in 2026 and following an 18.0% compound annual growth rate through our 2026–2032 forecast horizon. This growth trajectory is not academic: it reshapes capital planning, supplier strategy, and product road maps for any organization that depends on high‑speed, low‑latency optical interconnects.
Cybersecurity Vulnerability Assessment Service Market
Why 2026 is a Strategic Inflection Point
The near-term market dynamics combine robust demand with supply-side scarcity and rapid technology transitions. Hyperscale cloud expansions, the spread of high-performance computing (HPC), densification for AI workloads, and shifting architectures such as co‑packaged optics are converging to create both opportunity and risk. The market’s growth rate implies that organizations delaying strategic choices in 2026 risk higher procurement costs, missed integration windows, and degraded competitive positioning.
Worldwide Back Office Automation Market
Executives should interpret the 18.0% CAGR not as mere growth, but as the pace of architectural change: capacity requirements, connector and form-factor standards, and supplier ecosystems will evolve quickly. Those who treat AOCs and extenders as commodity cables will find themselves constrained by lead-time bottlenecks and losing negotiating leverage with tier‑one suppliers.
Worldwide Intensified Cameras Market
What the PW Consulting Report Delivers — Practical, Transactional, and Decision‑Ready
- Market sizing and scenario forecasts calibrated to 2026 budget cycles and multi‑year capital plans, highlighting upside and downside demand paths.
- Actionable vendor assessment frameworks that translate technical capability into procurement scorecards and negotiating levers.
- Go‑to‑market playbooks for OEMs, system integrators, and hyperscalers — including channel strategies, warranty economics, and migration roadmaps for 400G/800G and beyond.
- Supply‑chain mitigation templates: dual‑sourcing roadmaps, safety‑stock heuristics, and long‑lead component hedging strategies tailored to optoelectronics constraints.
- Technology adoption timelines, showing pragmatic steps to prepare for co‑packaged optics, multicore fiber launches, and microLED light sources without disrupting current deployments.
- Regulatory and tariff impact worksheets for procurement teams, allowing quick recalculation of TCO under different trade and duties scenarios.
- M&A and partnership screening tools to prioritize targets and assess integration risk in a market where the top firms capture meaningful share but leave room for challengers.
In short, the report is built to be used inside planning cycles: it provides executable artifacts (models, templates, and checklists), not just descriptive charts.
Competitive Landscape — Who Moves First and Why It Matters
The market shows a moderate concentration: the top three players control a substantial but not dominant portion of revenues, and the top five expand that share meaningfully. This structure fosters a dynamic arena where established incumbents, specialized component suppliers, and cost‑focused manufacturers each play distinct roles.
- Corning Incorporated: Positioned to lead on density and AI‑centric interconnects, Corning’s investments in multicore fiber and micro‑cable architectures are a direct response to hyperscaler demand for space‑efficient, high‑bandwidth cabling.
- Broadcom Inc. and Coherent Corp. (formerly II‑VI / Finisar): These integrated‑component leaders influence platform adoption through chipset and transceiver road maps, enabling higher per‑link rates and tighter ecosystem control.
- Molex LLC, Amphenol Communications Solutions, TE Connectivity and similar assembly specialists: Their advantage is breadth — robust portfolios for enterprise, industrial and ruggedized use cases — enabling fast channel response and systems integration.
- Nimble, cost‑focused vendors from APAC: Shenzhen‑based and other regional manufacturers are critical to white‑box channels, offering strong price competition for high‑volume deployments and accelerating price pressure in standard configurations.
- Specialists such as Sumitomo Electric, Fujikura, 3M and Siemon: These players combine material science and connectivity expertise to support high‑reliability and regulated environments.
Recent product and research announcements crystallize competitive vectors: multicore fiber and micro‑cable solutions to improve rack density, and microLED‑based AOC prototypes aimed at reducing power and improving thermal profiles. These are not incremental — they influence procurement timing, lifecycle costing, and co‑engineering relationships between OEMs and hyperscalers.
Supply Chain & Pricing Dynamics: The Hidden Levers
Three less‑visible market mechanics will determine winners and losers in 2026:
- Bill of materials economics: Transceiver chipsets dominate the cost structure of an AOC, representing roughly two‑thirds of the bill of materials in many designs, while the fiber portion is comparatively small. That imbalance amplifies the commercial significance of chipset availability and supplier licensing terms.
- Price erosion and channel segmentation: Standard 100G AOC units continue to face annual price erosion in the low double digits, and there is a persistent large price delta between OEM‑coded modules and compatible white‑box equivalents. Procurement teams must balance short‑term savings against long‑term reliability and support costs.
- Component lead times and supply constraint: Critical optoelectronics — VCSELs, photodetectors and specialized driver ICs — are subject to extended lead times, with some configurations experiencing multi‑month deliveries. This reality makes forward planning and supplier cooperation essential.
Geopolitical and tariff pressures further complicate sourcing. In many procurement scenarios, tariff changes on electronic components materially alter project economics, and agile teams will want to maintain playbooks that can be executed within weeks, not months.
Prioritized Playbook for 2026 Decision‑Makers
Based on our analysis, PW Consulting recommends a prioritized set of actions for C‑suite leaders, procurement heads, and product strategists entering 2026:
- Embed optical interconnect strategy into capital planning: translate the projected growth and technology shifts into capacity investments and migration timelines aligned with your fiscal calendar.
- Shift from spot procurement to strategic supplier contracts: negotiate volume commitments that secure capacity for critical transceiver components while preserving flexibility for emerging form factors.
- Operationalize a two‑tier sourcing model: marry trusted tier‑one suppliers for mission‑critical paths with vetted white‑box partners for scale and price agility.
- Invest in co‑engineering partnerships: secure early access to multicore, micro‑cable and microLED innovations through joint development agreements to gain design wins rather than simply buying components.
- Quantify total cost of ownership (TCO) across scenarios: incorporate price erosion trajectories, warranty and replacement economics, and tariff contingencies into procurement decisions.
- Use M&A and alliance moves selectively: target technology suppliers that fill roadmap gaps (e.g., advanced lasers, driver ICs, or assembly automation) rather than purely revenue‑accretive targets.
- Operational resilience: build inventory buffers for long‑lead optoelectronic parts, adopt flexible manufacturing agreements, and simulate multi‑node failure scenarios into continuity plans.
- Compliance and sustainability: incorporate lifecycle and end‑of‑life plans early — not as an afterthought — to meet regulatory and customer expectations while limiting stranded asset risk.
How to Use This Report in Your 2026 Planning Cycle
PW Consulting’s study is structured to be directly executable in annual planning and vendor selection cycles. Use it to inform board‑level investment cases, to guide RFP specifications, and to prioritize product features and form‑factor roadmaps. For procurement organizations, the supply‑chain playbooks and contract templates can be implemented with minimal customization to reduce lead‑time risk and capture the benefits of scale as the market grows.
For technology teams, the adoption timelines and co‑engineering checklists clarify which emergent technologies warrant immediate pilots versus staged evaluation. For strategy and corporate development groups, our M&A screening filters accelerate target identification in a market where concentration is meaningful but not prohibitive — creating windows for well‑timed acquisitions or joint ventures.
Closing: Why This Market Demands Proactive Leadership
The AOC and extender market is at once high‑growth and technically nuanced. The projected expansion from an approximate USD 4.5 billion market in 2025 to a significantly larger market by 2032, combined with an 18.0% CAGR, will reshape procurement economics and architectural choices. The top tier of vendors capture a sizeable share of value, but the midpoint concentration leaves room for disruptors that can combine technical differentiation with supply resilience and competitive pricing.
This press release intentionally omits segment‑level breakdowns and granular vendor scoring — those are core proprietary insights in the full PW Consulting report, designed to power vendor selection, investment decisions, and strategic roadmaps. For executives building or defending a 2026 budget, the tactical assets in the full report — scenario models, supplier scorecards, and procurement playbooks — are designed to be directly executable.
To access the comprehensive dataset, dynamic models, and step‑by‑step playbooks that underlie these conclusions, visit PW Consulting’s Worldwide Active Optical Cable and Extender Market report page and download the full briefing. In a market moving this quickly, access to the right intelligence is the difference between leading the transition and reacting to it.
For detailed analysis of this topic, please visit the official page: Worldwide Active Optical Cable and Extender Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Thoracic Drainage Devices Market Set to Expand at a 6.48% CAGR Through 2032
By pmarketresearch, 2026-08-12
Worldwide Thoracic Drainage Devices Market — Strategic Insights for 2026 Decision-Making
PW Consulting’s new market brief on the Worldwide Thoracic Drainage Devices market delivers a focused, actionable intelligence package tailored for executive teams planning for 2026. Built on a 2020–2025 historical foundation with 2025 as the base year, the report projects the global market to grow from an estimated USD 940.0 Million in 2025 to a materially larger opportunity by the end of the 2026–2032 forecast window, reflecting a compound annual growth rate (CAGR) of 6.48%. These macro dynamics underscore a stable, expanding market that rewards targeted product differentiation, clinical evidence, and smart commercial execution.
Worldwide Light Therapy Lamp Market
Why this report matters for 2026 strategies
-
Actionable signal in a transitional market: As hospitals prioritize patient mobility, objective monitoring, and shorter lengths of stay, thoracic drainage is shifting from commodity consumables toward integrated digital and value-based solutions. The report translates those macro shifts into concrete commercial and product development plays.
Worldwide Brick Saws Market -
Regulatory clarity and risk mapping: Thoracic drainage devices in leading markets continue to be regulated primarily as Class II devices (510(k) pathway in the United States). Our regulatory surveillance and scenario planning equip clients to de-risk US market entries and post-market obligations.
Telemedicine Integrated Consultation Vehicle Market -
Commercial disruption ahead: Recent industry events — including product discontinuations and Class II recalls announced in 2025–2026, new 510(k) clearances for monitoring technologies, and active trade show launches — are already reshaping supply and procurement dynamics. The report translates these events into near-term competitive advantages and threat vectors.
-
Investment-grade diligence for M&A and partnerships: With moderate market concentration among leading players, the market is ripe for bolt-on acquisitions, technology licensing, and distribution reshuffles. We quantify concentration and provide deal-level playbooks without exposing proprietary segmentation detail here.
Key trends shaping the market in 2026
-
Digitalization: Objective air-leak monitoring and digital drainage platforms are transitioning from niche to mainstream applications. Digital systems offer quantifiable clinical benefits (earlier mobilization, standardized monitoring) and create recurring revenue through consumables, monitoring subscriptions, and service contracts.
-
Mobility and ambulatory care: Wearable and portable chest drainage designs are gaining traction as hospitals and health systems expand early-discharge and outpatient post-operative pathways. This trend changes procurement priorities from upfront device cost to total cost of care.
-
Regulatory and safety focus: Compliance with consensus electrical safety and performance standards remains a gating factor for digital devices entering core markets. Recall and discontinuation events in 2025–2026 have amplified buyer sensitivity to supplier stability and post-market surveillance rigor.
-
Value-based procurement and reimbursement nuance: Reimbursement coding and payment drivers — in particular CPT and DRG/APC constructs for thoracic procedures — are shaping hospital willingness to pay for higher-value drainage platforms that demonstrably reduce complications or length of stay.
-
Supply-chain and commercial realignment: Announced US commercial exits and product recalls create short- to medium-term distribution gaps that agile competitors and local manufacturers can exploit with rapid market access strategies.
Competitive landscape: strategic implications for incumbents and challengers
The competitive map includes a mix of global medtech leaders, specialized innovators, and regional manufacturers. Market concentration metrics indicate a moderately consolidating landscape, where the top tier of firms hold meaningful scale but room exists for well-positioned entrants and adjacencies.
-
Becton, Dickinson and Company (BD): A strong critical-care portfolio and established chest tube offerings position BD to defend installed base share. Strategic priorities should include converting hospitals to integrated consumable/service models and accelerating evidence generation on outcomes.
-
Getinge (Atrium brand): The Atrium line remains a staple for many cardiac and thoracic programs. Getinge’s existing product breadth allows cross-selling into cardiac surgery pathways; the strategic focus should be improving digital interfaces and mobile drain options.
-
Medela and ATMOS (digital platform leaders): Their digital systems demonstrate the clinical and workflow advantages buyers seek. Competitors must either partner with or replicate digital measurement capabilities — or offer differentiated service and analytics layers.
-
Cardinal Health: Recent decisions to discontinue certain chest drainage units in the US, followed by a Class 2 recall in early 2026, create immediate procurement voids. This represents an opportunity for competitors to capture share through rapid qualification and tender responsiveness, but also highlights the reputational and operational risks associated with product portfolio shifts.
-
Centese and other innovators: Automated clog clearance and intelligence-focused systems represent a meaningful technology inflection. Venture and corporate investors should monitor regulatory milestones and hospital pilots as precursors to scaling opportunities.
-
Regional manufacturers (e.g., Vygon, Redax, Sinapi, Sterimed, Angiplast): Cost-competitive and specialty offerings from regional players cater to differentiated price and service requirements. Strategic alliances between global platform providers and regional manufacturers can accelerate market coverage while optimizing cost structures.
What the PW Consulting report contains — practical modules for 2026 execution
-
Executive dashboard: concise decision-grade KPIs (market size trajectory, growth drivers, concentration indices) and scenario-impact summaries for board-level briefings.
-
Market sizing & forecast model: base-year calibration (2025) and granular forecast engine for 2026–2032 with sensitivity levers. Note: detailed subsegment tables (region, application, product) are included in the report download to support GTM and financial planning — we intentionally withhold those line-item tables in this summary to preserve the strategic value of the full research package.
-
Regulatory and reimbursement playbook: pathway maps for 510(k) filings, common consensus standards, and CPT/DRG/APC considerations that influence purchasing decisions in the hospital setting.
-
Competitive heatmaps and capability matrices: side-by-side profiles, go-to-market footprints, and innovation roadmaps for the leading and up-and-coming players.
-
Commercial playbooks and tender templates: customer segmentation, price-tier strategies, pilot design templates, modality-specific ROI calculators, and contract negotiation checklists tailored to health system buying behaviors.
-
Scenario and sensitivity workshops: three practical scenarios (baseline, accelerated digital adoption, and supply-disruption) with quantified P&L and market-share implications to guide resource allocation.
-
Implementation support tools: KPI trackers, post-launch monitoring templates, and recommended clinical-evidence generation plans (study designs, endpoints, and timelines) for purchasers and suppliers.
Recommended strategic moves for 2026
-
Incumbents should prioritize modular digital upgrades and service contracts to convert one-time purchasers into recurring revenue relationships. Track clinical endpoints tied to length of stay and readmission as procurement levers.
-
Challengers and innovators must focus on rapid 510(k) strategies, selective clinical pilots with high-volume thoracic programs, and interoperability with electronic medical records to accelerate adoption.
-
Distributors and smaller manufacturers should target urgent coverage opportunities arising from supplier exits and recalls, using local regulatory agility and rapid fulfillment as competitive advantage.
-
Private equity and strategic buyers should prioritize assets that provide digital analytics, consumable lock-in, or access to high-volume cardiac/thoracic centers — these attributes materially enhance multiple expansion potential.
-
Health systems and procurement organizations should redesign tender criteria to emphasize total cost of care, evidence of reduced complications, and supplier continuity plans.
Risk factors and regulatory watch for 2026
-
Post-market obligations: Recent recalls and discontinuations underscore the need for robust quality systems and contingency planning. Buyers will increasingly prefer suppliers with visible post-market surveillance and service commitments.
-
510(k) landscape: Devices relying on incremental engineering changes must prepare for more rigorous predicate scrutiny. New entrants should budget for additional clinical or bench testing to accelerate clearance.
-
Reimbursement sensitivity: Changes in procedure coding, APC levels, or DRG logic can alter hospital economics quickly. Companies should model multiple reimbursement scenarios in pricing and evidence generation plans.
-
Procurement concentration risk: A moderate share held by the top competitors suggests potential consolidation-driven pricing pressure; nimble firms can exploit short-term dislocations if they have execution discipline.
How PW Consulting supports 2026 implementation
Our advisory offering combines the market intelligence in this report with hands-on program execution: competitive response blueprints, due diligence packages, regulatory support mapping for 510(k) pathways, and tailored clinical study design to accelerate adoption. Clients benefit from both the strategic vantage and the operational toolkits (e.g., tender templates, ROI calculators) necessary to convert insight into market share.
For decision-makers planning 2026 initiatives, this report functions as both compass and playbook: it quantifies the growth runway, synthesizes regulatory and reimbursement constraints, and prescribes prioritized actions that protect margin while capturing growth. To access the full dataset, regional and application breakdowns, company-by-company market shares, and downloadable financial models, please visit the PW Consulting report page — the detailed annex contains the proprietary segmentation tables and deal-level guidance we intentionally hold back from summary circulation.
PW Consulting remains available to brief investor committees, boards, and executive leadership teams on how these insights translate into executable 12–24 month plans that align product roadmaps, sales incentives, and M&A targets with the unfolding market reality in 2026.
For detailed analysis of this topic, please visit the official page: Worldwide Thoracic Drainage Devices Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecast: Worldwide CNS Stimulants Market Poised for a 6.25% CAGR Through 2032
By pmarketresearch, 2026-08-12
Strategic Preview: Worldwide CNS Stimulants Market — Preparing Pharma Leadership for 2026
PW Consulting’s latest market study on Worldwide Central Nervous System (CNS) Stimulants synthesizes market-scale dynamics, regulatory inflection points and competitive moves into an actionable roadmap for executive decision-making in 2026. Anchored on a 2025 base year and projecting through 2032, our model shows the global CNS stimulants market expanding at a compound annual growth rate (CAGR) of 6.25% (USD, revenue unit: Million). The market has grown from the mid‑2020s through 2025 and, under our base scenario, continues a steady expansion into 2032—driven by persistent ADHD demand, therapeutic diversification, and formulation-driven lifecycle management.
Worldwide Brassinolide Market
Why this report matters for 2026 strategy
-
Decisions in 2026 must account for a market that is simultaneously mature and dynamically reshaping: incumbent brand equity and extensive generic penetration coexist with product-level innovation (delivery systems, prodrugs, delayed‑release platforms) and renewed regulatory scrutiny. Our analysis translates these tensions into strategic imperatives for pipeline prioritization, manufacturing investments, and commercial go‑to‑market sequencing.
Worldwide Cryptocurrency Software Market -
Regulatory and supply constraints affecting Schedule II stimulants are not one‑off disruptions but structural variables that will influence capacity planning, contract manufacturing relationships and geographic launch priorities. The report quantifies the likely market impact of these variables under alternative regulatory and supply scenarios, enabling financial teams to stress‑test forecasts and procurement groups to prioritize resilience investments.
Worldwide Dental Fluoride Varnish Market -
For commercial leadership, the report benchmarks competitive positioning across originator, authorized‑generic and pure‑play generic players, and provides playbooks for formulary negotiations, specialty channel deployment and lifecycle extensions that maintain profitability in a pricing‑sensitive environment.
What the topline numbers tell you (and what they don’t)
PW Consulting’s market model provides year‑by‑year revenue projections from 2023 through 2032 (USD Million). It captures recent acceleration into 2025 and a projected continuance of growth into 2032 consistent with the 6.25% CAGR. These topline trajectories reflect demand persistence for core ADHD and narcolepsy indications, incremental uptake of new formulations and steady replacement/renewal cycles in chronic use populations.
As a “trailer” for our proprietary dataset, we surface the macro growth trajectory to inform board‑level resource allocation without publishing the granular regional, drug‑type and indication splits contained in the full report. Clients who need segment‑level revenue, market share tables, or the scenario outputs that translate quota shifts, label changes and supply interruptions into P&L impacts should consult the complete research pack.
Regulatory and supply dynamics shaping 2026 choices
-
Heightened regulatory focus. Recent regulatory actions have materially altered product risk/benefit communication: in mid‑2025, regulators mandated expanded pediatric warnings for extended‑release amphetamine and methylphenidate products. That label evolution directly affects pediatric prescribing patterns and the commercial case for pediatric label expansion programs. Teams must update clinical development and pharmacovigilance strategies to accommodate heightened safety surveillance and potential labeling constraints.
-
Controlled‑substance production quotas. Aggregate production quotas have been adjusted upward in response to manufacturer requests, reflecting underlying demand and supply negotiations with regulators. These quota dynamics become strategic levers—especially for originators and large generics—that can be used to smooth supply or to secure short‑term competitive advantage. Our scenario module maps quota outcomes to market availability and price volatility under multiple regulatory response assumptions.
-
Persistent API and finished‑product constraints. Global API concentration and downstream manufacturing bottlenecks continue to produce intermittent shortages, notably among immediate‑release amphetamine salts. The 2026 environment therefore favors companies with diversified sourcing, redundant manufacturing footprints, or long‑dated supply agreements. Manufacturers should prioritize capital allocation to strategic capacity, and payers/pharmacies should assess contingency protocols to avoid therapy disruption.
-
Quality assurance signals. Quality surveillance outcomes matter: publicly reported FDA quality testing in early 2026 confirmed acceptable results for certain extended‑release methylphenidate products from leading generics manufacturers. This kind of verification reduces short‑term market risk for specific suppliers and can influence procurement choices among health systems and group purchasing organizations.
Competitive landscape: reading the signal from established and emerging players
The CNS stimulants category is populated by a spectrum of players: multinational originators with branded franchises, large generic manufacturers with scale supply capabilities, and smaller firms focused on formulation innovation and niche delivery technologies. Our competitive assessment highlights several strategic archetypes present in the marketplace:
-
Originator franchises leveraging formulation differentiation: Major multinational companies continue to protect and extend branded assets through extended‑release platforms, prodrug approaches and time‑of‑day targeting. These plays are supported by strong regulatory and commercial infrastructures and permit premium pricing in managed markets with favorable reimbursement.
-
Scale generics and contract manufacturers: Large generic manufacturers and specialty producers remain the backbone of volume supply, particularly in mature markets. Their strategic focus is on manufacturing efficiency, portfolio breadth and rapid biosimilar‑style launch readiness when exclusivities expire. Manufacturing quality verification events in 2026 are a positive signal for these players’ market access.
-
Formulation specialists and delivery innovators: Smaller, agile companies are capturing value through novel delivery systems (liquid formulations, transdermal patches, delayed‑release evening dosing) and prodrug technologies that modify abuse potential and dosing cadence. These capabilities are attractive to payers when they reduce administration burden or improve adherence.
Beyond pure therapeutic competition, the category is shaped by shifting payer dynamics and regulatory engagement. Our competitor dossiers evaluate commercial strengths, manufacturing footprints, patent cliffs, partnership activity and clinical pipelines for the leading firms in the space. For clients considering collaborations, M&A or licensing, those dossiers create an actionable shortlist calibrated to 2026 market realities.
Strategic implications and playbook for 2026 decision‑makers
PW Consulting’s research distills market forces into a compact strategic playbook tailored for executive teams preparing budgets, capital plans and product roadmaps in 2026. Key recommendations include:
-
Adopt scenario‑based demand planning that integrates quota variability and label changes. Build a matrix of likely regulatory outcomes and tie these to procurement, manufacturing ramp‑up schedules and launch timing decisions.
-
Invest selectively in supply chain resilience: prioritize API diversification, capacity redundancy in finished‑dose production, and long‑term supply agreements with validated manufacturers to reduce exposure to episodic shortages.
-
Prioritize formulation differentiation that addresses payer and end‑user pain points: convenience, adherence, abuse‑deterrent/prodrug designs and pediatric suitability will command attention from formulary committees and prescribers.
-
Prepare reimbursement rationales mapped to evolving pricing paradigms. With pricing models and benchmarking pilot programs under discussion in major markets, companies must document value through real‑world evidence, pharmacoeconomic models and targeted outcomes studies.
-
Leverage regulatory intelligence as a competitive asset. Proactive engagement with regulators on labeling language, pediatric risk mitigation, and post‑marketing surveillance programs can reduce time‑to‑market and improve acceptance of new formulations.
-
Shape M&A and partnership strategies around asymmetric advantages: originators seeking manufacturing scale should prioritize targets with validated GMP facilities; smaller developers with differentiated delivery systems should seek partners offering payer access and commercialization infrastructure.
Report contents — practical deliverables you can use in 2026
The full PW Consulting report is designed for operational use by commercial, regulatory, R&D and M&A teams. Key deliverables include:
-
A transparent market model (2020–2032) with downloadable spreadsheets and scenario toggles for regulatory, supply and reimbursement shocks.
-
Region‑ and indication‑level forecasts (with sensitivity bands) and a methodology appendix describing data sources and assumptions.
-
Proprietary supplier risk heatmaps that identify API concentration, single‑site dependencies and likely shortage triggers.
-
Company profiles and comparative scorecards covering manufacturing quality, commercial reach, pipeline differentiation and likely post‑patent competition timing.
-
Actionable go‑to‑market playbooks for branded launches, authorized generics, and generic‑only market entry strategies.
-
Regulatory tracker and policy impact assessments, including quantified P&L impacts for plausible labeling and quota scenarios.
Conclusion — preparing to act, not just to observe
As the CNS stimulants market moves into 2026, executives face a landscape of predictable growth but compound uncertainty: regulatory tightening, quota mechanics, supply chain fragility and evolving reimbursement frameworks. PW Consulting’s study converts that complexity into a structured set of choices—prioritizing resilience, formulation innovation and payer‑facing evidence generation.
Our preview has revealed the macro growth path and the strategic contours leaders must consider. For stakeholders who require the granular segmentation, regional breakdowns, and the full suite of model outputs that drive transaction and operational decisions, the complete report provides the necessary depth and downloadable tools to act with confidence. PW Consulting stands ready to partner on bespoke scenario analysis, M&A diligence and implementation roadmaps tailored to your 2026 strategic plan.
For detailed analysis of this topic, please visit the official page: Worldwide Central Nervous System (CNS) Stimulants Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Predicts Worldwide Adult Ventricular Assist Device Market to Grow at a 5.81% CAGR from 2026–2032
By pmarketresearch, 2026-08-12
Worldwide Adult Ventricular Assist Device Market — Strategic Preview for 2026 Decision‑Makers
PW Consulting’s new market intelligence briefing frames the adult ventricular assist device (VAD) landscape at a pivotal inflection point. Our analysis projects continuing expansion from an estimated global market size of USD 1,845.5 Million in 2025 to roughly USD 1,941.1 Million in 2026, with a compound annual growth rate (CAGR) of 5.81% through our 2026–2032 forecast horizon and a 2032 market projection of approximately USD 2,742.1 Million. These headline metrics underscore steady, clinically driven growth against a backdrop of regulatory tightening, concentrated competition, and accelerating technology transitions — factors that will determine winners and losers in corporate strategies executed in 2026.
Worldwide Money Insurance Market
Key findings at a glance
-
Resilient market growth: The adult VAD market has expanded materially over the last half‑decade and, per our base case, will continue to grow at a mid‑single digit CAGR out to 2032. This growth is powered by broader adoption of destination therapy, incremental clinical evidence supporting newer centrifugal technologies, and incremental reimbursement alignment in developed markets.
Worldwide Tubing Connections Market -
High concentration, high stakes: Market concentration is pronounced — the top three companies control the overwhelming majority of market revenue, and the top five exceed 90%. This concentration compresses commoditization risk while magnifying the strategic impact of clinical data, recall risk, and regulatory approvals.
Worldwide Melaleuca Oil Market -
Clinical evidence moves markets: Long‑term trial results and real‑world registries are the single most influential determinant of device uptake and payer acceptance. Recent five‑year data for a leading centrifugal LVAD have materially reinforced its commercial position; conversely, device recalls and advisories have precipitated rapid share shifts and created white‑space opportunities for agile competitors.
-
Regulatory and reimbursement complexity: VADs remain Class III devices in the U.S., with PMA processes and evolving European MDR requirements shaping time‑to‑market and post‑market burdens. Simultaneously, recent updates to hospital billing codes and DRG payments in key markets are modifying provider economics and center‑level adoption incentives.
-
Adjacencies and alternatives: Total artificial hearts, percutaneous temporary devices, and improvements in heart failure medical therapy are creating nuanced competitive and complementary dynamics. For incumbent manufacturers the strategic question is whether to focus on incremental LVAD improvements, adjacent device platforms, or service‑led care pathways.
Why this report matters for 2026 strategic decisions
-
M&A screening and diligence: With a highly concentrated market and clear regulatory hurdles, valuation asymmetries will arise from differential clinical evidence and regulatory status. Our report provides a triage framework for identifying targets where regulatory runway, clinical data, or service economics can be de‑risked within a two‑year M&A horizon.
-
Product portfolio prioritization: R&D budgets must be triaged between incremental device improvements (e.g., hemocompatibility, energy efficiency), controller ecosystems, and adjacent platforms such as total artificial hearts. We map the clinical and commercial returns across these investment choices under multiple adoption scenarios.
-
Market access and reimbursement strategy: Payers and hospitals are tightening adoption criteria. Our payer models simulate the impact of specific DRG and CPT updates on provider margins and forecast likely shifts in center of excellence behavior — essential inputs when negotiating hospital contracts or piloting new reimbursement pathways.
-
Commercial strategy and channel design: The capital‑intensive, service‑heavy nature of VAD programs rewards sophisticated field playbooks. The report prescribes sales coverage models, training and servicing KPIs, and partnership archetypes (e.g., implant center alliances, leasing/consignment models) that improve conversion and lifetime value.
-
Clinical development planning: Trial design choices (endpoint selection, non‑inferiority margins, registry‑augmented approaches) materially shift time‑to‑label and market uptake. We provide protocol optimization checklists that reconcile regulatory expectations with real‑world adoption drivers.
Competitive dynamics — what to watch in 2026
-
Abbott Laboratories — execution through evidence: Abbott’s centrifugal LVAD platform remains a commercial anchor for organizations seeking durable destination therapy options. Recent multi‑year trial results showing meaningful survival and neurological outcomes have fortified its commercial position; for competitors, matching or exceeding that evidence is a prerequisite for displacement.
-
Medtronic — recall legacy and strategic choices: The recall and clinical advisory surrounding one of Medtronic’s centrifugal systems have constrained new implantations in several markets and reshaped the competitive field. Ongoing support obligations and liability considerations continue to influence hospital procurement decisions and present strategic openings for other manufacturers.
-
LivaNova — regional thrust and next‑generation centrifugal entrants: CE Mark progress and commercial launches across Europe illustrate a viable pathway to scale for newer centrifugal designs. For multinational players, timing and sequencing of regulatory clearances will dictate when and where to press advantage or defend ground.
-
Berlin Heart and Syncardia — niche and adjunct strategies: External pneumatic devices and total artificial heart platforms serve important clinical niches — specifically in biventricular failure or implant‑ineligible patients. These therapies underscore the importance of service, specialized training, and referral network stewardship rather than pure product competition.
-
Implication: consolidation and co‑opetition: Expect continued consolidation among devices, supply chain partners, and service providers. Strategic partnerships (manufacturing, digital health, consumables management) will be decisive for scaling programs and extracting service revenue beyond the implant.
Regulatory and reimbursement dynamics shaping 2026 strategies
-
Regulation: Adult VADs remain Class III devices under U.S. regulation and require PMA pathways, with the European MDR imposing rigorous Annex II conformity assessment and enhanced post‑market surveillance obligations.
-
Reimbursement: Recent payer actions — including an updated DRG for LVAD implants and changes to procedural coding that recognize new approaches — are already influencing hospital economics and may accelerate or decelerate regional adoption depending on pathway design.
-
Recall risk: Device advisories and class I recalls have immediate commercial fallout. Companies must pair device engineering plans with rapid-response clinical and communications playbooks to protect center relationships and minimize attrition.
What the full PW Consulting report delivers (practical components)
-
Demand forecasting package: Transparent top‑down and bottom‑up models with scenario sensitivity (base, upside, downside) covering 2026–2032 and incorporating epidemiology, center capacity, and payer dynamics.
-
Commercial playbooks: Market entry and expansion templates for incumbents, challengers, and new entrants — including sample KPIs, training curricula, and consumables pricing strategies.
-
Regulatory roadmap and time‑to‑market planning: Country‑level approval timelines, required clinical endpoints, and PMA/Notified Body considerations that materially affect launch sequencing and resource allocation.
-
Reimbursement impact models: Provider margin simulations under DRG and CPT updates to estimate adoption thresholds across hospital archetypes and payer mixes.
-
Competitive deep dives: Strategic profiles and recent development summaries for the leading players, with implications for partners, suppliers, and acquirers.
-
M&A and partnership screening tool: Valuation heuristics and a short list of candidate assets/categories prioritized for strategic buyers and private equity sponsors.
-
Operational readiness checklist: Manufacturing scale considerations, aftermarket service models, and supply chain vulnerabilities critical to sustaining growth in 2026 and beyond.
Methodology and credibility
Our findings are grounded in a blended research approach: primary interviews with clinical and procurement leaders at implant centers, detailed billing and claims analysis, device registry and trial outcome synthesis, and a proprietary forecasting engine that triangulates epidemiology, center capacity, and historical adoption curves from 2020–2025. We validate outputs through sensitivity testing and scenario analysis to reflect regulatory shocks, evidence inflection points, and reimbursement changes. To preserve tactical value for clients, this public summary is deliberately high‑level; the full report contains the supporting datasets, model logic, and payoff matrices used to generate our projections.
Next steps for executives and investors
-
Prioritize clinical evidence programs that target durable survival and neurological outcomes — these are the single biggest determinant of payer coverage and center preference.
-
Build dual pathways for growth: defend core centrifugal platforms while exploring adjacent service and total‑heart solutions that capture unmet clinical segments.
-
Stress‑test M&A opportunities against regulatory timelines and recall‑scenario contingencies — integration plans should explicitly cover post‑market surveillance and product liability drag.
-
Engage payers early with real‑world evidence frameworks and hospital pilots aligned to updated DRG/CPT mechanics to accelerate adoption at reference centers.
PW Consulting’s Worldwide Adult Ventricular Assist Device Market report is designed as an executable intelligence product for leadership teams setting 2026 priorities. To access the full dataset, segmentation detail, executable playbooks, and proprietary models referenced in this briefing — including the granular regional and application splits withheld here to preserve strategic value — visit the PW Consulting report landing page or contact our advisory team to arrange a briefing and demonstration.
For detailed analysis of this topic, please visit the official page: Worldwide Adult Ventricular Assist Device Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com