

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Thoracic Drainage Devices Market Set to Expand at a 6.48% CAGR Through 2032

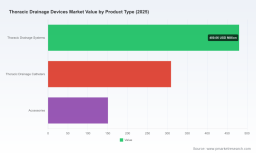
Worldwide Thoracic Drainage Devices Market — Strategic Insights for 2026 Decision-Making
PW Consulting’s new market brief on the Worldwide Thoracic Drainage Devices market delivers a focused, actionable intelligence package tailored for executive teams planning for 2026. Built on a 2020–2025 historical foundation with 2025 as the base year, the report projects the global market to grow from an estimated USD 940.0 Million in 2025 to a materially larger opportunity by the end of the 2026–2032 forecast window, reflecting a compound annual growth rate (CAGR) of 6.48%. These macro dynamics underscore a stable, expanding market that rewards targeted product differentiation, clinical evidence, and smart commercial execution.
Worldwide Light Therapy Lamp Market
Why this report matters for 2026 strategies
-
Actionable signal in a transitional market: As hospitals prioritize patient mobility, objective monitoring, and shorter lengths of stay, thoracic drainage is shifting from commodity consumables toward integrated digital and value-based solutions. The report translates those macro shifts into concrete commercial and product development plays.
Worldwide Brick Saws Market -
Regulatory clarity and risk mapping: Thoracic drainage devices in leading markets continue to be regulated primarily as Class II devices (510(k) pathway in the United States). Our regulatory surveillance and scenario planning equip clients to de-risk US market entries and post-market obligations.
Telemedicine Integrated Consultation Vehicle Market -
Commercial disruption ahead: Recent industry events — including product discontinuations and Class II recalls announced in 2025–2026, new 510(k) clearances for monitoring technologies, and active trade show launches — are already reshaping supply and procurement dynamics. The report translates these events into near-term competitive advantages and threat vectors.
-
Investment-grade diligence for M&A and partnerships: With moderate market concentration among leading players, the market is ripe for bolt-on acquisitions, technology licensing, and distribution reshuffles. We quantify concentration and provide deal-level playbooks without exposing proprietary segmentation detail here.
Key trends shaping the market in 2026
-
Digitalization: Objective air-leak monitoring and digital drainage platforms are transitioning from niche to mainstream applications. Digital systems offer quantifiable clinical benefits (earlier mobilization, standardized monitoring) and create recurring revenue through consumables, monitoring subscriptions, and service contracts.
-
Mobility and ambulatory care: Wearable and portable chest drainage designs are gaining traction as hospitals and health systems expand early-discharge and outpatient post-operative pathways. This trend changes procurement priorities from upfront device cost to total cost of care.
-
Regulatory and safety focus: Compliance with consensus electrical safety and performance standards remains a gating factor for digital devices entering core markets. Recall and discontinuation events in 2025–2026 have amplified buyer sensitivity to supplier stability and post-market surveillance rigor.
-
Value-based procurement and reimbursement nuance: Reimbursement coding and payment drivers — in particular CPT and DRG/APC constructs for thoracic procedures — are shaping hospital willingness to pay for higher-value drainage platforms that demonstrably reduce complications or length of stay.
-
Supply-chain and commercial realignment: Announced US commercial exits and product recalls create short- to medium-term distribution gaps that agile competitors and local manufacturers can exploit with rapid market access strategies.
Competitive landscape: strategic implications for incumbents and challengers
The competitive map includes a mix of global medtech leaders, specialized innovators, and regional manufacturers. Market concentration metrics indicate a moderately consolidating landscape, where the top tier of firms hold meaningful scale but room exists for well-positioned entrants and adjacencies.
-
Becton, Dickinson and Company (BD): A strong critical-care portfolio and established chest tube offerings position BD to defend installed base share. Strategic priorities should include converting hospitals to integrated consumable/service models and accelerating evidence generation on outcomes.
-
Getinge (Atrium brand): The Atrium line remains a staple for many cardiac and thoracic programs. Getinge’s existing product breadth allows cross-selling into cardiac surgery pathways; the strategic focus should be improving digital interfaces and mobile drain options.
-
Medela and ATMOS (digital platform leaders): Their digital systems demonstrate the clinical and workflow advantages buyers seek. Competitors must either partner with or replicate digital measurement capabilities — or offer differentiated service and analytics layers.
-
Cardinal Health: Recent decisions to discontinue certain chest drainage units in the US, followed by a Class 2 recall in early 2026, create immediate procurement voids. This represents an opportunity for competitors to capture share through rapid qualification and tender responsiveness, but also highlights the reputational and operational risks associated with product portfolio shifts.
-
Centese and other innovators: Automated clog clearance and intelligence-focused systems represent a meaningful technology inflection. Venture and corporate investors should monitor regulatory milestones and hospital pilots as precursors to scaling opportunities.
-
Regional manufacturers (e.g., Vygon, Redax, Sinapi, Sterimed, Angiplast): Cost-competitive and specialty offerings from regional players cater to differentiated price and service requirements. Strategic alliances between global platform providers and regional manufacturers can accelerate market coverage while optimizing cost structures.
What the PW Consulting report contains — practical modules for 2026 execution
-
Executive dashboard: concise decision-grade KPIs (market size trajectory, growth drivers, concentration indices) and scenario-impact summaries for board-level briefings.
-
Market sizing & forecast model: base-year calibration (2025) and granular forecast engine for 2026–2032 with sensitivity levers. Note: detailed subsegment tables (region, application, product) are included in the report download to support GTM and financial planning — we intentionally withhold those line-item tables in this summary to preserve the strategic value of the full research package.
-
Regulatory and reimbursement playbook: pathway maps for 510(k) filings, common consensus standards, and CPT/DRG/APC considerations that influence purchasing decisions in the hospital setting.
-
Competitive heatmaps and capability matrices: side-by-side profiles, go-to-market footprints, and innovation roadmaps for the leading and up-and-coming players.
-
Commercial playbooks and tender templates: customer segmentation, price-tier strategies, pilot design templates, modality-specific ROI calculators, and contract negotiation checklists tailored to health system buying behaviors.
-
Scenario and sensitivity workshops: three practical scenarios (baseline, accelerated digital adoption, and supply-disruption) with quantified P&L and market-share implications to guide resource allocation.
-
Implementation support tools: KPI trackers, post-launch monitoring templates, and recommended clinical-evidence generation plans (study designs, endpoints, and timelines) for purchasers and suppliers.
Recommended strategic moves for 2026
-
Incumbents should prioritize modular digital upgrades and service contracts to convert one-time purchasers into recurring revenue relationships. Track clinical endpoints tied to length of stay and readmission as procurement levers.
-
Challengers and innovators must focus on rapid 510(k) strategies, selective clinical pilots with high-volume thoracic programs, and interoperability with electronic medical records to accelerate adoption.
-
Distributors and smaller manufacturers should target urgent coverage opportunities arising from supplier exits and recalls, using local regulatory agility and rapid fulfillment as competitive advantage.
-
Private equity and strategic buyers should prioritize assets that provide digital analytics, consumable lock-in, or access to high-volume cardiac/thoracic centers — these attributes materially enhance multiple expansion potential.
-
Health systems and procurement organizations should redesign tender criteria to emphasize total cost of care, evidence of reduced complications, and supplier continuity plans.
Risk factors and regulatory watch for 2026
-
Post-market obligations: Recent recalls and discontinuations underscore the need for robust quality systems and contingency planning. Buyers will increasingly prefer suppliers with visible post-market surveillance and service commitments.
-
510(k) landscape: Devices relying on incremental engineering changes must prepare for more rigorous predicate scrutiny. New entrants should budget for additional clinical or bench testing to accelerate clearance.
-
Reimbursement sensitivity: Changes in procedure coding, APC levels, or DRG logic can alter hospital economics quickly. Companies should model multiple reimbursement scenarios in pricing and evidence generation plans.
-
Procurement concentration risk: A moderate share held by the top competitors suggests potential consolidation-driven pricing pressure; nimble firms can exploit short-term dislocations if they have execution discipline.
How PW Consulting supports 2026 implementation
Our advisory offering combines the market intelligence in this report with hands-on program execution: competitive response blueprints, due diligence packages, regulatory support mapping for 510(k) pathways, and tailored clinical study design to accelerate adoption. Clients benefit from both the strategic vantage and the operational toolkits (e.g., tender templates, ROI calculators) necessary to convert insight into market share.
For decision-makers planning 2026 initiatives, this report functions as both compass and playbook: it quantifies the growth runway, synthesizes regulatory and reimbursement constraints, and prescribes prioritized actions that protect margin while capturing growth. To access the full dataset, regional and application breakdowns, company-by-company market shares, and downloadable financial models, please visit the PW Consulting report page — the detailed annex contains the proprietary segmentation tables and deal-level guidance we intentionally hold back from summary circulation.
PW Consulting remains available to brief investor committees, boards, and executive leadership teams on how these insights translate into executable 12–24 month plans that align product roadmaps, sales incentives, and M&A targets with the unfolding market reality in 2026.
For detailed analysis of this topic, please visit the official page: Worldwide Thoracic Drainage Devices Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com