

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Wearable Injectors Market to Reach USD 22,323.33 Million by 2032 at a 13.5% CAGR

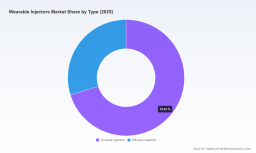
Worldwide Wearable Injectors Market: Strategic Imperatives for 2026 — PW Consulting Insights
As wearable injectors transition from niche innovation to mainstream delivery platforms, 2026 represents a decisive year for commercial teams, device manufacturers, and strategic investors. PW Consulting’s latest market study — anchored on a 2025 base year and projecting through 2032 — quantifies a striking trajectory: the global market more than doubled in five years to USD 9,200 Million in 2025 and is set to surpass USD 10,900 Million in 2026, with a forecast compound annual growth rate (CAGR) of 13.5% across the 2026–2032 horizon. This growth is accompanied by increased market concentration (CR3 ~55.4%; CR5 ~72.8%), maturing regulatory clarity, and accelerating payer engagement — forces that together define a narrow window of opportunity for first movers and fast followers.
Lead-acid Battery for Telecom Base Station Market
Why 2026 Decisions Will Define Multi-Year Outcomes
-
Adoption inflection: Clinical evidence packages and human factors work completed in 2024–2025 are starting to unlock regulatory clearances and commercial launches. The coming year will separate organizations that can operationalize commercialization from those still optimizing R&D.
Next Generation Managed Security Service Market -
Commercial tooling and reimbursement alignment: With clearer billing pathways emerging, notably specific HCPCS codes that can be applied to wearable injector supplies under Medicare Part B, manufacturers who align product design, labeling, and coding strategies now will accelerate time-to-market and reimbursement capture.
Solar-Powered Water Pump Inverters Market -
Consolidation and partnering: A concentrated supplier base means that strategic partnerships — licensing, co-development, or commercialization agreements — will materially shape access to scale. The reported CR3/CR5 levels indicate that a handful of players already control substantial share, raising the stakes for alliance-making in 2026.
What the PW Consulting Report Delivers — Practically
Our research is designed to be operational from day one. The report is deliberately structured to translate intelligence into executable plans, without requiring readers to distill raw data into strategy themselves. Key deliverables include:
-
Market sizing and scenario models calibrated to the 2025 base year and spanning 2026–2032, with alternative uptake assumptions (conservative, base, accelerated) and sensitivity levers for pricing, penetration, and reimbursement.
-
Go-to-market playbooks tailored for device OEMs, pharma partners, and contract manufacturers: channel strategies, launch sequencing, field force deployment, and sample-to-prescription conversion frameworks.
-
Commercial due diligence templates and NPV models for M&A and partnership negotiations, including break-even timelines, dilution scenarios, and milestone structuring guidance.
-
Regulatory and clinical path maps covering device standards, key submission strategies, and human factors evidence aligned to ISO and IEC requirements.
-
Reimbursement and pricing roadmaps that integrate payer segmentation, coding strategies, and warranty/service models to protect margin while supporting adoption.
-
Supply-chain risk heatmaps — from resin pricing to electronics sourcing — with mitigation playbooks and supplier scorecards to preserve time-to-volume.
-
Competitive landscaping with capability matrices, partnership mappings, and likely strategic trajectories for the leading players (teaser level; segment-level share tables are reserved for the full report).
Competitive Landscape — Who Matters and Why
The wearable injector arena is dominated by a mix of specialized device OEMs and strategic supply partners. PW Consulting’s analysis highlights several companies whose actions in 2024–2025 materially shift competitive dynamics:
-
Ypsomed (Switzerland) — A leader in on-body systems with platforms designed for large-volume subcutaneous delivery. Their October 2025 launch of an enhanced connectivity-enabled SmartPilot marks a deliberate push to convert digital telemetry into clinical and commercial value, improving adherence verification and real-time dosing visibility for pharma partners.
-
West Pharmaceutical Services (USA) — With a strong platform approach and deep commercial relationships, West announced a major commercial supply agreement in March 2025 that signals confidence among top-tier pharma customers in the SmartDose platform. West’s scale positions it as an attractive partner for companies seeking rapid commercialization.
-
Enable Injections (USA) — A technology specialist focused on high-volume self-administration devices. FDA 510(k) clearance in June 2025 for a 10mL variant of the enFuse injector expands its addressable indications and reinforces its role as a prime partner for biologic developers targeting patient-centric delivery.
-
Stevanda (India) — Focused on cost-competitive solutions for emerging markets, Stevanda represents a distinct strategic play: serving price-sensitive systems and local pharma ecosystems where affordability drives adoption.
-
Medipim (Belgium) — With multi-day delivery systems designed for chronic indications, Medipim’s device architecture appeals to therapies demanding extended dosing windows and patient convenience.
-
Nexus Pharmaceuticals (USA) — Functions as a commercialization and distribution enabler, connecting device manufacturers with therapeutic sponsors, particularly in oncology and rare disease segments.
Taken together, these players illustrate two parallel market evolutions: technological differentiation (connectivity, dose volume, user experience) and commercial consolidation (strategic supply agreements and FDA-clearance-based credibility). With CR3 and CR5 concentrations indicating a substantially concentrated market, partnership choice and timing will drive competitive advantage.
Standards, Reimbursement and Supply-Chain Realities
-
Regulatory and safety standards: Wearable injectors are subject to established device norms — ISO 11608-01 for needle-based injection systems and IEC 60601-1 for electrical safety. Compliance to these standards is non-negotiable for market entry and payer acceptance.
-
Reimbursement mechanics: US Medicare coding developments (notably HCPCS-level designations for wearable injector supplies) have reduced a key commercial barrier. However, coding is only part of the puzzle: evidence of real-world effectiveness and cost-offsets is required to secure favorable coverage and utilization.
-
Materials and manufacturing: Device housings commonly rely on medical-grade polymers. Current bulk resin pricing remains an input consideration (medical-grade polycarbonate and cyclic olefin copolymer resins typically trade in an approximate range of USD 8–12/kg), and electronics supply constraints continue to affect lead times — both factors that should be stress-tested in 2026 budgeting cycles.
-
Regulatory usage constraints: Wearable injectors are prescription-only devices and not intended for experimental compounding without regulatory oversight — an important compliance guardrail for commercial and hospital adoption.
Strategic Imperatives for 2026 — What Leaders Should Do Now
-
Prioritize payer-ready evidence: Invest in targeted health-economic studies and real-world evidence collection that demonstrate adherence gains, administration cost savings, and potential reductions in site-of-care utilization.
-
Lock in scalable manufacturing early: Given resin pricing and electronics sourcing risks, secure dual-sourcing agreements and discuss capacity reservations with CMOs to avoid launch delays.
-
Design for digital integration: Telemetry and adherence data will increasingly influence formularies and contracting. Embed secure, standards-compliant connectivity options that align with sponsor data needs and regulatory expectations.
-
Choose partnership models strategically: Evaluate co-development, licensing, and white-label manufacturing against full-internalization scenarios. For many pharma companies, partnering with an established platform provider will accelerate time-to-market and reduce regulatory risk.
-
Segment go-to-market by payer sensitivity: Deploy differentiated pricing and service bundles for private payers, government payers, and self-pay channels to optimize uptake while preserving margin.
-
Prepare for consolidation dynamics: With a concentrated top tier, prepare contingency playbooks for potential competitor M&A or exclusive supply arrangements that could affect access to key platforms.
Why PW Consulting’s Report Is Essential for 2026 Execution
Our study bridges strategy and implementation. Beyond headline market figures, the report delivers executable plans, negotiation-ready financial models, and regulatory roadmaps aligned to current ISO/IEC expectations and recent reimbursement developments. It synthesizes competitive intelligence — including recent product launches, FDA clearances, and commercial agreements announced through 2025 — and maps likely scenarios that will shape 2026 market entry and scale-up.
If your organization is contemplating licensing, developing an in-house wearable injector, structuring a commercialization partnership, or evaluating acquisition targets, the intelligence in this report reduces uncertainty and accelerates decision velocity. To access the full dataset, granular segment analysis, and proprietary supply-chain scorecards that underpin these recommendations, please consult the full PW Consulting Worldwide Wearable Injectors Market report on our website.
For detailed analysis of this topic, please visit the official page: Worldwide Wearable Injectors Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com