

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Predicts Worldwide Adult Ventricular Assist Device Market to Grow at a 5.81% CAGR from 2026–2032

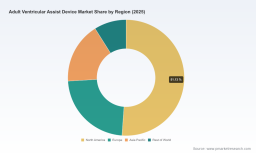
Worldwide Adult Ventricular Assist Device Market — Strategic Preview for 2026 Decision‑Makers
PW Consulting’s new market intelligence briefing frames the adult ventricular assist device (VAD) landscape at a pivotal inflection point. Our analysis projects continuing expansion from an estimated global market size of USD 1,845.5 Million in 2025 to roughly USD 1,941.1 Million in 2026, with a compound annual growth rate (CAGR) of 5.81% through our 2026–2032 forecast horizon and a 2032 market projection of approximately USD 2,742.1 Million. These headline metrics underscore steady, clinically driven growth against a backdrop of regulatory tightening, concentrated competition, and accelerating technology transitions — factors that will determine winners and losers in corporate strategies executed in 2026.
Worldwide Money Insurance Market
Key findings at a glance
-
Resilient market growth: The adult VAD market has expanded materially over the last half‑decade and, per our base case, will continue to grow at a mid‑single digit CAGR out to 2032. This growth is powered by broader adoption of destination therapy, incremental clinical evidence supporting newer centrifugal technologies, and incremental reimbursement alignment in developed markets.
Worldwide Tubing Connections Market -
High concentration, high stakes: Market concentration is pronounced — the top three companies control the overwhelming majority of market revenue, and the top five exceed 90%. This concentration compresses commoditization risk while magnifying the strategic impact of clinical data, recall risk, and regulatory approvals.
Worldwide Melaleuca Oil Market -
Clinical evidence moves markets: Long‑term trial results and real‑world registries are the single most influential determinant of device uptake and payer acceptance. Recent five‑year data for a leading centrifugal LVAD have materially reinforced its commercial position; conversely, device recalls and advisories have precipitated rapid share shifts and created white‑space opportunities for agile competitors.
-
Regulatory and reimbursement complexity: VADs remain Class III devices in the U.S., with PMA processes and evolving European MDR requirements shaping time‑to‑market and post‑market burdens. Simultaneously, recent updates to hospital billing codes and DRG payments in key markets are modifying provider economics and center‑level adoption incentives.
-
Adjacencies and alternatives: Total artificial hearts, percutaneous temporary devices, and improvements in heart failure medical therapy are creating nuanced competitive and complementary dynamics. For incumbent manufacturers the strategic question is whether to focus on incremental LVAD improvements, adjacent device platforms, or service‑led care pathways.
Why this report matters for 2026 strategic decisions
-
M&A screening and diligence: With a highly concentrated market and clear regulatory hurdles, valuation asymmetries will arise from differential clinical evidence and regulatory status. Our report provides a triage framework for identifying targets where regulatory runway, clinical data, or service economics can be de‑risked within a two‑year M&A horizon.
-
Product portfolio prioritization: R&D budgets must be triaged between incremental device improvements (e.g., hemocompatibility, energy efficiency), controller ecosystems, and adjacent platforms such as total artificial hearts. We map the clinical and commercial returns across these investment choices under multiple adoption scenarios.
-
Market access and reimbursement strategy: Payers and hospitals are tightening adoption criteria. Our payer models simulate the impact of specific DRG and CPT updates on provider margins and forecast likely shifts in center of excellence behavior — essential inputs when negotiating hospital contracts or piloting new reimbursement pathways.
-
Commercial strategy and channel design: The capital‑intensive, service‑heavy nature of VAD programs rewards sophisticated field playbooks. The report prescribes sales coverage models, training and servicing KPIs, and partnership archetypes (e.g., implant center alliances, leasing/consignment models) that improve conversion and lifetime value.
-
Clinical development planning: Trial design choices (endpoint selection, non‑inferiority margins, registry‑augmented approaches) materially shift time‑to‑label and market uptake. We provide protocol optimization checklists that reconcile regulatory expectations with real‑world adoption drivers.
Competitive dynamics — what to watch in 2026
-
Abbott Laboratories — execution through evidence: Abbott’s centrifugal LVAD platform remains a commercial anchor for organizations seeking durable destination therapy options. Recent multi‑year trial results showing meaningful survival and neurological outcomes have fortified its commercial position; for competitors, matching or exceeding that evidence is a prerequisite for displacement.
-
Medtronic — recall legacy and strategic choices: The recall and clinical advisory surrounding one of Medtronic’s centrifugal systems have constrained new implantations in several markets and reshaped the competitive field. Ongoing support obligations and liability considerations continue to influence hospital procurement decisions and present strategic openings for other manufacturers.
-
LivaNova — regional thrust and next‑generation centrifugal entrants: CE Mark progress and commercial launches across Europe illustrate a viable pathway to scale for newer centrifugal designs. For multinational players, timing and sequencing of regulatory clearances will dictate when and where to press advantage or defend ground.
-
Berlin Heart and Syncardia — niche and adjunct strategies: External pneumatic devices and total artificial heart platforms serve important clinical niches — specifically in biventricular failure or implant‑ineligible patients. These therapies underscore the importance of service, specialized training, and referral network stewardship rather than pure product competition.
-
Implication: consolidation and co‑opetition: Expect continued consolidation among devices, supply chain partners, and service providers. Strategic partnerships (manufacturing, digital health, consumables management) will be decisive for scaling programs and extracting service revenue beyond the implant.
Regulatory and reimbursement dynamics shaping 2026 strategies
-
Regulation: Adult VADs remain Class III devices under U.S. regulation and require PMA pathways, with the European MDR imposing rigorous Annex II conformity assessment and enhanced post‑market surveillance obligations.
-
Reimbursement: Recent payer actions — including an updated DRG for LVAD implants and changes to procedural coding that recognize new approaches — are already influencing hospital economics and may accelerate or decelerate regional adoption depending on pathway design.
-
Recall risk: Device advisories and class I recalls have immediate commercial fallout. Companies must pair device engineering plans with rapid-response clinical and communications playbooks to protect center relationships and minimize attrition.
What the full PW Consulting report delivers (practical components)
-
Demand forecasting package: Transparent top‑down and bottom‑up models with scenario sensitivity (base, upside, downside) covering 2026–2032 and incorporating epidemiology, center capacity, and payer dynamics.
-
Commercial playbooks: Market entry and expansion templates for incumbents, challengers, and new entrants — including sample KPIs, training curricula, and consumables pricing strategies.
-
Regulatory roadmap and time‑to‑market planning: Country‑level approval timelines, required clinical endpoints, and PMA/Notified Body considerations that materially affect launch sequencing and resource allocation.
-
Reimbursement impact models: Provider margin simulations under DRG and CPT updates to estimate adoption thresholds across hospital archetypes and payer mixes.
-
Competitive deep dives: Strategic profiles and recent development summaries for the leading players, with implications for partners, suppliers, and acquirers.
-
M&A and partnership screening tool: Valuation heuristics and a short list of candidate assets/categories prioritized for strategic buyers and private equity sponsors.
-
Operational readiness checklist: Manufacturing scale considerations, aftermarket service models, and supply chain vulnerabilities critical to sustaining growth in 2026 and beyond.
Methodology and credibility
Our findings are grounded in a blended research approach: primary interviews with clinical and procurement leaders at implant centers, detailed billing and claims analysis, device registry and trial outcome synthesis, and a proprietary forecasting engine that triangulates epidemiology, center capacity, and historical adoption curves from 2020–2025. We validate outputs through sensitivity testing and scenario analysis to reflect regulatory shocks, evidence inflection points, and reimbursement changes. To preserve tactical value for clients, this public summary is deliberately high‑level; the full report contains the supporting datasets, model logic, and payoff matrices used to generate our projections.
Next steps for executives and investors
-
Prioritize clinical evidence programs that target durable survival and neurological outcomes — these are the single biggest determinant of payer coverage and center preference.
-
Build dual pathways for growth: defend core centrifugal platforms while exploring adjacent service and total‑heart solutions that capture unmet clinical segments.
-
Stress‑test M&A opportunities against regulatory timelines and recall‑scenario contingencies — integration plans should explicitly cover post‑market surveillance and product liability drag.
-
Engage payers early with real‑world evidence frameworks and hospital pilots aligned to updated DRG/CPT mechanics to accelerate adoption at reference centers.
PW Consulting’s Worldwide Adult Ventricular Assist Device Market report is designed as an executable intelligence product for leadership teams setting 2026 priorities. To access the full dataset, segmentation detail, executable playbooks, and proprietary models referenced in this briefing — including the granular regional and application splits withheld here to preserve strategic value — visit the PW Consulting report landing page or contact our advisory team to arrange a briefing and demonstration.
For detailed analysis of this topic, please visit the official page: Worldwide Adult Ventricular Assist Device Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com