

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Market Insights: Worldwide Liquid Termiticides Market to Hit USD 4,042.31 Million by 2032, Expanding at a 5.12% CAGR

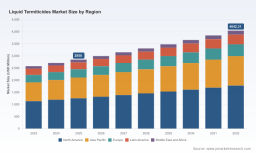
Worldwide Liquid Termiticides Market — 2026 Strategic Outlook (PW Consulting)
Executive summary
As the liquid termiticides market enters a new strategic inflection point, PW Consulting’s latest market study provides an indispensable evidence base for 2026 corporate decision-making. The market has grown from USD 2,579.14 Million in 2023 to an estimated USD 2,850.0 Million in 2025, and our baseline projection shows expansion to roughly USD 4,042.31 Million by 2032. Our forecast for the 2026–2032 period is driven by a compound annual growth rate (CAGR) of 5.12% under the base-case scenario.
Mental Stress Analyzer (Heart Rate Variability Detector) Market
These headline figures only hint at the complexity behind industry dynamics. Strategic choices in 2026 — around R&D prioritization, supply chain resilience, product stewardship and M&A — will determine winners and laggards through the coming cycle. This release summarizes the report’s high-value insights and tactical frameworks, while reserving the detailed segment-level tables and proprietary scenario outputs for the full report.
Worldwide Heavy Duty Truck Seat Market
Why 2026 is a pivotal year
-
Regulatory tightening and stewardship expectations are accelerating. The U.S. EPA’s 2025 Insecticide Strategy (April 2025) elevates mitigation requirements for insecticides to protect endangered species, creating new constraints on field use patterns and technical support expectations from manufacturers.
Ethylene Oxide Device Sterilization Market -
Active ingredient risk profiles and market access are in flux. Policy actions and scientific assessments continue to constrain agricultural uses of certain actives — a dynamic that spills into structural pest management through supply pressure, public perception, and stewardship obligations.
-
Supply-side dynamics are more volatile. Between raw material price inflation for key actives and episodic supply chain bottlenecks linked to geopolitics and transport disruptions, manufacturers face margin and availability trade-offs that require immediate mitigation plans.
-
Customer expectations and commercial models are evolving. Professional applicators demand formulations that balance efficacy, safety, application efficiency and regulatory defensibility; meanwhile, service models and bait technologies continue to reshape purchase and adoption dynamics.
What PW Consulting’s report delivers (practical, execution-focused)
-
Robust market-sizing and probabilistic forecasting model: Our model produces top-line market trajectories (2020–2032) with alternative scenarios that embed commodity shocks, regulatory tightening, and adoption curves for reduced-risk chemistries.
-
Regulatory and stewardship dashboard: A jurisdiction-by-jurisdiction heat map of regulatory risk drivers and expected timelines for policy actions, including mitigation measures that materially affect use patterns and labeling.
-
Supply chain risk maps and cost-to-serve analysis: An operational playbook identifying single points of failure, near-shoring opportunities, and indexed sensitivity of gross margins to raw material cost movements.
-
Competitive positioning toolkit: Product and channel benchmarking, go-to-market playbooks for global and regional rollouts, and a transaction screen for target selection in consolidation scenarios.
-
Field-efficacy and stewardship matrix: Comparative performance and application-efficiency scores for major liquid formulations, tied to technician training and quality assurance interventions that improve in-field outcomes.
-
Scenario-based strategic roadmaps: Tactical initiatives ranked by expected value and implementation complexity — from formulation reformulation programs to pilot manufacturing partnerships and targeted commercial trials.
Competitive dynamics — what the major players signal
The liquid termiticides market remains moderately concentrated: the top three global suppliers account for a material share of volumes and influence over distribution channels, with the top five further consolidating market power. Against this backdrop, incumbent agrochemical and pest management firms retain a mix of advantages — established portfolios, regulatory dossiers, and deep technical support networks — while nimble specialists and generics providers exert pricing pressure in mature channels.
-
BASF SE (Termidor portfolio) — Strengths: market-leading brand recognition and a proven non-repellent solution set that underpins pre- and post-construction programs. Strategic implication: BASF’s depth in stewardship programs and technical support raises the barrier for new entrants seeking share in professional channels.
-
Syngenta AG (Altriset / chlorantraniliprole) — Strengths: a reduced-risk active that aligns with regulatory and customer demand for lower mammalian and non-target toxicity. Strategic implication: regulatory windows (including recent temporary residue tolerances) materially affect commercialization runway; manufacturers should plan for both opportunity windows and expiry of special allowances.
-
FMC Corporation — Strengths: broad pyrethroid portfolio and strong relationships with professional applicators. Strategic implication: price and supply management for pyrethroid active ingredients will influence FMC’s mix decisions; investment in stewardship and non-target risk mitigation is essential to defend market access.
-
Bayer AG — Strengths: Premise (imidacloprid-based) legacy product and global distribution muscle. Strategic implication: imidacloprid’s constrained agricultural profile requires Bayer to focus on structural use stewardship and labeling clarity to maintain acceptance among customers and regulators.
-
Nufarm Limited and Sumitomo Chemical — Strengths: global formulation and distribution capabilities tailored to local market needs. Strategic implication: these firms are well-positioned to offer regionally adapted formulations and to execute nimble supply strategies.
-
Control Solutions Inc. and Ensystex Inc. — Strengths: competitive generics and integrated service-product offerings that compete on cost and convenience. Strategic implication: generics and integrated-service models will continue to exert downward price pressure and accelerate commoditization in selected channels.
Regulatory and raw-material realities that will shape 2026 decisions
-
Policy developments are active and consequential. The U.S. EPA’s Insecticide Strategy (April 2025) signals heightened mitigation and species-protection obligations that apply to insecticide use patterns, including those relevant to termiticide applications.
-
Time-limited regulatory allowances create tactical windows. A recent time-limited tolerance established in late 2025 for residues of a reduced-risk active in a specific commodity illustrates how administrative flexibility can create temporary commercialization advantages — but such allowances come with expiration dates that must be planned for.
-
Raw material cost and supply volatility matter. Key active ingredients experienced meaningful price increases in recent years, and transport or production bottlenecks have periodically disrupted supply. Companies without diversified sourcing or hedging strategies face margin compression or lost sales.
-
Non-target protections and agricultural restrictions are reshaping perceptions. Uses of some historically common actives have been restricted in agriculture due to pollinator and non-target risks; this regulatory and reputational pressure prompts manufacturers to accelerate alternatives and stewardship investments in structural pest control.
Risks, opportunities and priority choices for 2026
-
Risk — Regulatory tailwinds can turn into constraints: Firms overly dependent on a narrow set of actives risk sudden label changes, use restrictions or reputational headwinds. Mitigation: diversify active portfolios and invest in residue and non-target monitoring programs.
-
Opportunity — Reduced-risk chemistries and application efficiencies: Accelerating adoption of lower-risk actives and high-efficiency application systems is a durable market trend. Action: allocate R&D and field-trial budgets now to capture early-adopter share and to build stewardship narratives.
-
Risk — Supply-chain fragility and raw-material cost shocks: Single-supplier dependencies for specialty intermediates create commercial vulnerability. Mitigation: near-shoring, dual sourcing, and strategic inventory policies should be stress-tested under the scenarios we provide.
-
Opportunity — Service-led differentiation: Integrated offerings that combine product, digital decision-support and technician training materially increase switching costs and customer lifetime value. Action: pilot service bundles in key provinces and measure retention uplift.
Top-line strategic recommendations for 2026
-
Prioritize portfolio resilience: Invest in at least two alternative active chemistries and accelerate formulation work that reduces reliance on constrained inputs.
-
Operationalize regulatory scenario planning: Create a cross-functional “regulatory war room” to model label changes, conditional tolerances and mitigation prescriptions that could hit volumes or application methods.
-
Hedge supply risk pragmatically: Combine contractual off-take, strategic inventory buffers and selective near-shoring to reduce single-point failure exposure without overcapitalizing.
-
Monetize stewardship: Turn regulatory compliance into a commercial asset by certifying applicator networks and using stewardship credentials to secure premium channel partnerships.
-
Use M&A and partnerships selectively: Target bolt-on formulations, local manufacturing capacity and service platforms that accelerate time-to-market for reduced-risk solutions.
How PW Consulting supports execution
The full PW Consulting report is designed as both a strategy blueprint and an implementation toolkit. Subscribers receive the granular scenario outputs, the full segmentation matrices, playbooks for pricing and channel expansion, and customizable financial models. We also provide advisory engagements to operationalize recommendations through pilot programs, regulatory engagement strategies, and M&A target diligence.
This briefing is a strategic “trailer” that highlights the decision levers that matter entering 2026. For the detailed segment tables, localized forecasts, and the proprietary scenario model that underpins the USD 4,042.31 Million 2032 projection (with a 5.12% CAGR for 2026–2032), please refer to the full Worldwide Liquid Termiticides Market report and contact PW Consulting for access to the complete dataset and bespoke advisory options.
For detailed analysis of this topic, please visit the official page: Worldwide Liquid Termiticides Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com