

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecast: Worldwide CNS Stimulants Market Poised for a 6.25% CAGR Through 2032

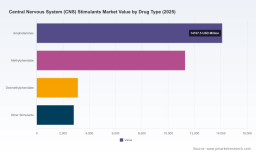
Strategic Preview: Worldwide CNS Stimulants Market — Preparing Pharma Leadership for 2026
PW Consulting’s latest market study on Worldwide Central Nervous System (CNS) Stimulants synthesizes market-scale dynamics, regulatory inflection points and competitive moves into an actionable roadmap for executive decision-making in 2026. Anchored on a 2025 base year and projecting through 2032, our model shows the global CNS stimulants market expanding at a compound annual growth rate (CAGR) of 6.25% (USD, revenue unit: Million). The market has grown from the mid‑2020s through 2025 and, under our base scenario, continues a steady expansion into 2032—driven by persistent ADHD demand, therapeutic diversification, and formulation-driven lifecycle management.
Worldwide Brassinolide Market
Why this report matters for 2026 strategy
-
Decisions in 2026 must account for a market that is simultaneously mature and dynamically reshaping: incumbent brand equity and extensive generic penetration coexist with product-level innovation (delivery systems, prodrugs, delayed‑release platforms) and renewed regulatory scrutiny. Our analysis translates these tensions into strategic imperatives for pipeline prioritization, manufacturing investments, and commercial go‑to‑market sequencing.
Worldwide Cryptocurrency Software Market -
Regulatory and supply constraints affecting Schedule II stimulants are not one‑off disruptions but structural variables that will influence capacity planning, contract manufacturing relationships and geographic launch priorities. The report quantifies the likely market impact of these variables under alternative regulatory and supply scenarios, enabling financial teams to stress‑test forecasts and procurement groups to prioritize resilience investments.
Worldwide Dental Fluoride Varnish Market -
For commercial leadership, the report benchmarks competitive positioning across originator, authorized‑generic and pure‑play generic players, and provides playbooks for formulary negotiations, specialty channel deployment and lifecycle extensions that maintain profitability in a pricing‑sensitive environment.
What the topline numbers tell you (and what they don’t)
PW Consulting’s market model provides year‑by‑year revenue projections from 2023 through 2032 (USD Million). It captures recent acceleration into 2025 and a projected continuance of growth into 2032 consistent with the 6.25% CAGR. These topline trajectories reflect demand persistence for core ADHD and narcolepsy indications, incremental uptake of new formulations and steady replacement/renewal cycles in chronic use populations.
As a “trailer” for our proprietary dataset, we surface the macro growth trajectory to inform board‑level resource allocation without publishing the granular regional, drug‑type and indication splits contained in the full report. Clients who need segment‑level revenue, market share tables, or the scenario outputs that translate quota shifts, label changes and supply interruptions into P&L impacts should consult the complete research pack.
Regulatory and supply dynamics shaping 2026 choices
-
Heightened regulatory focus. Recent regulatory actions have materially altered product risk/benefit communication: in mid‑2025, regulators mandated expanded pediatric warnings for extended‑release amphetamine and methylphenidate products. That label evolution directly affects pediatric prescribing patterns and the commercial case for pediatric label expansion programs. Teams must update clinical development and pharmacovigilance strategies to accommodate heightened safety surveillance and potential labeling constraints.
-
Controlled‑substance production quotas. Aggregate production quotas have been adjusted upward in response to manufacturer requests, reflecting underlying demand and supply negotiations with regulators. These quota dynamics become strategic levers—especially for originators and large generics—that can be used to smooth supply or to secure short‑term competitive advantage. Our scenario module maps quota outcomes to market availability and price volatility under multiple regulatory response assumptions.
-
Persistent API and finished‑product constraints. Global API concentration and downstream manufacturing bottlenecks continue to produce intermittent shortages, notably among immediate‑release amphetamine salts. The 2026 environment therefore favors companies with diversified sourcing, redundant manufacturing footprints, or long‑dated supply agreements. Manufacturers should prioritize capital allocation to strategic capacity, and payers/pharmacies should assess contingency protocols to avoid therapy disruption.
-
Quality assurance signals. Quality surveillance outcomes matter: publicly reported FDA quality testing in early 2026 confirmed acceptable results for certain extended‑release methylphenidate products from leading generics manufacturers. This kind of verification reduces short‑term market risk for specific suppliers and can influence procurement choices among health systems and group purchasing organizations.
Competitive landscape: reading the signal from established and emerging players
The CNS stimulants category is populated by a spectrum of players: multinational originators with branded franchises, large generic manufacturers with scale supply capabilities, and smaller firms focused on formulation innovation and niche delivery technologies. Our competitive assessment highlights several strategic archetypes present in the marketplace:
-
Originator franchises leveraging formulation differentiation: Major multinational companies continue to protect and extend branded assets through extended‑release platforms, prodrug approaches and time‑of‑day targeting. These plays are supported by strong regulatory and commercial infrastructures and permit premium pricing in managed markets with favorable reimbursement.
-
Scale generics and contract manufacturers: Large generic manufacturers and specialty producers remain the backbone of volume supply, particularly in mature markets. Their strategic focus is on manufacturing efficiency, portfolio breadth and rapid biosimilar‑style launch readiness when exclusivities expire. Manufacturing quality verification events in 2026 are a positive signal for these players’ market access.
-
Formulation specialists and delivery innovators: Smaller, agile companies are capturing value through novel delivery systems (liquid formulations, transdermal patches, delayed‑release evening dosing) and prodrug technologies that modify abuse potential and dosing cadence. These capabilities are attractive to payers when they reduce administration burden or improve adherence.
Beyond pure therapeutic competition, the category is shaped by shifting payer dynamics and regulatory engagement. Our competitor dossiers evaluate commercial strengths, manufacturing footprints, patent cliffs, partnership activity and clinical pipelines for the leading firms in the space. For clients considering collaborations, M&A or licensing, those dossiers create an actionable shortlist calibrated to 2026 market realities.
Strategic implications and playbook for 2026 decision‑makers
PW Consulting’s research distills market forces into a compact strategic playbook tailored for executive teams preparing budgets, capital plans and product roadmaps in 2026. Key recommendations include:
-
Adopt scenario‑based demand planning that integrates quota variability and label changes. Build a matrix of likely regulatory outcomes and tie these to procurement, manufacturing ramp‑up schedules and launch timing decisions.
-
Invest selectively in supply chain resilience: prioritize API diversification, capacity redundancy in finished‑dose production, and long‑term supply agreements with validated manufacturers to reduce exposure to episodic shortages.
-
Prioritize formulation differentiation that addresses payer and end‑user pain points: convenience, adherence, abuse‑deterrent/prodrug designs and pediatric suitability will command attention from formulary committees and prescribers.
-
Prepare reimbursement rationales mapped to evolving pricing paradigms. With pricing models and benchmarking pilot programs under discussion in major markets, companies must document value through real‑world evidence, pharmacoeconomic models and targeted outcomes studies.
-
Leverage regulatory intelligence as a competitive asset. Proactive engagement with regulators on labeling language, pediatric risk mitigation, and post‑marketing surveillance programs can reduce time‑to‑market and improve acceptance of new formulations.
-
Shape M&A and partnership strategies around asymmetric advantages: originators seeking manufacturing scale should prioritize targets with validated GMP facilities; smaller developers with differentiated delivery systems should seek partners offering payer access and commercialization infrastructure.
Report contents — practical deliverables you can use in 2026
The full PW Consulting report is designed for operational use by commercial, regulatory, R&D and M&A teams. Key deliverables include:
-
A transparent market model (2020–2032) with downloadable spreadsheets and scenario toggles for regulatory, supply and reimbursement shocks.
-
Region‑ and indication‑level forecasts (with sensitivity bands) and a methodology appendix describing data sources and assumptions.
-
Proprietary supplier risk heatmaps that identify API concentration, single‑site dependencies and likely shortage triggers.
-
Company profiles and comparative scorecards covering manufacturing quality, commercial reach, pipeline differentiation and likely post‑patent competition timing.
-
Actionable go‑to‑market playbooks for branded launches, authorized generics, and generic‑only market entry strategies.
-
Regulatory tracker and policy impact assessments, including quantified P&L impacts for plausible labeling and quota scenarios.
Conclusion — preparing to act, not just to observe
As the CNS stimulants market moves into 2026, executives face a landscape of predictable growth but compound uncertainty: regulatory tightening, quota mechanics, supply chain fragility and evolving reimbursement frameworks. PW Consulting’s study converts that complexity into a structured set of choices—prioritizing resilience, formulation innovation and payer‑facing evidence generation.
Our preview has revealed the macro growth path and the strategic contours leaders must consider. For stakeholders who require the granular segmentation, regional breakdowns, and the full suite of model outputs that drive transaction and operational decisions, the complete report provides the necessary depth and downloadable tools to act with confidence. PW Consulting stands ready to partner on bespoke scenario analysis, M&A diligence and implementation roadmaps tailored to your 2026 strategic plan.
For detailed analysis of this topic, please visit the official page: Worldwide Central Nervous System (CNS) Stimulants Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com