

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Predicts 18% CAGR — Worldwide Active Optical Cable & Extender Market to Reach USD 14.34 Billion by 2032

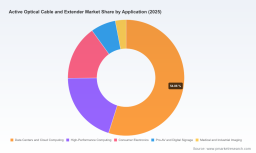
Worldwide Active Optical Cable and Extender Market: Strategic Imperatives for 2026
As enterprises, cloud providers, and network equipment manufacturers enter a decisive build-out phase for AI-ready infrastructure, Active Optical Cables (AOCs) and optical extenders have moved from niche enablers to core strategic assets. PW Consulting’s latest market study projects the worldwide AOC and extender market to reach approximately USD 4.50 billion in 2025, accelerating to roughly USD 5.49 billion in 2026 and following an 18.0% compound annual growth rate through our 2026–2032 forecast horizon. This growth trajectory is not academic: it reshapes capital planning, supplier strategy, and product road maps for any organization that depends on high‑speed, low‑latency optical interconnects.
Cybersecurity Vulnerability Assessment Service Market
Why 2026 is a Strategic Inflection Point
The near-term market dynamics combine robust demand with supply-side scarcity and rapid technology transitions. Hyperscale cloud expansions, the spread of high-performance computing (HPC), densification for AI workloads, and shifting architectures such as co‑packaged optics are converging to create both opportunity and risk. The market’s growth rate implies that organizations delaying strategic choices in 2026 risk higher procurement costs, missed integration windows, and degraded competitive positioning.
Worldwide Back Office Automation Market
Executives should interpret the 18.0% CAGR not as mere growth, but as the pace of architectural change: capacity requirements, connector and form-factor standards, and supplier ecosystems will evolve quickly. Those who treat AOCs and extenders as commodity cables will find themselves constrained by lead-time bottlenecks and losing negotiating leverage with tier‑one suppliers.
Worldwide Intensified Cameras Market
What the PW Consulting Report Delivers — Practical, Transactional, and Decision‑Ready
- Market sizing and scenario forecasts calibrated to 2026 budget cycles and multi‑year capital plans, highlighting upside and downside demand paths.
- Actionable vendor assessment frameworks that translate technical capability into procurement scorecards and negotiating levers.
- Go‑to‑market playbooks for OEMs, system integrators, and hyperscalers — including channel strategies, warranty economics, and migration roadmaps for 400G/800G and beyond.
- Supply‑chain mitigation templates: dual‑sourcing roadmaps, safety‑stock heuristics, and long‑lead component hedging strategies tailored to optoelectronics constraints.
- Technology adoption timelines, showing pragmatic steps to prepare for co‑packaged optics, multicore fiber launches, and microLED light sources without disrupting current deployments.
- Regulatory and tariff impact worksheets for procurement teams, allowing quick recalculation of TCO under different trade and duties scenarios.
- M&A and partnership screening tools to prioritize targets and assess integration risk in a market where the top firms capture meaningful share but leave room for challengers.
In short, the report is built to be used inside planning cycles: it provides executable artifacts (models, templates, and checklists), not just descriptive charts.
Competitive Landscape — Who Moves First and Why It Matters
The market shows a moderate concentration: the top three players control a substantial but not dominant portion of revenues, and the top five expand that share meaningfully. This structure fosters a dynamic arena where established incumbents, specialized component suppliers, and cost‑focused manufacturers each play distinct roles.
- Corning Incorporated: Positioned to lead on density and AI‑centric interconnects, Corning’s investments in multicore fiber and micro‑cable architectures are a direct response to hyperscaler demand for space‑efficient, high‑bandwidth cabling.
- Broadcom Inc. and Coherent Corp. (formerly II‑VI / Finisar): These integrated‑component leaders influence platform adoption through chipset and transceiver road maps, enabling higher per‑link rates and tighter ecosystem control.
- Molex LLC, Amphenol Communications Solutions, TE Connectivity and similar assembly specialists: Their advantage is breadth — robust portfolios for enterprise, industrial and ruggedized use cases — enabling fast channel response and systems integration.
- Nimble, cost‑focused vendors from APAC: Shenzhen‑based and other regional manufacturers are critical to white‑box channels, offering strong price competition for high‑volume deployments and accelerating price pressure in standard configurations.
- Specialists such as Sumitomo Electric, Fujikura, 3M and Siemon: These players combine material science and connectivity expertise to support high‑reliability and regulated environments.
Recent product and research announcements crystallize competitive vectors: multicore fiber and micro‑cable solutions to improve rack density, and microLED‑based AOC prototypes aimed at reducing power and improving thermal profiles. These are not incremental — they influence procurement timing, lifecycle costing, and co‑engineering relationships between OEMs and hyperscalers.
Supply Chain & Pricing Dynamics: The Hidden Levers
Three less‑visible market mechanics will determine winners and losers in 2026:
- Bill of materials economics: Transceiver chipsets dominate the cost structure of an AOC, representing roughly two‑thirds of the bill of materials in many designs, while the fiber portion is comparatively small. That imbalance amplifies the commercial significance of chipset availability and supplier licensing terms.
- Price erosion and channel segmentation: Standard 100G AOC units continue to face annual price erosion in the low double digits, and there is a persistent large price delta between OEM‑coded modules and compatible white‑box equivalents. Procurement teams must balance short‑term savings against long‑term reliability and support costs.
- Component lead times and supply constraint: Critical optoelectronics — VCSELs, photodetectors and specialized driver ICs — are subject to extended lead times, with some configurations experiencing multi‑month deliveries. This reality makes forward planning and supplier cooperation essential.
Geopolitical and tariff pressures further complicate sourcing. In many procurement scenarios, tariff changes on electronic components materially alter project economics, and agile teams will want to maintain playbooks that can be executed within weeks, not months.
Prioritized Playbook for 2026 Decision‑Makers
Based on our analysis, PW Consulting recommends a prioritized set of actions for C‑suite leaders, procurement heads, and product strategists entering 2026:
- Embed optical interconnect strategy into capital planning: translate the projected growth and technology shifts into capacity investments and migration timelines aligned with your fiscal calendar.
- Shift from spot procurement to strategic supplier contracts: negotiate volume commitments that secure capacity for critical transceiver components while preserving flexibility for emerging form factors.
- Operationalize a two‑tier sourcing model: marry trusted tier‑one suppliers for mission‑critical paths with vetted white‑box partners for scale and price agility.
- Invest in co‑engineering partnerships: secure early access to multicore, micro‑cable and microLED innovations through joint development agreements to gain design wins rather than simply buying components.
- Quantify total cost of ownership (TCO) across scenarios: incorporate price erosion trajectories, warranty and replacement economics, and tariff contingencies into procurement decisions.
- Use M&A and alliance moves selectively: target technology suppliers that fill roadmap gaps (e.g., advanced lasers, driver ICs, or assembly automation) rather than purely revenue‑accretive targets.
- Operational resilience: build inventory buffers for long‑lead optoelectronic parts, adopt flexible manufacturing agreements, and simulate multi‑node failure scenarios into continuity plans.
- Compliance and sustainability: incorporate lifecycle and end‑of‑life plans early — not as an afterthought — to meet regulatory and customer expectations while limiting stranded asset risk.
How to Use This Report in Your 2026 Planning Cycle
PW Consulting’s study is structured to be directly executable in annual planning and vendor selection cycles. Use it to inform board‑level investment cases, to guide RFP specifications, and to prioritize product features and form‑factor roadmaps. For procurement organizations, the supply‑chain playbooks and contract templates can be implemented with minimal customization to reduce lead‑time risk and capture the benefits of scale as the market grows.
For technology teams, the adoption timelines and co‑engineering checklists clarify which emergent technologies warrant immediate pilots versus staged evaluation. For strategy and corporate development groups, our M&A screening filters accelerate target identification in a market where concentration is meaningful but not prohibitive — creating windows for well‑timed acquisitions or joint ventures.
Closing: Why This Market Demands Proactive Leadership
The AOC and extender market is at once high‑growth and technically nuanced. The projected expansion from an approximate USD 4.5 billion market in 2025 to a significantly larger market by 2032, combined with an 18.0% CAGR, will reshape procurement economics and architectural choices. The top tier of vendors capture a sizeable share of value, but the midpoint concentration leaves room for disruptors that can combine technical differentiation with supply resilience and competitive pricing.
This press release intentionally omits segment‑level breakdowns and granular vendor scoring — those are core proprietary insights in the full PW Consulting report, designed to power vendor selection, investment decisions, and strategic roadmaps. For executives building or defending a 2026 budget, the tactical assets in the full report — scenario models, supplier scorecards, and procurement playbooks — are designed to be directly executable.
To access the comprehensive dataset, dynamic models, and step‑by‑step playbooks that underlie these conclusions, visit PW Consulting’s Worldwide Active Optical Cable and Extender Market report page and download the full briefing. In a market moving this quickly, access to the right intelligence is the difference between leading the transition and reacting to it.
For detailed analysis of this topic, please visit the official page: Worldwide Active Optical Cable and Extender Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com