

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecast: Worldwide Cloud IDS/IPS Market to Surge at a 15.2% CAGR Through 2032

PW Consulting Releases Worldwide Cloud IDS/IPS Market Report — A Strategic Playbook for 2026 Decision-Makers
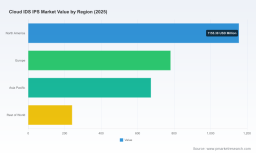
PW Consulting today publishes its authoritative Worldwide Cloud IDS/IPS Market report, offering senior security and cloud leaders a pragmatic roadmap for decisions that will determine resiliency, economics, and compliance posture through the 2026 planning cycle and beyond. Built on a robust historical baseline (2020–2025) and a detailed seven-year forecast (2026–2032), the study quantifies a market expanding rapidly — driven by cloud-native adoption, distributed application architectures, and the operationalization of threat intelligence. The global market was approximately USD 2,850 Million in our 2025 base year and is projected to grow to roughly USD 7,673.8 Million by 2032, representing a compound annual growth rate of 15.2% over the forecast period.
Worldwide Media and Influencer Targeting Software Market
Why this report matters for 2026 strategy
-
Timing and confidence: Security procurement and architecture cycles in 2026 will be governed by shorter product lifecycles, accelerated cloud migration plans, and tighter capital discipline. Our report translates market trajectory into decision-ready timelines — helping CISOs and CIOs prioritize pilots, migrations, and vendor evaluations within the 12–36 month window when technology choice still matters most.
Worldwide Harbor Operations Software Market -
Cost and capacity realism: As cloud IDS/IPS becomes a continuous, traffic-sensitive function, hosting economics matter. The report aligns market growth with operational drivers — including the material rise in data center electricity demand and AI-driven workload growth — so finance and security teams can anticipate the real TCO implications of inline versus agent-based models and public versus private cloud placements.
Cord Blood Sealer Market -
Regulatory and procurement clarity: With shifting certification pathways and evolving data sovereignty rules, our analysis highlights the regulatory inflection points that will affect vendor selection, deployment topology, and contractual obligations in regulated industries and government procurement.
-
Competitive context without the noise: We provide a practical vendor landscape and capability mapping that illuminates where the market is consolidating and where specialist players are innovating — enabling buyers to fast-track shortlist decisions while preserving room to validate technical fit in PoC phases.
What the report contains — operational, practitioner-focused deliverables
-
Executive decision matrix: A concise framework that maps business objectives (risk reduction, compliance, cost control, speed-to-market) to technical options (cloud-native IDS, virtual appliances, host-based solutions, managed services), with recommended prioritization for 2026 procurement cycles.
-
Vendor capability playbooks: Actionable profiles and comparative criteria for leading and emerging suppliers — covering integration posture, threat intelligence sourcing, automation maturity, and managed service delivery models.
-
Implementation blueprints: Ready-to-adapt deployment patterns for common enterprise environments (greenfield cloud-native workloads, lift-and-shift migrations, multi-cloud orchestration, and regulated-sector hybrid deployments), including sample rule management workflows and escalation pathways.
-
TCO and energy sensitivity models: Interactive scenario analysis that quantifies how compute, traffic growth, and rising electricity demand influence per-GB inspection costs and the relative attractiveness of centralized versus distributed inspection points.
-
Procurement and contracting templates: Clauses and KPIs designed for 2026 realities (data locality, shared responsibility, SLAs for detection-to-response, and audit support), to reduce negotiation cycles and preserve operational flex.
-
Validation playbook and PoC templates: Test plans that emphasize adverse-case scenarios (lateral east-west traffic, encrypted flows, and AI-driven attack patterns), enabling buyers to validate detection efficacy and false-positive economics before deployment scale-up.
-
Risk and compliance compendium: A practical guide to mapping data sovereignty, sectoral localization rules, and recent certification changes into architectural constraints and vendor roadmaps.
Competitive landscape — who matters and why
The Cloud IDS/IPS market is maturing into a mix of large platform providers, cloud-native specialists, and security incumbents transitioning their portfolios. Market concentration is meaningful: the largest three firms account for a material share of vendor revenue, and the top five expand that concentration further — creating both integration advantages and strategic risk for buyers who prefer supplier diversity.
Key companies profiled in the report include platform leaders and specialists that matter to enterprise buyers in 2026:
-
Cisco Systems — brings cloud-native and hybrid IDS/IPS capabilities tightly integrated with its Secure Firewall and broader security platforms. Cisco’s strength is enterprise-grade integration and a broad installed base that eases operations for global deployments.
-
Fortinet — positions cloud-delivered IPS/IDS with AI-driven threat intelligence and scalable inspection engines, appealing to organizations seeking consolidated networking and security stacks.
-
Trend Micro — emphasizes automated rule management and one-click managed policy groups for major cloud marketplaces, simplifying deployment and ongoing tuning in public cloud environments.
-
Palo Alto Networks — integrates IDS/IPS functions into comprehensive cloud workload security, delivering unified prevention across network and host contexts.
-
Check Point, CrowdStrike, Zscaler, IBM Security, Microsoft, AWS, Google Cloud, Juniper, and Sophos — each brings differentiated strengths in threat telemetry, cloud platform integration, zero-trust positioning, or managed service delivery that will influence partner strategies and procurement choices.
Recent market activity referenced in the report underscores the pace of productization and cloud partnership strategies: Trend Micro’s partnership to offer one-click managed rule groups in major cloud marketplaces reduces operational friction for buyers; and new cloud firewall offerings embedding IDS/IPS functions reflect vendor moves to consolidate north-south and east-west protection in single consoles. These developments accelerate buyer value capture but also raise interoperability and lock-in considerations that the report helps negotiate.
Industry dynamics — energy, regulation, and deployment complexity
Beyond vendor capabilities, two structural forces will shape 2026 outcomes and are examined in depth:
-
Energy and operational cost pressures: Data center electricity demand rose markedly in recent years, driven by AI and heavy compute workloads. The report models how rising energy costs and power density constraints change the economics of continuous inline inspection versus sampled or host-based approaches, and how architects can optimize inspection placement to reduce marginal operational cost.
-
Regulatory and certification shifts: Notable changes in government testing and certification pathways — including the sunset and transition of legacy procurement lists — require security teams to rethink compliance roadmaps and validate alternative certification strategies. Meanwhile, data sovereignty and cross-border restrictions continue to impose architectural constraints for regulated industries and global enterprises.
Actionable recommendations for 2026 planning
-
Adopt a staged deployment strategy: Begin with focused PoCs in mission-critical but contained environments to validate detection efficacy and operational cost, then expand to high-risk east-west segments once rule automation proves effective.
-
Incorporate energy and TCO sensitivity into procurement: Require vendors to disclose inspection compute profiles and energy estimates, and include energy-adjusted TCO in bid evaluation to avoid surprise operational costs as workloads scale.
-
Prioritize interoperability and telemetry portability: Choose solutions that export normalized telemetry and support standardized APIs to avoid long-term lock-in and to enable multivendor analytics.
-
Plan for regulatory contingencies: Build deployment templates that can isolate data flows by jurisdiction and retain the option to localize inspection capabilities where sovereignty rules require it.
-
Use concentration-aware sourcing: Where supplier concentration introduces systemic risk, consider blended sourcing (platform + specialist) and diversify critical detection functions across different technology bases.
A final note — depth with discretion
PW Consulting’s Worldwide Cloud IDS/IPS Market report is intentionally designed as a practitioner’s playbook: it reveals the analytical frameworks, vendor comparisons, and scenario models you need to make confident 2026 decisions, while preserving sensitive subsegment intelligence for subscribers. The report demonstrates our deep quantitative modeling — anchored by the 2025 market baseline and a 15.2% CAGR to 2032 — and pairs it with operational templates and procurement-ready assets to shorten your time to value.
For procurement teams, security architects, and executive sponsors preparing 2026 budgets and roadmaps, this report reduces ambiguity and accelerates decision cycles. To access the full dataset, vendor scorecards, and PoC templates that underpin our strategic recommendations, please visit the PW Consulting report page for subscription and licensing information.
For detailed analysis of this topic, please visit the official page: Worldwide Cloud IDS IPS Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com